Customizing Roofers Insurance for Maximum Protection

Navigating the world of insurance can be daunting, especially for specialized professions like roofing. Roofers face unique risks and challenges, making it crucial to have a tailored insurance policy that provides comprehensive coverage. In this blog, we’ll explore how to customize roofers insurance to ensure maximum protection, addressing specific needs and potential risks.
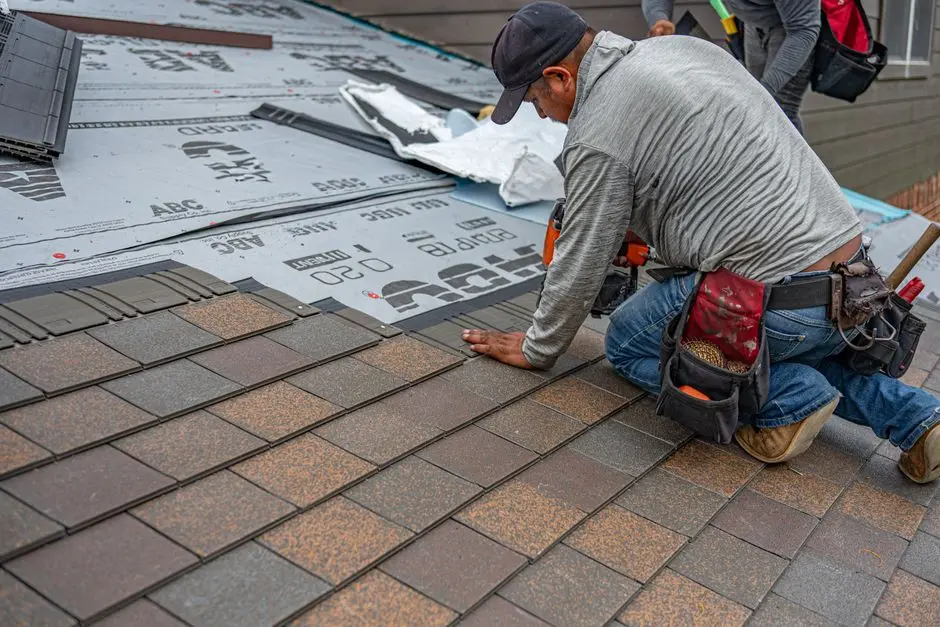
Skilled roofer installing asphalt shingles, ensuring quality home renovation.

Understanding the Risks in the Roofing Business

Roofers encounter numerous risks daily, from working at great heights to handling heavy materials. Accidents can occur in the blink of an eye, and factors such as weather conditions or equipment malfunction can exacerbate these risks. Slip and fall accidents are common, given the nature of rooftops and the materials used, while the potential for more serious incidents—like falling off a roof entirely—remains a significant concern. Understanding these risks is the foundation upon which comprehensive insurance is built. By grasping these potential hazards, roofers can make more informed decisions about what specific coverages to include in their insurance policy to reduce potential liabilities and protect their workforce.

In addition to physical risks, roofers also face liability risks when accidents or damages occur while working on client properties. This includes scenarios where workers accidentally damage a client’s property during installation or repair. Environmental factors, such as storms or extreme heat, can also contribute to the unpredictability and danger of the work environment. Fires and water damage can arise from unexpected weather changes, impacting not only the project at hand but the overall safety of the job site. By acknowledging these risks, roofers can adequately inform their insurance providers to ensure all such eventualities are covered, safeguarding their business operations.

Essential Insurance Components for Roofers

A comprehensive insurance strategy for roofers should encompass a variety of essential coverage components. General liability insurance acts as the bedrock, protecting your business against claims related to bodily injury or property damage that may arise while conducting work on clients’ roofs. This type of insurance is indispensable as it mitigates financial risks associated with litigation and compensatory claims from third parties. Without it, a single accident could potentially shutter your business due to overwhelming legal fees or settlements.

Another critical component is workers’ compensation insurance. This covers medical expenses and lost wages for employees injured on the job. Considering the inherent dangers of roofing, this type of insurance is non-negotiable for those in the industry. Additionally, property insurance is essential as it provides coverage for the physical assets of your business, such as equipment and tools, which are vital for daily operations. Together, these components not only offer a safety net but also convey professionalism and responsibility to clients, reassuring them that you are a credible business capable of managing unexpected incidents.

Tailoring Coverage to Fit Your Business Needs

Every roofing business is different, and therefore, needs a personalized approach to insurance. For small businesses or freelancers, a basic coverage package like general liability may suffice initially. However, as your business grows or your operations expand, additional coverages become necessary. For instance, operating in a high-risk area might require a more robust property insurance policy to account for increased exposure to environmental hazards. Furthermore, if your company undertakes diverse services such as installation, repair, and maintenance, consider policies that cater specifically to these varied jobs to ensure comprehensive protection.

Insurance needs can also vary depending on the geographical location of the roofing business. For instance, businesses operating in hurricane-prone areas may need to include specialized coverage to protect against storm damage. Similarly, companies might need to secure additional endorsements that cover subcontractors if they frequently use third-party services. An effective strategy involves closely examining historical data and future forecasts specific to your area to identify potential risks better and work with your insurance provider to tailor a policy that is as exhaustive as it is cost-effective.

Working with Insurance Providers for Optimal Cover

Choosing the right insurance provider can make all the difference. Building a strong relationship with your insurer is key to securing a policy that addresses your precise business needs while remaining financially feasible. When evaluating potential providers, consider their track record in serving businesses similar to yours and their ability to adapt policies as industry standards and legal requirements evolve. Transparency is crucial, so it is important to communicate openly about your business operations and any unique aspects that might affect coverage. This level of communication ensures your insurance policy is continuously aligned with your business’s evolving dynamics.

Engaging with insurance providers isn’t just a one-off transaction; think of it as an ongoing partnership. Provide your insurance agent with updates on any changes in your business model, such as diversification of services or expansion to new locations, which might necessitate adjustments in coverage. Insurers can offer insights into best practices for risk management and expose you to additional services like regular safety audits, which can lead to potential discounts on premiums, effectively lowering long-term costs while enhancing the safety of your operations.

Balancing Cost with Comprehensive Coverage

Insurance premiums can take a significant bite out of your business budget. Finding the sweet spot between affordability and adequate coverage can be challenging, but it’s not impossible. One effective strategy is to leverage bundling options provided by insurers. By combining multiple policy types—like general liability, property, and workers’ compensation—into one comprehensive package, businesses can often save significantly on overall costs. Moreover, higher deductibles can lower monthly premiums, but this should be approached cautiously as it shifts greater financial risk onto the business.

Another approach is conducting regular risk assessments to pinpoint areas where safety measures can be increased, potentially lowering insurance costs over time. Implementing on-site safety training and investing in quality equipment to reduce accident rates are proactive steps that demonstrate a commitment to minimizing risks, which insurers often recognize through premium reductions. By being strategic about the way risks are managed and leveraging the expertise of insurance providers, roofing businesses can successfully balance the need for comprehensive coverage with the constraints of their budget.

Securing Your Roofing Business with Customized Insurance

Customizing roofers insurance is not just about protecting your business but also about providing peace of mind. By understanding the unique risks your roofing business faces, you can tailor an insurance policy that covers all bases. This not only ensures safety but also allows you to focus on what you do best, knowing that your business is well protected. Consider working collaboratively with your insurance provider to tailor a policy that suits your specific needs, striking a balance between comprehensive coverage and cost-efficiency.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com


12 Questions to Ask Before Buying Window Installation Insurance

Choosing the right insurance for window installation can be a daunting task. With so many options to consider, it’s essential to know the right questions to ask to ensure you’re making an informed decision. In this listicle, we’ll guide you through the crucial questions to help you secure the best coverage for your needs.

1. What Does the Policy Cover?

Understanding the scope of your insurance policy is crucial. Ensure the policy provides coverage for all potential damages or liabilities related to window installation. This might include things like accidental damage to the windows during installation or injury to the installation team. It’s also vital to consider if the policy covers structural damage to your property that might occur during the process of installation. Always inquire deeply into the specifics of coverage, as general terms can sometimes mask the true extent of what an insurance policy includes. Knowing exactly what is covered can save you from unexpected costs in the future.

2. Are There Any Exclusions?

Every insurance policy comes with its exclusions. You should be aware of what circumstances or damages aren’t covered to avoid surprises later. Exclusions can often include pre-existing damages or wear and tear that occurs over time, which aren’t typically covered. Some policies might also exclude coverage for natural disasters unless specifically added to the policy. It’s important to ask the insurance provider for a clear explanation of exclusions, as this understanding will help prevent miscommunications and ensure you have the right expectations about what will be supported if you need to file a claim.

3. What is the Coverage Limit?

Check the maximum amount the insurance will pay out in the event of a claim. This will help determine if the coverage aligns with your project’s needs. Knowing your coverage limits is essential to assessing how protected you will be in worst-case scenarios. Sometimes, the financial repercussions of an incident might exceed the limit set by your policy, leaving you with a substantial out-of-pocket expense. To best protect your investment, evaluate whether the coverage limits are sufficient for both routine installations and larger scale or more complex window setups.

When examining coverage limits, it’s also beneficial to compare limits across different policies to ensure you’re getting the best deal for your needs. Some policies may appear similar at first glance but have significant differences in payout limits, which can be crucial during a claim. Therefore, conducting a thorough analysis is key to making a wise decision.

4. What Are the Premium Costs?

Knowing the cost of premiums is essential for budgeting. Compare different policies to ensure you’re getting a fair rate for the coverage provided. Insurance premiums can vary based on the extent of coverage, the insurer, and other factors, so it’s important to look at what you’re getting for your monthly or annual payment. When deciding, consider the balance between cost and benefit; the cheapest policy may not provide the thorough coverage you need, which could lead to more significant expenses should a claim arise. Therefore, it’s vital to find a policy that offers the best value for its price.

5. Is There a Deductible?

Find out if you’ll need to pay a deductible before the insurance kicks in. Understanding out-of-pocket costs is important for financial planning. Deductibles can significantly affect your cash flow, especially if a claim needs to be made quickly. In some cases, opting for a higher deductible might lower your premium costs, but this trade-off needs careful consideration based on your financial capability to cover that initial expense. As you review your policy options, consider both your current financial situation and potential future incidents that could require a claim.

6. How Easy is the Claim Process?

Inquire about the steps involved in filing a claim. A smooth and efficient process is crucial in the event of an incident. Insurers should be able to provide a clear outline of the claim process, including the necessary documentation and the expected timeframe for a response. Consider policies that offer streamlined digital claim filing options or dedicated customer support that can ease the burden when a claim needs to be filed. Understanding this process before you commit to a policy can prevent stress and confusion during what is already a trying time.

7. Are There Discounts Available?

Some companies offer discounts for bundling policies or installing safety features. Explore your options for potential savings. By combining different types of insurance—like liability and property insurance—you might receive a discounted overall rate. Additionally, installing advanced security measures on your property can not only protect against damage and theft but might also earn you a reduction in your insurance costs. Always ask your insurer about available discounts and actively seek ways to qualify for them as part of your negotiations.

8. Who is the Underwriter?

Research the insurance company or underwriter. A reputable company can provide peace of mind that claims will be handled fairly. Looking into customer reviews and ratings for these companies online can provide insight into their reliability and customer service. Try to find underwriters with a solid history and positive customer feedback, ensuring you are partnering with a company that’s trustworthiness is equal to the quality of service they offer. This research helps establish a partnership based on trust and reassurance.

9. How Long is the Policy Term?

Understand the duration of your coverage. Make sure it aligns with your needs or any specific project timelines you have in mind. Some projects may have extended timelines, making it essential that your insurance policy can cover the entire duration without requiring renewal. Check if the policy length is adaptable or if there are options to extend the coverage without significant cost increases. Evaluating the policy term allows for efficient planning and helps prevent gaps in coverage.

10. Are There Policy Renewal Terms?

Check what happens at the end of your policy term. Knowing renewal terms can prevent any lapse in coverage. Some policies automatically renew, while others may require action on your part to continue coverage. Understanding these terms ensures you remain continuously protected. Additionally, engaging with the insurer about potential changes in terms or costs upon renewal can prepare you better for any adjustments you might need to make to maintain coverage.

11. What About Customer Support?

Good customer support is invaluable. Verify that the provider offers reliable assistance when you need it. Immediate access to knowledgeable representatives can influence your overall satisfaction with your insurance provider, especially during emergencies. Evaluate their support systems, including the availability of online resources, chat support, and phone assistance, to ensure you can access help whenever necessary. This aspect of service is often overlooked but contributes significantly to the user experience.

12. Can the Policy Be Customized?

Your needs might be unique, and a one-size-fits-all policy may not be ideal. Ask about custom options to tailor the insurance to fit your specific requirements. Customization could involve adding specific coverage types to protect against unique risks associated with your installation techniques or business model. Working closely with a provider that values personalized attention can lead to more effective coverage and potentially significant long-term savings by only paying for what you genuinely need.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com
 

Is Contractor Insurance NY Cost Worth the Investment?

If you’re a contractor in New York, navigating the complex world of insurance can be daunting. You may wonder if contractor insurance is worth the investment, especially considering the costs involved. In this blog, we’ll break it down for you, making sure you have all the information needed to make an informed decision.

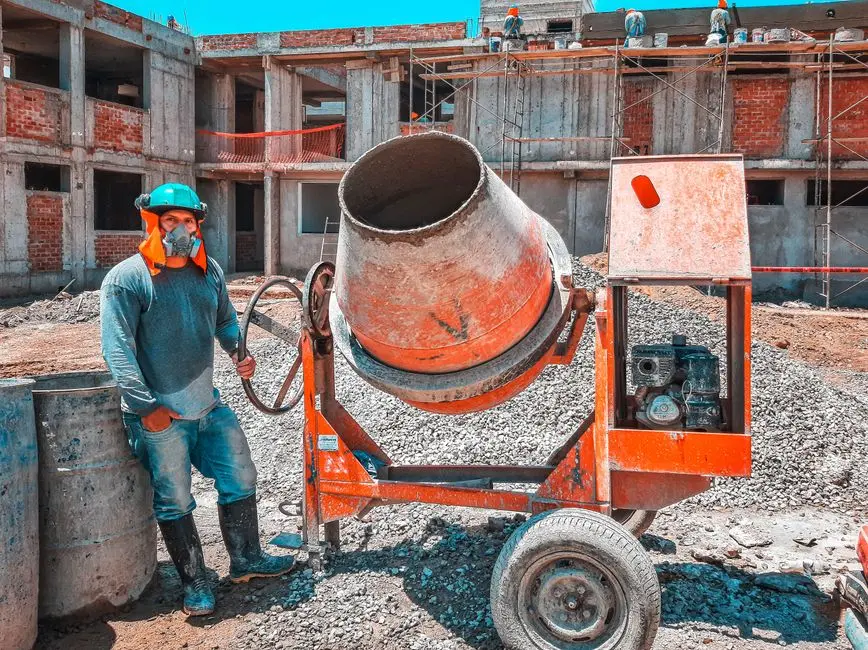
A construction worker operating a concrete mixer at an active building site, emphasizing safety gear.

Understanding Contractor Insurance Basics

Before diving into costs, it’s essential to understand what contractor insurance covers. Typically, it includes general liability, workers’ compensation, and sometimes professional liability insurance, protecting against accidents, injuries, and professional errors.

General liability insurance covers common risks like property damage and bodily injury claims, which can occur on a construction site. This type of coverage is indispensable, as it shields contractors from the financial blow of lawsuits, medical costs, and repair expenses that could arise from accidents.

Workers’ compensation insurance, on the other hand, is crucial for businesses with employees. It covers medical expenses and wage replacement for workers injured on the job, ensuring you comply with New York state laws while taking care of your team.

Professional liability insurance, often called errors and omissions insurance, is essential for contractors offering design or consulting services. This insurance provides protection from claims of negligence or incomplete work, which can be costly and damaging to reputation.

Weighing the Cost vs. Benefits

Contractor insurance in New York can seem costly, but it’s crucial to weigh these costs against the benefits. Insurance can protect you from hefty legal fees and payouts in case of lawsuits, potentially saving much more money than the premium costs.

While the price of insurance premiums can often be a concern, consider the peace of mind you gain in return. Being covered for unexpected incidents enables you to focus on what you do best—running your business—without the constant worry of potential financial ruin.

Moreover, having adequate insurance coverage can enhance your credibility as a contractor. Clients are more likely to trust and hire contractors who display a commitment to safety and liability coverage, giving you a competitive edge in the marketplace.

Assessing Your Specific Risks

Contractors face varying risks depending on their industry and the scale of their projects. Analyzing these risks helps determine the level of coverage necessary, ensuring you aren’t over-insured or under-insured.

For example, a contractor specializing in high-rise structures might face significantly higher risks compared to one working on residential homes. Understanding such distinctions can guide you in tailoring your insurance needs appropriately.

It’s also useful to consider any geographical risks specific to New York, such as severe winter weather conditions that could lead to delays and accidents. Factoring these elements into your risk assessment ensures comprehensive coverage.

Choosing the Right Insurance Plan

Once you’ve assessed the risks, selecting the right insurance plan is vital. This involves finding a reputable insurance provider and ensuring the policy aligns with your business’s unique needs and budget.

Consultation with insurance experts or agents can provide valuable insights, helping you navigate the myriad of policies available and find one that aligns with your operational requirements.

Customizable insurance plans allow you to build a policy that fits your exact needs, ensuring you’re not paying for coverage you don’t require while also avoiding uncovered liabilities.

Reviewing client and peer reviews can also be an effective way to evaluate insurance providers and their customer service, thus securing a trustworthy partner in your business journey.

The Long-Term Value of Contractor Insurance

While initial costs may deter some, the long-term value of contractor insurance includes peace of mind, safeguarding your business’s reputation, and compliance with legal requirements, all contributing to sustainable business growth.

Investing in comprehensive coverage now can prevent financial distress later, ensuring continuity of operations and stability in your business, regardless of unforeseen challenges.

Additionally, maintaining consistent insurance coverage builds trust with clients and partners, portraying reliability and professionalism, which are vital for building strong, lasting business relationships.

Ultimately, contractor insurance serves as an indispensable tool that not only protects but also propels your business towards its growth objectives, guaranteeing both financial security and a solid market standing.

Is Contractor Insurance a Smart Investment?

In conclusion, contractor insurance in NY may seem like an additional expense, but it’s an investment in your business’s future. Protecting yourself from potential liabilities, enhancing your professional credibility, and ensuring peace of mind are all invaluable benefits that outweigh the costs. Evaluate your specific needs and choose the right insurance plan to secure your business with confidence.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com


10 Key Facts About Workers’ Compensation Insurance NYC Every Contractor Should Know

Navigating the world of workers’ compensation insurance in New York City can be challenging, especially for contractors. Understanding the key aspects can help protect your business and ensure compliance. Here are ten essential points that every contractor should be familiar with.

Silhouette of construction workers on a building site with one pointing towards the distance.

1. Understanding Workers’ Compensation Basics

Workers’ compensation is a type of insurance that provides benefits to employees who get injured or fall ill due to their job. It covers medical expenses and a portion of lost wages, ensuring that workers are protected while on the job. This insurance acts as a crucial safety net for employees, providing them with the necessary support when unexpected incidents occur. Not only does it furnish financial relief but also peace of mind, knowing that medical costs and recovery expenses are taken care of.

For contractors, understanding the distinctions between various types of workers’ compensation coverage is essential. It helps in selecting the most appropriate plan that aligns with the nature of the job and the potential risks involved. Moreover, having a clear grasp of the coverage scope aids in addressing any anomalies during the claim process, enhancing the overall efficiency and transparency of interactions with insurance providers.

In New York City, it is mandatory for employers, including contractors, to carry workers’ compensation insurance for their employees. Failure to comply can result in severe penalties, including fines and potential business shutdown. Contractors should be aware of these legal obligations to avoid costly mistakes and ensure a smooth operational flow.

Navigating the legal landscape of workers’ compensation insurance in NYC requires staying updated with the latest regulations. The rapid evolution of policies necessitates continuous learning and adaptation, making it crucial for contractors to stay informed and consult with legal experts when needed. Understanding the nuances of laws not only minimizes legal risks but also fosters a compliant and ethical work environment.

3. Who Needs Coverage

Generally, all employees, whether part-time, full-time, or seasonal, must be covered under a workers’ compensation policy. Even subcontractors may need coverage depending on their work arrangement and state requirements. Determining the appropriate coverage protects both the workforce and the business from unforeseen liabilities.

It’s crucial for contractors to assess their workforce structure and identify roles that necessitate coverage under workers’ compensation insurance. This assessment involves scrutinizing employment contracts, evaluating work arrangements, and understanding the legal obligations pertinent to each employment type. Establishing a comprehensive coverage regime, thus, mitigates risk exposure and enhances the safety net for everyone involved.

4. Cost Factors Affecting Premiums

The cost of workers’ compensation insurance in NYC depends on several factors, including the type of work, the number of employees, and the company’s claims history. Understanding these factors can help contractors manage their insurance costs effectively. Companies operating in high-risk industries typically encounter higher premiums due to the increased likelihood of workplace incidents.

Additionally, maintaining a safe work environment and adhering to regulatory safety standards can positively impact insurance costs. Implementing risk management strategies, such as employee safety training and regular site inspections, can significantly reduce workplace accidents and claims, thereby lowering premiums over time. Proactive investment in safety not only decreases costs but also enhances overall employee well-being.

5. How Claims Are Processed

When a worker files a claim, it typically involves reporting the injury, seeking medical attention, and submitting necessary documentation. The insurance provider will then review the claim and determine compensation eligibility. A seamless claims process requires clear communication and efficient coordination between all parties involved.

To expedite claims, contractors should ensure that proper documentation procedures are in place. This includes timely reporting of incidents, meticulous record-keeping, and precise communication with insurance representatives. Providing accurate and detailed accounts in documentation aids in swift claim resolution and minimizes disruptions to business operations, allowing employees to recover without additional stress.

6. The Role of the New York State Workers’ Compensation Board

This state agency oversees the workers’ compensation system, ensuring that laws are followed and disputes are resolved fairly. They are also involved in licensing and regulating insurance carriers. Their role is pivotal in maintaining the integrity of the workers’ compensation framework across New York.

The Board plays an essential part in educating both employers and employees about their rights and responsibilities under the workers’ compensation system. Their guidance publications and online resources are valuable tools for understanding and complying with the regulatory landscape. Engaging with the Board’s resources can greatly assist contractors in navigating complex insurance matters and resolving disputes efficiently.

7. Penalties for Non-Compliance

Contractors who fail to secure appropriate insurance face hefty fines and possible lawsuits. It’s crucial to maintain valid insurance to avoid these risks and protect your business integrity. Non-compliance not only leads to financial strains but can also hinder the ability to secure contracts and maintain client trust.

Being vigilant about compliance is not merely a legal obligation but also a cornerstone of responsible business practice. Regular audits and reviews of insurance policies ensure up-to-date coverage and compliance with statutory requirements, safeguarding the business against potential legal and financial pitfalls.

8. Managing Workplace Safety

Implementing safety measures and training programs can reduce the likelihood of workplace accidents and subsequently lower insurance premiums. A safe work environment benefits everyone involved. Investing in ongoing training ensures that employees are aware of the best practices and equipped to handle safety challenges effectively.

Creating a culture of safety requires commitment from all levels of management. Encouraging open communication about safety concerns, regularly reviewing safety protocols, and rewarding compliance can foster a proactive approach towards minimizing hazards. Such initiatives result in a robust safety culture, reducing the incidence of claims and enhancing the reputation of the business.

9. Tips for Selecting the Right Insurance Provider

Consider factors like provider reputation, customer service, and pricing when selecting an insurance carrier. It’s important to find a reliable partner that understands the unique needs of contractors. Comparing various providers and seeking recommendations from industry peers can aid in making an informed decision.

When evaluating potential insurance providers, it’s essential to assess their experience in handling workers’ compensation claims. Providers with a strong track record of efficiently resolving claims and offering exceptional support can be invaluable, ensuring that your workforce receives timely and appropriate care when needed. Trust and reliability are key components in fostering a successful partnership with your insurance provider.

10. Keeping Up with Legislative Changes

Workers’ compensation laws can change, affecting coverage requirements and costs. Staying informed about these changes ensures that you remain compliant and adequately covered. Regularly reviewing industry updates and consulting with legal professionals can keep contractors abreast of legislative developments.

Embracing a proactive approach to legislative awareness helps in anticipating changes before they impact your business operations. Establishing relationships with industry associations and subscribing to relevant newsletters are effective strategies in staying informed. Being prepared for legislative shifts maintains smooth compliance and continuous protection for both employees and the business.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com


Why is my liability insurance excluding labor law claims?

Navigating the complex world of insurance policies can be challenging, especially when you discover that labor law claims are not covered by your liability insurance. In this FAQ, we’ll break down the reasons behind this exclusion and help you understand what it means for your coverage.

Understanding Liability Insurance

Liability insurance is designed to protect your business from claims involving bodily injuries or property damage. However, it’s important to know its limitations, especially concerning employment-related issues.

Most businesses invest in liability insurance to safeguard against unforeseen incidents that may lead to financial loss. While it is a broad safety net, the intricate details can sometimes be confusing. It’s not uncommon for policyholders to assume they’re covered for all potential liabilities, only to find exceptions like labor law claims. Knowing these distinctions beforehand can save you from unexpected surprises in a crisis.

What Are Labor Law Claims?

Labor law claims typically involve employment practices issues, such as wrongful termination, discrimination, and harassment. These claims often require different types of coverage from typical liability insurance.

In the workplace, various challenges may arise between employers and employees. Labor law claims are focused on situations where employees believe their rights have been violated under employment law. Cases such as sexual harassment or discrimination due to race, gender, or age fall under this category. As these situations can have severe legal and financial repercussions, they demand particular attention and coverage.

Why Labor Law Claims Are Excluded

Most liability insurance policies exclude labor law claims because they fall under employment practices liability. Handling these claims requires specialized policies that address the risks associated with employment practices.

The exclusion of labor law claims from general liability insurance is primarily due to the specialized nature of these risks. Insurance companies tailor their offerings based on common exposures that businesses face. Since employment-related issues need nuanced policy frameworks, they are segmented into separate policies like Employment Practices Liability Insurance (EPLI). This separation helps to cater specifically to the complexities of employment laws, which vary greatly from state to state and even industry to industry.

Exploring Employment Practices Liability Insurance

To address labor law claims, businesses often need to purchase Employment Practices Liability Insurance (EPLI). This coverage specifically deals with the risks associated with employment practices, providing protection against claims made by employees.

EPLI is a crucial tool for businesses looking to protect themselves from costly lawsuits filed under labor laws. This insurance helps cover legal costs linked with defending your business against claims and also addresses settlements or court rulings. As employment laws evolve, having an EPLI policy ensures that your business remains secure and resilient against emerging legal challenges.

In light of recent trends in workplace dynamics and increasing labor rights awareness, EPLI has become more relevant than ever. It covers a broad spectrum of potential employee grievances, giving managers and business owners peace of mind as they navigate complex employment landscapes. By opting for EPLI, companies can stay prepared amid a backdrop of ever-changing legal requirements in employment and labor relations.

Assessing Your Coverage Needs

It’s crucial to assess your business’s specific needs and risks to determine if you require additional coverage, such as EPLI. Consulting with an insurance specialist can provide guidance tailored to your business’s unique situation.

Every business operates differently, facing unique risks and challenges. Thus, assessing your coverage needs requires a thorough understanding of your organizational dynamics and potential vulnerabilities. An insurance audit in collaboration with a trusted advisor ensures you have a comprehensive understanding of your risk landscape. They can guide you not only towards acquiring the right policies but also help you implement preventive measures to mitigate these risks.

If you’re debating whether EPLI is necessary for your business, consider factors such as the size of your workforce, the regulatory environment you operate in, and past employee relations. Remember, prevention and preparedness are cheaper than remediation. Taking proactive steps to secure your business makes you not only resilient but also helps foster a healthier workplace by showcasing your commitment to fair and lawful employment practices.

Final Thoughts on Liability Insurance Exclusions

Understanding why labor law claims are excluded from your liability insurance can help you better navigate your coverage options and address any gaps. Always consult with your insurance provider or a specialist to ensure comprehensive protection tailored to your specific needs.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com


What should contractors know about labor law coverage for scaffolding?

Navigating the world of labor laws can be tricky, especially when it comes to ensuring your construction site is up to code with scaffolding regulations. As a contractor, it’s crucial to understand what labor law coverage means for you and your workers. This blog will break down the essentials.

Two construction workers on bamboo scaffolding, wearing safety gear under a clear blue sky.

Understand the Importance of Labor Law Coverage

Labor law coverage is fundamental to protecting both employees and employers. As a contractor, knowing the ins and outs ensures you are prepared for any legal obligations that could arise from using scaffolding on site.

Labor laws are designed to ensure safe working environments and fair practices. For contractors overseeing projects involving scaffolding, understanding these laws is particularly vital. Not only does labor law coverage protect you from potential lawsuits, but it also ensures the well-being of your workers. This dual protection can safeguard your company’s reputation and financial stability by preventing costly legal battles and demonstrating a commitment to safety.

For those wondering how to get labor law coverage for scaffolding and falls in NY, guidelines can vary significantly between jurisdictions. Therefore, consulting with experts familiar with local regulations can provide you with the necessary insight to remain compliant at all times.

Identify Key Regulations for Scaffolding

It’s vital to be knowledgeable about the specific regulations that apply to scaffolding, including load capacities, structural soundness, and safety measures.

Scaffolding regulations can be extensive, covering everything from design and structural requirements to safety protocols and inspection schedules. An integral aspect of these regulations is understanding the load requirements; scaffolding must be robust enough to withstand intended loads to prevent collapse risk. Regular inspections are mandated by law to ensure structural integrity is maintained throughout the project’s duration. Adhering to these guidelines is not just about compliance—it’s about creating a secure environment conducive to productivity and safety.

Consulting resources like OSHA’s scaffolding safety guidelines can provide comprehensive checklists and procedural insights. Understanding these regulations can help in assessing both the design and the practical applications of scaffolding on your site, ensuring you meet national standards.

Educate and Train Workers on Safety Standards

Providing proper training and regular safety briefings to your workers can help prevent accidents and ensure everyone is aware of the risks and how to mitigate them effectively.

Knowledge is power, and when it comes to safety, it’s also protection. Offering continuous education on safety standards ensures that all workers are equipped with the skills and knowledge necessary to handle scaffolding safely. Training sessions should be frequent and mandatory, covering emergency procedures and the proper use of personal protective equipment (PPE). By fostering a culture of safety, workers not only protect themselves but also contribute to a more efficient and harmonious work environment.

A proactive approach involves staying informed about the latest safety standard updates and incorporating them into your training programs. This commitment to ongoing learning encourages a safer work culture and minimizes accidents. As safety becomes second nature, incidents and near-misses are significantly reduced.

Document and Report Incidents Promptly

Having a reliable incident reporting process can protect your business from potential legal action. Ensure any accidents are documented accurately and reported in a timely manner.

Accurate documentation is crucial when dealing with workplace incidents. In the event of an accident, detailed records provide clarity that can mitigate legal repercussions. Implementing a rigorous reporting system encourages transparency, allowing for swift corrective action and helping to prevent similar occurrences in the future. Promptly reporting incidents as per the requirements of legal authorities and regulatory bodies not only fulfills legal obligations but also initiates a thorough investigation process, vital for culpability and corrective measures.

Doing a regular check-in with a legal expert helps keep you updated on any changes in the laws and how they may affect your operations, ensuring compliance and minimizing risks.

Legal landscapes change, and staying ahead means avoiding potential pitfalls. Regular consultations with legal professionals give you access to up-to-date information and strategic advice tailored to your specific needs as a contractor. Engaging with experienced legal advisors not only ensures you are not caught off guard by legal amendments, but it also provides peace of mind in knowing that your operations remain legally sound and compliant.

Wrapping Up On Scaffolding Safety

Understanding labor law coverage for scaffolding is crucial for preventing accidents and legal issues at construction sites. With the right knowledge and preparation, contractors can ensure a safer environment for their workers and comply with regulations. To learn more about how we can assist you, visit our homepage and ensure your projects are safeguarded against any potential risks.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com


8 Reasons Scaffolding Insurance is Essential for Your Construction Business

Running a construction business comes with its own set of challenges and risks, and when it comes to scaffolding, those risks can significantly impact your operations. Scaffolding insurance might seem like just another checkbox for your business, but it’s essential for a variety of reasons. In this blog, we’ll explore why having scaffolding insurance is more than just a good idea—it’s a necessity.

Silhouetted construction workers on scaffolding in an urban environment under blue skies.

1. Protecting Your Workforce

Ensuring the safety of your workers is paramount, and scaffolding insurance provides a safety net that protects them from accidents and injuries. This insurance not only offers financial coverage but also peace of mind for everyone on site.

Working at heights is inherently risky, and even the most experienced workers can find themselves in precarious situations. In case of an accident, scaffolding insurance helps cover medical costs and related expenses, protecting not just the workers but the company’s financial stability. It’s important to make sure that worker safety is prioritized at all times to maintain a safe and productive work environment.

2. Mitigating Financial Risks

Unexpected accidents can quickly escalate into overwhelming financial burdens. With scaffolding insurance, your business can avoid hefty out-of-pocket expenses, protecting your bottom line from unforeseen incidents.

Imagine a scenario where an unexpected accident halts your project. Without scaffolding insurance, the costs for medical bills, legal fees, and equipment repair could cripple your finances. This type of insurance acts as a buffer, absorbing these financial shocks so your business can recover swiftly and continue operations. Having a risk management plan can complement your insurance policy, ensuring a robust safety strategy is in place.

3. Compliance with Regulations

In many regions, carrying insurance is not just recommended, it’s required. Scaffolding insurance helps ensure that your construction business complies with local regulations, avoiding legal issues and potential fines.

Compliance with regulations is more than meeting minimum safety standards; it’s also about positioning your business as a responsible entity. This not only prevents costly fines and legal encounters but also builds trust with your clients by showing them your commitment to operating lawfully and ethically. Understanding the relevant construction regulations in your area can help prepare your business for inspections and audits.

4. Enhancing Business Reputation

Having comprehensive insurance coverage demonstrates professionalism and reliability to clients. It shows that your business values safety and responsibility, enhancing your reputation in the competitive construction market.

Your business reputation is an invaluable asset. By investing in scaffolding insurance, you’re letting potential clients know that you care about quality, safety, and reliability. This reassurance can be the deciding factor for clients choosing between your services and another company’s. Furthermore, an enhanced reputation opens doors to more business opportunities, fostering growth and stability in an ever-competitive market.

5. Safeguarding Against Equipment Damage

Equipment damage can lead to project delays and increased costs. Scaffolding insurance covers repairs and replacements, ensuring your projects continue smoothly, without unplanned downtime.

The costs associated with equipment failure can be substantial, not to mention the delays and potential loss of contracts that can occur. With scaffolding insurance, repairs and replacements of damaged equipment are covered, which allows your projects to maintain their timelines and your business to keep its commitments. Continuous investment in high-quality equipment, supported by an insurance plan, guarantees operational efficiency throughout your projects.

6. Navigating Liability Claims

Liability claims can arise from various incidents on a construction site. Scaffolding insurance provides coverage for legal costs and settlements, protecting your business from the financial strain of legal proceedings.

No matter how thorough your safety measures are, accidents can happen, and they can lead to costly liability claims. Scaffolding insurance helps protect your business by covering the potential expenses for legal defense and settlements, preventing litigation costs from affecting your bottom line. Proactively addressing liability issues through insurance allows you to focus more on your core business activities without the looming worry of potential lawsuits.

7. Peace of Mind for Project Managers

With the complexity involved in managing construction projects, having scaffolding insurance allows project managers to focus on delivering quality work without the constant worry of potential risks and accidents.

Project managers have enough on their plates without adding the stress of potential scaffolding accidents. Scaffolding insurance provides peace of mind, allowing them to focus on project delivery. Managers can rest assured that the financial repercussions of any mishaps are covered, enabling them to maintain productivity and project integrity. Regularly reviewing your insurance needs and ensuring comprehensive coverage can help in streamlining project management efforts.

8. Facilitating Business Growth

With the right insurance, your business is better positioned to take on larger projects and expand operations. Insurance coverage makes it easier to secure contracts and forge partnerships, contributing to your business’s growth and success.

Insurance isn’t just about protection; it’s a tool for growth. By providing a safety net, scaffolding insurance enables your business to pursue larger contracts and enter into new markets with confidence. This security not only attracts clients but also potential partners looking for reliable collaborators. Leveraging insurance to explore new business avenues can significantly enhance your competitive edge and drive your business forward on the path to sustained success.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com


Navigating Contractor Insurance Requirements with Ease

In the world of contracting, understanding insurance requirements can feel overwhelming. However, it’s a crucial aspect of running a successful contracting business and protecting yourself from potential risks. In this blog, we’ll break down the essentials of contractor insurance requirements in an easy-to-understand manner.

Portrait of a construction worker with a tape measure, working indoors.

Why Contractor Insurance is Important

Contractor insurance provides vital protection against financial losses that can result from accidents, property damage, or liability claims. Understanding its importance helps contractors make informed decisions about the coverage they need.

Imagine a scenario where an unexpected accident occurs on the job. Without insurance, the financial burden of medical bills and potential lawsuits could cripple a business. Contractor insurance serves as a protective shield, absorbing such financial shocks and allowing contractors to focus on their work without constant worry. It’s also worth noting how insurance enhances a contractor’s professional image. Clients are more likely to trust and hire professionals who can demonstrate they are fully covered, giving them peace of mind that any mishaps will be dealt with effectively.

Types of Insurance Coverage Contractors Need

There are several types of insurance coverages contractors should consider, including general liability, professional liability, and workers’ compensation. Each type serves a specific purpose and addressing all potential risks can help keep a contracting business safe.

General liability insurance covers common risks like bodily injury or property damage and is often the first policy contractors acquire. Professional liability insurance, often known as errors and omissions insurance, protects against claims of negligence or mistakes in service. It’s particularly important for contractors who provide specialized advice or services. Workers’ compensation insurance is crucial for businesses with employees, covering medical expenses and lost wages if an employee is injured on the job. With these coverages, contractors can tackle a wide range of uncertainties with confidence.

Beyond the basics, contractors might also consider builder’s risk insurance, which covers buildings under construction, or commercial auto insurance for vehicles used in business operations. Each category serves unique aspects of a contractor’s operations and safeguarding these areas can prove invaluable. Knowing which insurance policies to prioritize can make a huge difference in handling unforeseen events and maintaining smooth business operations.

How to Determine Your Insurance Needs

Assessing your business type, size, and operational risks can help determine the right mix of coverages. It’s essential to evaluate your individual business needs to choose an insurance plan that best fits.

Start by evaluating the scope of your services and the typical risks involved. Consider the size of your projects and number of employees. For example, a large construction company may need more extensive coverage compared to a small consultancy. Ensure you’re also considering potential cyber risks if you deal with sensitive data. It’s about balancing comprehensive protection with cost-effectiveness, ensuring you’re neither underinsured nor overpaying. Regular reviews of insurance needs are also crucial as your business grows or changes.

Finding the Right Insurance Provider

Selecting a reputable insurance provider involves research and comparisons. It’s important to find a provider who understands your industry and offers reliable coverage options tailored to your specific needs.

Start by seeking recommendations from peers within the industry or professional associations. Then, gather quotes from multiple agencies and evaluate what each provider offers in terms of coverage limits, exclusions, and premiums. Look at customer reviews and check the financial stability of the insurance companies, as noted by third-party ratings. Choosing a provider who is communicative and responsive can be just as important as the technical aspects of a policy, especially when questions or claims arise. Furthermore, establishing a good working relationship can lead to better-negotiated terms in future policy renewals.

Common Pitfalls to Avoid in Contractor Insurance

Mistakes in navigating insurance requirements can lead to costly consequences. Avoiding common pitfalls like underestimating required coverage or misunderstanding policy terms can help you protect your contracting business efficiently.

One prevalent mistake is failing to read the fine print thoroughly, leading to surprises when claims arise. It’s vital to understand exclusions and what situations are not covered. Contractors also often overlook updating their policies to reflect business growth or changes in operations. Over time, projects may become larger or more complex, requiring different coverage levels. Regularly reassess your policy to ensure it aligns with your current operations. Misjudging the extent of liability needed can leave gaps in protection, so it’s wise to err on the side of seeking more guidance rather than less when uncertain.

Wrapping Up: Ensuring Peace of Mind with the Right Coverage

By understanding the essentials of contractor insurance requirements, you can confidently navigate your insurance options and ensure your business is adequately protected. Remember, the right insurance not only safeguards your business but also enhances your credibility with clients. Consider it an investment in your peace of mind and professional growth. Visit our homepage to learn more about how we can help safeguard your business.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com


Why Contractor Insurance NY is Essential for Your Business

Running a contracting business is both rewarding and challenging. From managing projects to handling client expectations, there’s a lot on your plate. One crucial element that is often overlooked is contractor insurance in New York. Let’s delve into why it’s essential for safeguarding your business and providing peace of mind.

A construction worker operating a concrete mixer at an active building site, emphasizing safety gear.

Understanding Contractor Insurance: What Does It Cover?

Contractor insurance typically covers a range of risks, including property damage, bodily injury, and contractual liabilities. Understanding these aspects helps protect your business from unforeseen events and potential lawsuits. For instance, if a passerby accidentally gets injured at your worksite, contractor insurance can cover the medical expenses arising from that incident. Moreover, it helps small businesses like yours navigate the financial burdens associated with accidents, offering a buffer that safeguards your assets. Thus, ensuring a comprehensive understanding of your insurance benefits and coverage can prevent financial strain and provide necessary security for your contracting business.

Additionally, contractor insurance often includes coverage for tools and equipment, which are crucial for day-to-day operations. Replacement costs can be exorbitant if your tools are lost, stolen, or damaged. Insurance designed for contractors extends to these aspects, reducing your downtime and helping you maintain service continuity. By ensuring all potential scenarios are covered, you not only protect your investments but also project reliability to your clients. Embracing comprehensive insurance reflects professionalism and assures clients that you are well-prepared for any unexpected circumstances.

In New York, contractors are legally required to hold specific insurance policies. This section will outline the mandatory requirements and how they affect your business operations. General liability insurance is a must, providing coverage against claims of injury or property damage. Additionally, workers’ compensation insurance is mandatory, ensuring employees injured on the job receive necessary medical care and wage replacement benefits. Compliance with these legal requirements not only averts fines and penalties but also strengthens your credibility with both clients and partners.

Furthermore, certain types of contracts might require additional insurance, such as umbrella policies or errors and omissions insurance. These types of coverage offer added protection, particularly for contracts involving higher risks. Adhering to New York’s insurance regulations also makes your business more appealing to potential clients who value security and reliability. By meeting these legal standards, you demonstrate your commitment to operating within set guidelines and your dedication to upholding the highest professional standards.

The Benefits of Having Contractor Insurance

Beyond compliance, contractor insurance ensures peace of mind, provides financial security, and boosts your company’s reputation. Here’s how having the right coverage can benefit your contracting business in the long run. One major benefit is its role in minimizing financial loss, especially when faced with lawsuits or claims from third parties. With insurance, your business assets are shielded, allowing for a smoother resolution of disputes. Additionally, contractor insurance showcases your dedication to quality and safety, which are critical for attracting and retaining high-profile clients.

Insurance also enhances your competitiveness in a crowded market. Clients feel reassured knowing that a business has the necessary protection in place, which can lead to more opportunities and can even justify premium pricing. Moreover, having a solid insurance plan can facilitate new business relationships, as partners or subcontractors prefer working with contractors who come prepared with comprehensive coverage. Thus, contractor insurance is not just about security – it’s also a strategic tool that enhances your market position and builds long-term client trust.

How to Choose the Right Insurance Policy

Selecting the right insurance policy can be daunting. We’ll guide you on assessing your business needs, comparing plans, and choosing a policy that offers comprehensive coverage while fitting your budget. Start by evaluating the specific risks associated with your contracting endeavors, including both typical challenges and unique circumstances that your projects may pose. Consulting with an insurance expert who understands the complexities of your industry can be incredibly valuable in aligning coverage with actual risks faced by your business.

Equipped with a clear understanding of your needs, you can then begin comparing different insurance providers. Pay attention to their reputation, the scope of coverage they offer, and the flexibility of their policies. Don’t shy away from seeking personalized quotes and engaging in comprehensive discussions about coverage options. Opting for a bespoke insurance policy that can be adjusted as your business grows will save you the stress of constantly switching providers, and ensure steady protection as your operations expand.

Common Mistakes to Avoid When Purchasing Contractor Insurance

Learn about the common pitfalls contractors face when securing insurance and how to avoid them to ensure you get the best coverage for your business. One typical mistake is underestimating the necessary coverage, leading to inadequate protection that leaves your company vulnerable to large claims. Similarly, contractors sometimes overlook the importance of updating their insurance policy as their business grows. Not tailoring your coverage can result in gaps that expose you to unexpected liabilities.

Another error is choosing a policy based solely on price without considering the specific needs and risks of your business. It’s crucial to prioritize value over cost, focusing on the comprehensive nature of the policy and the trustworthiness of the insurer. Lastly, not reading the fine print or understanding policy exclusions can lead to unpleasant surprises. Fully understanding your policy terms not only aids in choosing the right plan but equips you with the knowledge needed to leverage your insurance effectively in times of need.

Embrace Contractor Insurance: A Smart Business Decision

In conclusion, having contractor insurance in NY is not just a legal requirement but a practical necessity for your contracting business. It offers protection, ensures compliance with state laws, and enhances your business’s credibility. Investing in the right insurance plan today can save you from potential troubles tomorrow, allowing you to focus on what you do best—serving your clients.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com


12 Ways Building Project Insurance Safeguards Your Contractor Business

In the world of construction, unexpected challenges and risks are part and parcel of every project. As a contractor, you know the importance of protecting your business from potential liabilities. Building project insurance is a crucial tool that not only offers peace of mind but also safeguards your operations from unforeseen setbacks. In this blog, we’ll explore how building project insurance can be a game-changer for your contractor business.

Group of construction workers wearing hard hats assessing a site outdoors.

1. Protection Against Project Delays

Delays are an inevitable part of the construction landscape. Whether due to unforeseen weather conditions or unexpected supply chain disruptions, these hold-ups can significantly affect project timelines and costs. Having building project insurance in place means your business can efficiently handle the financial repercussions of such delays. It ensures that you can cover the additional expenses incurred, like penalties for late completion or extra labor costs, thereby keeping your projects on schedule. This proactive approach not only reduces stress but also reinforces your reputation as a reliable contractor in the industry.

2. Coverage for Accidental Damages

Construction sites are bustling hubs of activity, and accidents are just par for the course. From a wayward crane to a slip and fall incident, damages can happen in the blink of an eye. Building project insurance serves as a financial cushion, covering costs associated with repairing damage or replacing materials. This coverage alleviates the financial burden on your business, allowing you to focus on completing the project rather than worrying about unforeseen expenses. It also ensures that stakeholders trust your ability to manage and mitigate risks effectively.

Not only does this insurance cover tangible damages, but it also plays a crucial role in maintaining peace of mind. Knowing that the potential for loss is minimized allows you and your team to concentrate on executing the project to the best of your abilities, boosting productivity and morale across the board.

In today’s litigious climate, legal claims can pop up unexpectedly, stemming from issues like contract disputes or liability cases. One of the significant advantages of building project insurance is the legal protection it provides. This insurance can cover the costs associated with defending against claims, including legal fees and settlement costs. Notably, having this backing means you won’t be blindsided by legal expenditures that could potentially cripple the financial stability of your business.

Moreover, this layer of protection inspires confidence in your clients, as it illustrates your commitment to handling disputes professionally and responsibly. It reassures them that their investment is secure, increasing the likelihood of future collaborations and client referrals.

4. Safeguarding Against Theft or Vandalism

Construction sites, unfortunately, are prime targets for theft and vandalism during off-hours. The risk of losing expensive equipment or experiencing destruction of valuable project assets is a valid concern for any contractor. Building project insurance acts as a protective shield, covering the cost of replacing stolen items or repairing vandalized property. This not only prevents potential financial loss but also ensures your project timeline can proceed with minimal disruption.

In addition to covering losses, having insurance specifically for theft or vandalism can lead to enhanced security measures being implemented on site. The act of securing insurance often involves a review of your current security protocols, prompting improvements that can further deter criminal activities and uphold the integrity of your projects.

5. Ensuring Contractor Accountability

Building project insurance promotes adherence to industry regulations and best practices. By holding insurance, contractors are often better informed about the compliance requirements relevant to their projects, from safety standards to environmental regulations, ensuring fully compliant operations. This accountability reduces the likelihood of incurring fines or facing project shutdowns, both of which can be detrimental to your reputation and bottom line.

Furthermore, builders who are aware and respectful of compliance standards often see improvements in efficiency and project execution, attributed to streamlined processes and fewer setbacks. This accountability fosters trust with clients, who can be assured that their projects are being managed by professionals who prioritize safety and quality.

6. Financial Security and Peace of Mind

Financial security is paramount for any business, and construction is no different. With comprehensive building project insurance, contractors can enjoy a definitive sense of security knowing that their business is shielded from unexpected financial burdens. This peace of mind translates into the freedom to pursue more ambitious projects or invest in innovative technologies, fostering growth and expansion.

By eliminating the constant worry of potential financial ruin, insurance allows contractors to focus on what they do best—constructing exceptional buildings and infrastructure that cater to clients’ visions. This assuredness often leads to strengthened client relationships, reinforcing trust and encouraging repeat business.

7. Risk Management Strategy

In the volatile construction industry, risk management is not just an option; it’s a necessity. Insurance forms a critical component of any risk management strategy, offering a structured approach to identifying potential risks before they escalate into costly problems. With insurance, contractors can craft a comprehensive risk reduction plan, covering everything from site safety to project financing.

Implementing a robust risk management strategy also translates into enhanced project outcomes. It leads to more reliable project delivery, decreased likelihood of delays, and an overall increase in operational efficiency, providing a solid foundation for long-term business success.

8. Enhanced Reputation with Clients

Building and maintaining a strong reputation is vital in the construction field, where word-of-mouth and client testimonials play significant roles. One of the subtle, yet impactful benefits of holding building project insurance is the signal it sends to clients. It tells them you’re a serious, responsible business entity prepared to stand by your work under any circumstance. Clients are more inclined to trust contractors who showcase thorough preparedness, potentially leading to more business opportunities and partnerships.

9. Employee Safety and Welfare

The welfare of your employees is paramount; after all, it’s their hard work that brings each project to life. Building project insurance can include coverage for workplace injuries and health issues, ensuring that your team is well-cared for and protected when accidents occur. This commitment to safety helps to maintain morale and create a work environment where employees feel valued and secure.

Furthermore, by safeguarding your workforce’s well-being, you nurture a culture of loyalty and dedication. Employees who feel secure and supported are typically more productive and less likely to leave for other opportunities, resulting in a more cohesive and experienced team dedicated to your company’s long-term success.

10. Coverage Beyond Completion

Some building project insurance policies extend their coverage well beyond the completion of a project, a feature that can be particularly advantageous in certain scenarios. This means that latent defects or post-construction issues can be addressed without financial strain. Such coverage can be a significant selling point for clients who wish to mitigate future risks, offering them confidence in the longevity and quality of the project delivered.

11. Budget Management Aid

Sticking to a budget is invariably a challenge in construction, with numerous unexpected costs potentially arising. Building project insurance offers practical support in managing budgetary concerns by covering unforeseen expenses. This aid can mean the difference between maintaining profit margins and sustaining financial losses. It equips contractors with the ability to respond flexibly to budgetary pressures without the need to compromise on quality or timelines.

12. Competitive Edge in Bidding

In the competitive bidding arena, demonstrating preparedness can significantly enhance your chances of success. Building project insurance showcases a contractor’s readiness to handle any eventuality. This preparedness not only reassures potential clients but also places your bids in a favorable position, often tipping the scales in your favor when decisions are being made. Being well-insured distinguishes you from competitors and highlights your commitment to delivering seamless, secure projects.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com