Navigating Scaffolding Insurance Options in New Jersey and Beyond

Navigating the world of insurance can be daunting, especially when it comes to scaffolding. With various options available, it’s crucial to understand what best suits your needs, whether you’re operating in New Jersey or elsewhere. In this guide, we’ll break down the essentials of scaffolding insurance to help you make informed decisions.
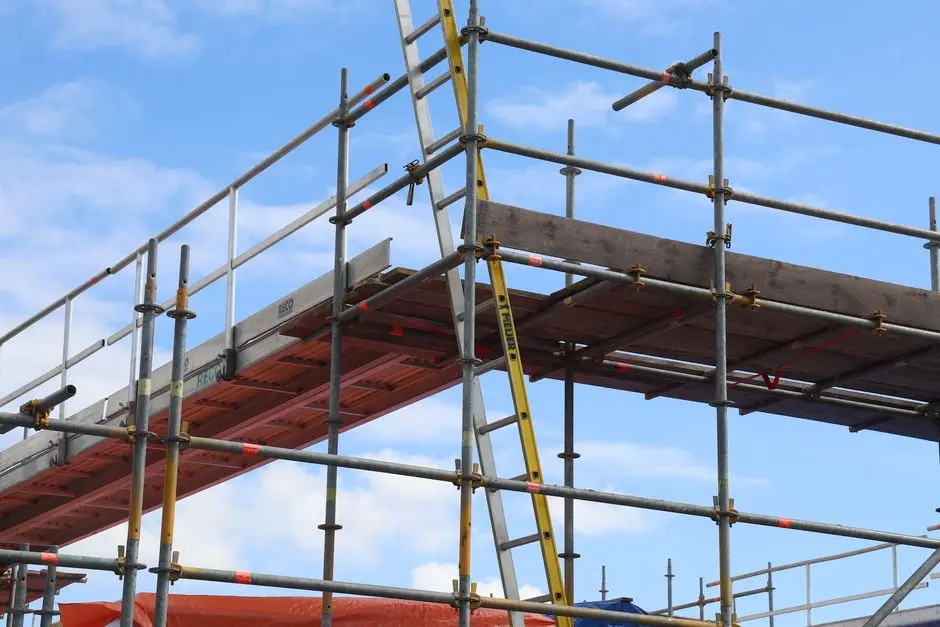
Detailed view of a construction site scaffolding structure and ladder against a bright blue sky.

Understanding Scaffolding Insurance: The Basics

Scaffolding insurance is a type of coverage specifically designed to protect companies in the scaffolding industry. This insurance typically covers a range of risks, including liability, property damage, and worker’s compensation. Understanding the basic components of scaffolding insurance is the first step in selecting the right policy.

At its core, scaffolding insurance aims to mitigate the financial burden of accidents and unforeseen events on construction sites. These environments inherently carry risks, from potential equipment failure to unexpected weather conditions, making it essential for businesses to have a robust insurance plan. When you’re well-versed in the fundamentals of scaffolding insurance, you can better prepare your business for the unpredictable nature of construction work.

Key Components of Scaffolding Insurance Policies

A comprehensive scaffolding insurance policy often includes general liability, equipment coverage, and occupational accident insurance. Each component serves a specific purpose, whether it’s protecting against third-party claims, covering the cost of damaged equipment, or ensuring support for injured workers. Knowing these components helps in tailoring a policy to meet business-specific needs.

Another critical aspect of scaffolding insurance is a well-defined worker’s compensation plan. This is essential for compensating employees who suffer job-related injuries or illnesses. Furthermore, transporting and storing scaffolding components pose additional risks that can be covered under specific policies addressing transportation liability. Businesses must evaluate all potential hazards inherent in their day-to-day operations when selecting the right insurance package.

New Jersey Scaffolding Insurance Requirements

In New Jersey, certain insurance requirements must be met to operate legally in the scaffolding industry. These include minimum coverage limits for liability insurance and compliance with state regulations. Familiarizing yourself with these requirements will ensure your business adheres to local laws while protecting your assets.

New Jersey’s specific regulatory environment mandates that scaffolding businesses adhere to strict safety standards and financial protections. This may include periodic site inspections and maintaining records of compliance. Moreover, understanding how state-specific rules interact with broader federal safety guidelines can be a complex endeavor. Businesses would benefit from consulting specialized legal advisors to keep abreast of any regulatory changes, thereby mitigating the risk of legal issues.

Comparing Insurance Providers and Policies

Shopping for scaffolding insurance involves comparing different providers and their offerings. Look for insurers with a strong track record in the construction industry and positive customer reviews. By weighing factors such as coverage options, premiums, and claim processing times, you can select a provider that aligns well with your business goals.

When comparing insurance providers, another important consideration is the flexibility of policy terms. Opt for providers that offer customizable plans, allowing you to scale your coverage as your business grows. Additionally, efficient claim services can be a deciding factor as time is often of the essence in the construction industry. Providers known for quick and hassle-free claim processes help businesses resume operations swiftly following any disruption.

Expanding Your Coverage Beyond New Jersey

If your scaffolding business operates beyond New Jersey, consider policies that offer flexibility and coverage in multiple states. Different regions may have unique requirements and risks, so ensure your insurance policy addresses these variations to provide seamless protection wherever your projects take you.

For businesses with an eye on expansion, it’s crucial to understand how geographic diversity impacts insurance needs. Different states can present varied environmental risks, legal structures, and labor laws, each of which must be factored into an insurance plan. An adept provider will offer multi-state policies that streamline administrative work and provide comprehensive coverage tailored to each locale’s legal climate. This ensures your operations remain compliant and safeguarded, regardless of where your next project may be.

Choosing the Right Scaffolding Insurance for Your Needs

Understanding and selecting the right scaffolding insurance is crucial to safeguarding your business against potential risks. Whether you’re based in New Jersey or beyond, the key is in finding the coverage that best fits your unique needs. By considering the factors mentioned above, you can confidently navigate the insurance landscape and protect your business effectively.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com


9 Essential Types of Electrician Insurance Every Contractor Should Consider

Navigating the world of insurance can feel overwhelming, especially when it comes to choosing the right coverage for your business. Electricians deal with unique risks, and having the right insurance policy is crucial for protecting your livelihood. In this guide, we’ll break down the essential types of insurance every electrician should consider, helping you make informed decisions with confidence.

Electricians repairing power lines at sunset, showcasing teamwork and safety.

1. General Liability Insurance

General liability insurance is a must-have for electricians. It covers legal fees and damages if your work accidentally causes bodily injury or property damage, offering peace of mind to both you and your clients. By choosing this type of insurance, you’re not only safeguarding your financial stability but also enhancing your professional reputation. Clients appreciate knowing that if something goes wrong, your business is insured and prepared to handle the situation responsibly. This sense of trust can often be a deciding factor when clients choose between you and another contractor who might not carry such comprehensive coverage.

Moreover, general liability insurance is often required by contract when working on certain projects. For example, larger commercial jobs typically mandate proof of this insurance before you can even step foot on the site. This requirement underscores the importance of being ready with the necessary documents, allowing you to focus on what you do best without worrying about legal hitches. It’s a safety net that can’t be overlooked if you want to compete in today’s market.

2. Professional Liability Insurance

Mistakes happen, even in the best-run businesses. Professional liability insurance protects you against claims of negligence or failure to deliver services as promised, ensuring that a simple oversight doesn’t become a financial burden. This type of coverage is particularly important for electricians who offer consultation services or design electrical systems, where an error in planning could lead to significant operational issues for the client.

In such scenarios, even a small miscalculation could result in substantial financial loss, both for your client and potentially for your own business. Professional liability insurance, sometimes known as errors and omissions insurance, covers not only the legal costs associated with defending such claims but also any settlements that might be required. This way, you’re not just protecting your financial interests but also your business’s reputation and client relationships.

3. Workers’ Compensation Insurance

If you have employees, workers’ compensation insurance is typically required by law. It covers medical expenses and lost wages if an employee is injured on the job, helping to maintain a productive and respectful workplace. Beyond legal compliance, it demonstrates a commitment to employee well-being and safety, which can enhance job satisfaction and retention rates.

Moreover, having workers’ compensation insurance can shield your business from costly lawsuits, as employees are generally barred from suing their employer for injuries once workers’ comp is in place. This insurance not only acts as a preventive measure against financial loss due to legal disputes but also fosters a fair and secure working environment. Employees feel assured that they are protected, which contributes to a positive workplace culture, ultimately increasing productivity and morale.

4. Commercial Property Insurance

Protect your tools, equipment, and workspace with commercial property insurance. This insurance covers damages from events like fire, theft, or vandalism, giving you the assurance that you’ll get back on your feet quickly after an unfortunate event. It’s especially crucial for electricians who store expensive tools and materials either at a workshop or on-site.

In the event of a significant loss, such as a fire that destroys your primary tools of trade, commercial property insurance ensures you’ll have the financial support needed to replace everything promptly, reducing downtime and minimizing impact on your business operation. Moreover, some policies also cover loss of income if your business premises are damaged to the extent that you cannot operate temporarily. This added layer of protection is invaluable in keeping your financial health steady during challenging times.

5. Inland Marine Insurance

As an electrician, you frequently transport tools and equipment. Inland marine insurance covers these items in transit, providing protection beyond what a standard commercial property policy includes. This type of insurance is particularly beneficial when covering high-valued items that are critical to your jobs.

6. Business Owner’s Policy

A business owner’s policy bundles general liability and commercial property insurance into one package, often at a lower cost than purchasing each separately. It’s a smart way to get comprehensive coverage and can be tailored to include other types of insurance that suit your specific business needs.

7. Commercial Auto Insurance

If you use vehicles for business, commercial auto insurance is crucial. It covers accidents involving company vehicles, safeguarding your business from potentially costly legal battles and repairs. This type of policy ensures that you can manage vehicle repairs or replacements with minimum financial disruption, allowing you to maintain your business operations.

8. Cyber Liability Insurance

With technology playing a key role in business operations, cyber liability insurance protects against data breaches and cyber attacks. This insurance helps manage the fallout from a cyber incident, protecting both your business and clients. As electricians increasingly use digital management systems to handle contracts, payments, and client communications, the likelihood of cyber threats has risen.

Without coverage, a single data breach could lead to substantial financial losses and damage to your reputation. But with cyber liability insurance, you can cover the costs of notifying affected clients, legal services, and even the business recovery process. This type of insurance is a proactive way to secure your business against the emerging risks of the digital age.

9. Equipment Breakdown Insurance

Equipment breakdown insurance covers repair or replacement costs when essential tools and machinery unexpectedly stop working. It’s an essential safety net that ensures your business operations can continue smoothly, even when the unexpected happens.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com


Is Contractor Liability Insurance Necessary for Small Projects?

When it comes to small projects, many contractors wonder about the necessity of liability insurance. It can seem like an unnecessary expense; however, it’s important to understand what contractor liability insurance covers and whether it’s worth the investment for your specific situation.

Group of construction workers in safety gear collaborating at a city construction site.

Understanding Contractor Liability Insurance

Contractor liability insurance protects your business from claims of property damage, bodily injury, or other accidents that occur during work. It’s designed to cover legal fees, medical payments, and any settlements or judgments that may arise from such claims.

Many contractors mistakenly perceive that insurance is only necessary for large projects. However, even seemingly small mishaps can escalate, leading to significant financial obligations. For instance, if a tool is accidentally dropped and injures a passerby, or if work-related activities inadvertently damage property, contractor liability insurance can provide essential financial protection.

Why Small Projects Aren’t Exempt from Liability

Even small projects can have unexpected complications. Accidents can happen, such as a tool causing damage to a client’s property or a bystander getting injured. These incidents can lead to costly claims that could severely affect a contractor’s finances without proper insurance.

Take into account that small projects, while limited in scope, occur in a variety of environments that may present hazards. An uneven floor, bad weather, or even existing structural problems can increase the risk of incidents. It’s crucial to anticipate potential liabilities and be prepared.

Clients tend to expect a certain level of professionalism and reliability, even for small projects. Proof of contractor liability insurance can enhance a client’s confidence in your services, potentially giving you an edge in a competitive market.

Assessing the Risks Involved in Small Projects

Consider the nature of your project work, the likelihood of accidents, and the potential financial impact of a claim. Project size doesn’t necessarily correlate with risk levels, and it’s vital to weigh these factors before deciding on insurance coverage.

To properly assess risks, analyze each step of your process to identify potential hazards. A straightforward assessment can highlight overlooked danger points, like the potential for slip-and-fall scenarios or tool mishandling.

In the end, a thorough risk assessment can clarify whether the cost of insurance is justifiable compared to the risks your small project involves. While you might get through most projects unscathed, it’s that one-in-a-thousand scenario where insurance provides invaluable protection.

Cost vs. Benefit of Insurance for Small Projects

Although it may seem like an added expense, the cost of contractor liability insurance can be minimal compared to the expenses associated with a lawsuit or claim. Evaluating the cost of insurance versus the potential financial fallout without it is crucial for every contractor.

Additionally, insurance can be viewed as an investment rather than a cost. It secures your reputation, shows potential clients your commitment to safety and professionalism, and can even sometimes lead to lower premiums over time through a no-claims discount.

Incorporating the cost of insurance into your pricing strategy can help mitigate the financial burden. Clients typically understand the necessity of such coverage, especially when framed as a measure ensuring their project’s smooth execution.

Some clients or projects may require proof of contractor liability insurance as part of the agreement. Ensure you understand these legal or contractual obligations to avoid any breaches that might hinder your business.

In addition to protecting your business, holding the right insurance can be a legal prerequisite. Whether for compliance with industry standards or meeting client expectations, staying informed about liability insurance mandates ensures you won’t miss out on potential project opportunities.

Consulting with a knowledgeable insurance provider can help you navigate legal requirements and ensure your coverage meets all necessary obligations.

Conclusion: A Wise Investment for Peace of Mind

While small projects might seem low-risk, contractor liability insurance can be a crucial safeguard against unforeseen incidents. By understanding what it covers and weighing the potential risks, you can make an informed decision that protects your business and provides peace of mind.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com


12 Strategies for Reducing Costs with Cheap Workers Compensation Insurance

Navigating the world of workers compensation insurance can seem daunting, especially when you’re trying to keep costs in check. Fortunately, there are several strategies that can help you manage these expenses without compromising on quality. In this guide, we will explore some practical approaches that make securing affordable workers compensation insurance a reality.

1. Understanding and Assessing Risks

The first step in reducing costs is understanding the specific risks associated with your industry. Conduct a thorough risk assessment to determine the coverage you truly need. This involves analyzing past claims and identifying potential hazards unique to your industry. By doing so, you can tailor your insurance policy to cover only the most relevant risks. Remember, purchasing unnecessary coverage can lead to inflated premiums that burden your business financially.

Once you’ve identified the primary risks, it becomes easier to search for policies that address those specific areas. Insurers appreciate informed clients who know what they want, and this can often lead to better deals. Don’t forget to revisit this assessment periodically as your business grows and evolves, ensuring that your coverage remains aligned with your current needs.

2. Shop Around for Different Quotes

It’s vital to compare quotes from various insurers before making a decision. Different companies assess risk differently, leading to varying quotes. To facilitate this process, consider using online comparison tools that allow you to quickly and effectively contrast the offerings of different insurers. Remember, the most expensive policy isn’t always the best, and the cheapest option may not offer adequate coverage, so finding a balance is key.

3. Utilize Online Tools and Calculators

Make use of online resources to estimate coverage needs and potential costs. These tools can provide a baseline for comparing insurance options. For example, using a workers compensation cost calculator can give you an initial understanding of what to expect when it comes to expenses. Armed with this information, you can have more informed discussions with potential insurers, ensuring you’re not overpaying or underinsured.

4. Implement Safety Training Programs

Enhancing workplace safety can significantly reduce the frequency of claims, often qualifying you for reduced premiums. Consider implementing comprehensive safety training programs that empower employees to work safely and responsibly. These programs not only foster a culture of safety but also demonstrate to insurers your commitment to risk management, potentially leading to even greater savings.

Safety training doesn’t have to be a dry subject. Engaging sessions that are interactive and customized to your workplace’s specific challenges tend to yield the best results. Companies with vibrant safety cultures often see decreases in workplace incidents, and as a result, enjoy lower workers compensation costs.

5. Review and Update Your Policy Regularly

Ensure your coverage aligns with your current business needs and eliminate unnecessary extras to minimize costs. Businesses change, and so do their insurance needs. Regularly reviewing your policy ensures that you’re not paying for coverage you no longer need. Additionally, an annual policy review might uncover new opportunities for discounts that weren’t available the year before due to changes in your business operations or size.

6. Consider Higher Deductibles

Opting for a higher deductible can lower your premiums. Assess whether your business can afford a larger deductible in exchange for reduced annual costs. This strategy requires a careful analysis of your financial capacity to cover higher costs in the event of claims, balanced against the potential savings on premiums. It’s a trade-off between risk and financial predictability. Discussing this option with a financial advisor might provide further clarity.

7. Negotiate with Your Current Provider

Insurers may offer discounts to maintain your business. It never hurts to negotiate terms with your existing provider for better rates. If your record of claims is low and you’ve been a loyal customer, use this as leverage to request a more favorable rate. Additionally, if you’ve received more competitive quotes from other insurers, make your provider aware to see if they can match or beat those prices.

Don’t shy away from asking your provider about any available loyalty discounts or benefits for clients with long-standing contracts. You might find there are previously unmentioned savings that can be unlocked simply by inquiring.

8. Bundle Insurance Policies

Consider bundling your workers compensation insurance with other policies you need. Providers often offer discounts for bundled packages. This could include combining general liability, property insurance, and workers compensation under one umbrella policy. By consolidating these coverages, not only could you save money, but you’ll also simplify your premium payments and claims processing.

9. Use Experience Modification Rate Strategies

Understand how your EMR can impact costs and take measures to lower it, such as improving safety standards to reduce claims. Your Experience Modification Rate (EMR) reflects your historical losses compared to the average losses of other companies in your industry. A lower EMR can lead to lower premium costs, so investing in safety improvements is a prudent financial move.

10. Invest in Ergonomic Office Equipment

Preventing workplace injuries can lead to fewer claims. Investing in ergonomic equipment can enhance worker safety and comfort. Items like adjustable chairs, desks, and keyboard stands might seem like minor expenses, but they can significantly reduce injuries and improve productivity. By prioritizing ergonomic solutions, you foster a healthier work environment, reducing the number of claims related to musculoskeletal injuries.

11. Promote a Return-to-Work Program

Encouraging a solid return-to-work program can help manage and mitigate claim costs, benefiting both employer and employee. Such programs focus on getting injured employees back to work as soon as they’re medically able, often in a modified capacity if necessary. This not only saves costs associated with long-term disability but also boosts morale among employees who feel supported by their employer.

12. Engage an Insurance Broker or Consultant

A professional can offer expert advice tailored to your specific business needs, helping you find the most cost-effective insurance solutions. Brokers possess an in-depth understanding of the insurance landscape and can navigate complex policy options to find the best fit for your company. Their expertise can uncover hidden discounts or untapped cost-saving measures, making their services a valuable investment in securing cheap workers compensation insurance.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com


The $1 Million Mistake Many New York Contractors Make: Are Your 1099 Workers Really Covered Under Your General Liability Policy?

For many New York contractors, using 1099 workers has become a common way to meet labor demands while maintaining flexibility. Unfortunately, many contractors assume that simply issuing a worker a Form 1099 automatically makes that individual an independent contractor for insurance purposes. That assumption can be extremely costly.

One of the biggest misconceptions in the construction industry is that tax classification determines insurance coverage. In reality, your Commercial General Liability (CGL) insurance policy may view these workers very differently than the IRS or your accountant does.

Understanding how your insurance company classifies 1099 workers—and how your policy’s subcontractor warranty or “Hard Hammer” endorsement applies—could mean the difference between having a claim paid or having coverage denied.

Does a 1099 Automatically Make Someone an Independent Contractor?

The answer is no.

A Form 1099 is simply a tax reporting document. It does not determine whether someone is considered an employee or an independent contractor under your Commercial General Liability policy.

When evaluating a claim, insurance companies often look at the actual working relationship between the contractor and the worker. Factors may include:

  • Who controls how the work is performed.
  • Who supplies the tools and equipment.
  • Whether the worker performs services exclusively for one contractor.
  • Whether the worker has their own business.
  • Whether the worker carries their own insurance.
  • Whether the worker hires and supervises their own employees.

Depending on these facts, a carrier may determine that a 1099 worker is actually functioning as your employee or, alternatively, as an uninsured subcontractor.

Why This Matters

Many contractors purchase insurance without fully understanding the endorsements attached to their policy.

One endorsement that has become increasingly common in the New York construction market is the Hard Hammer Subcontractor Warranty.

While the wording varies among insurance companies, these endorsements generally require that every subcontractor satisfy specific insurance requirements before beginning work.

If those requirements are not met, the insurance company may significantly reduce or completely eliminate coverage for claims arising out of that subcontractor’s work.

Article content

What Is a Hard Hammer Subcontractor Warranty?

A Hard Hammer endorsement is designed to transfer risk from the insurance company back to the insured contractor.

To comply with many of these endorsements, contractors are typically required to obtain documentation from every subcontractor before work begins.

Common requirements include:

  • A signed written subcontract or hold harmless agreement executed before work starts.
  • Proof that your company has been added as an Additional Insured.
  • Additional Insured status provided on a Primary and Non-Contributory basis.
  • A Waiver of Subrogation in your favor.
  • Commercial General Liability limits of at least $1,000,000 per occurrence (or higher if required).
  • Active Workers’ Compensation insurance.
  • Certificates of Insurance verifying the required coverages.

If even one of these requirements is missing, your policy’s Hard Hammer endorsement may be triggered.

What Happens if Your 1099 Worker Is Considered an Independent Contractor?

This is where many contractors encounter serious problems.

Suppose you hire a 1099 worker to perform framing work on one of your projects.

You never execute a written subcontract.

You never obtain a certificate of insurance.

You never require Additional Insured status.

There is no Primary and Non-Contributory wording.

No Waiver of Subrogation is obtained.

The worker has no Workers’ Compensation policy.

Several months later, property damage or bodily injury occurs arising out of that worker’s operations.

If your insurance carrier determines that the individual was actually an independent contractor rather than your employee, they may conclude that your Hard Hammer endorsement has not been satisfied.

Depending upon the wording of your policy, this could result in:

  • Reduced coverage.
  • Higher deductibles or self-insured retention.
  • Limited defense obligations.
  • Denial of indemnity.
  • Complete denial of coverage for the claim.

Every policy is different, and coverage depends on the specific policy language, endorsements, facts of the claim, and applicable law. However, contractors should never assume that using a 1099 worker automatically satisfies their insurance requirements.

The Hidden Risk

Many contractors spend thousands of dollars purchasing liability insurance but unknowingly create coverage gaps by failing to properly document their subcontractors.

During audits or after a serious claim, insurance companies frequently request:

  • Written contracts.
  • Certificates of Insurance.
  • Additional Insured endorsements.
  • Hold Harmless Agreements.
  • Workers’ Compensation documentation.

If these records cannot be produced, questions may arise regarding whether the subcontractor warranty has been satisfied.

Waiting until after a claim occurs is far too late.

Best Practices for New York Contractors

Whether you hire one subcontractor or one hundred, every contractor should establish procedures before anyone begins work.

Consider implementing the following practices:

  • Require written contracts before work starts.
  • Obtain certificates of insurance before workers arrive on the job.
  • Verify that Additional Insured endorsements have actually been issued—not merely promised.
  • Confirm Primary and Non-Contributory wording.
  • Obtain Waivers of Subrogation where required.
  • Verify active Workers’ Compensation coverage.
  • Review liability limits to ensure they meet your contractual requirements.
  • Keep organized electronic records for every subcontractor.

These simple administrative steps can help protect your company if a claim arises.

Don’t Assume—Know What Your Policy Requires

Every Commercial General Liability policy is different.

Some policies contain soft subcontractor warranties while others contain much stricter Hard Hammer endorsements. The exact wording of the endorsement can dramatically affect how coverage is applied following a claim.

Because of this, contractors should have their policies reviewed by an insurance professional who understands New York construction risks and can identify potentially dangerous endorsements before a loss occurs.

Spending a few minutes reviewing your policy today may save your business hundreds of thousands—or even millions—of dollars in uncovered claims tomorrow.

About BGES Group

At BGES Group, we specialize in insurance solutions for New York contractors. With more than 45 years of insurance experience, we understand the unique risks facing the construction industry, including subcontractor compliance, Commercial General Liability, Workers’ Compensation, Builders Risk, Umbrella Liability, Commercial Auto, and contractor-specific insurance requirements.

Our goal is not simply to sell an insurance policy—we help contractors understand what their policies actually cover and identify potentially dangerous exclusions and endorsements before they become expensive problems.

If you’re unsure whether your current policy contains a Hard Hammer subcontractor endorsement, or you’d like a second opinion on your insurance program, we’d be happy to review it with you.

Gary WallachBGES Group

Phone: 914-806-5853

Email: bgesgroup@gmail.com

Website: www.bgesgroup.com

Disclaimer: This article is for general informational purposes only and is not legal or insurance coverage advice. Insurance coverage depends on the specific policy language, endorsements, facts of each claim, and applicable law. Contractors should consult with their insurance professional and legal counsel regarding their specific circumstances.

Understanding Window Installation Insurance for Contractors in New York

Navigating the world of insurance can be overwhelming, especially for window installation contractors working in New York. Ensuring you have the right coverage can safeguard your business against unforeseen events. In this blog, we’ll break down what window installation insurance entails, why it’s crucial, and how you can obtain it as a New York contractor.

A modern green house under construction with blue skies and workers outside.

Why Window Installation Insurance is Essential

Window installation can be fraught with risks, from accidental damage to client property to worker injuries on site. Insurance provides financial protection and peace of mind, ensuring that any mishaps don’t turn into crippling expenses for your business. In the bustling environment of New York, where construction and renovations are ongoing, having window installation insurance is not just a recommendation but a necessity. It covers a broad spectrum of potential issues, such as damage to expensive glass panels during transportation or installation. Moreover, insurance supports your business by mitigating liabilities associated with structural mishaps that may occur during a project. Such protection is crucial, as the costs arising from these incidents can be substantial, sometimes even threatening the viability of your contracting business.

Another compelling reason to secure window installation insurance is the trust it builds with your clients. Homeowners and businesses alike prefer to work with contractors who are fully insured, seeing it as a mark of professionalism and responsibility. When clients know that you’re covered, it instills confidence and can even be a pivotal factor in choosing your services over those of an uninsured competitor. This trust can lead to positive word-of-mouth referrals, further enhancing your reputation in the industry.

Types of Coverage to Consider

Different types of insurance cover different risks. General liability, workers’ compensation, and professional liability insurance are among the most important for window installation contractors. Each of these plays a unique role in shielding your business from specific liabilities. For instance, general liability insurance covers incidents like accidental property damage or bodily injuries to third parties caused during your work. This is particularly crucial for contractors who work on high-rise buildings or urban sites, where the risk of accidents is higher.

Workers’ compensation insurance is mandated in almost all states, including New York, offering protection to both you and your employees. It covers medical expenses and lost wages for workers who are injured on the job, thus providing crucial financial support and peace of mind to your workforce. This type of insurance is not only a legal requirement but also a moral obligation for responsible business owners, showing that you care about the well-being of your team.

Professional liability insurance, also known as errors and omissions insurance, protects against claims of negligence or failing to perform professional services adequately. This includes cases where advice or guidance provided by your team led to financial loss or physical damage. Having this coverage can be a deciding factor in managing risks associated with larger scale, complex projects where project specifications and requirements might change frequently.

New York state has specific legal requirements when it comes to insurance for contractors. Understanding these requirements not only keeps your business compliant but also protects you from hefty fines or legal issues down the road. The state mandates that all businesses with employees must carry workers’ compensation, disability insurance, and in many cases, general liability insurance. As a contractor, failing to meet these obligations can lead to costly penalties and even jeopardize your ability to operate.

To effectively navigate these requirements, it’s beneficial to consult with an insurance broker who specializes in contractor insurance in New York. They can help ensure that your insurance policy is not only compliant but also aligns with the specific risks associated with your field. Additionally, staying informed about any changes in state laws or regulations is essential, as these could impact your insurance coverage requirements. Partnering with a knowledgeable broker can provide you with ongoing guidance, ensuring your business remains protected at all times.

Tips for Choosing the Right Insurance Provider

Selecting the right insurance provider can make all the difference. Look for insurers who specialize in contractor insurance and understand the unique challenges of working in New York. Comparing rates and coverage options can help you make an informed decision. Speak to other contractors about their experiences with insurance providers to gain insights into the quality of service and support offered.

When choosing an insurance provider, consider their financial stability and customer service reputation. An insurer with a strong financial footing is more likely to be able to pay out claims promptly and handle large claims effectively. Similarly, a company with a reputation for excellent customer service can make the process of managing claims and adjusting coverage less stressful during difficult times. Look for providers who offer customizable policies, allowing you to tailor the coverage specifically to your business needs. This flexibility can prove invaluable as your contracting business grows and evolves over time, ensuring continued protection against new and emerging risks.

Securing Your Business with the Right Insurance

In summary, having comprehensive window installation insurance is a vital part of running a successful contracting business in New York. It protects both your company and your clients, fostering trust and allowing you to focus on delivering quality work. By understanding the types of coverage available and complying with state requirements, you can ensure your business is well-protected.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com


Why Is Choosing the Best Contractor Insurance Essential for Your Business?

In the ever-evolving world of contracting, ensuring that your business is protected with the right insurance coverage is a critical consideration. Contractor insurance not only safeguards your financial well-being but also enhances your credibility in the industry. Let’s delve into why choosing the best contractor insurance is essential for your business.

Two engineers in hardhats discuss projects at a busy construction site.

Understanding Contractor Insurance Basics

Contractor insurance is designed to protect contractors against potential liabilities and claims that may arise during their work. It includes coverage types like general liability, worker’s compensation, and commercial auto insurance.

At its core, contractor insurance acts as a safety net. Imagine working on a construction site; accidents can happen at any time, whether it’s damage to a client’s property or an injury to one of your employees. That’s where general liability comes into play. This type of coverage protects you from claims related to third-party injuries and property damage. Additionally, worker’s compensation is vital to cover medical expenses and wage loss for employees injured on the job.

Commercial auto insurance is another essential component, especially if you have vehicles that are fundamental to your contracting business. It covers the costs of accidents involving company vehicles, which could otherwise be a massive financial burden. The importance of these coverage types cannot be overstated, as they form the foundation for protecting your financial assets and supporting your operation’s continuity.

Why Your Business Needs the Best Coverage

The best insurance coverage ensures that your business is protected against the unique risks it faces, from on-site accidents to property damage or even litigation. Having comprehensive insurance enhances your business’s reputation and credibility with clients.

Selecting the best insurance is not just about ticking off a requirement; it’s about securing your brand’s integrity and trustworthiness. Clients tend to choose contractors who can assure them of minimized liability. By maintaining well-rounded insurance, you are demonstrating a responsible business ethos, which can lead to stronger client relationships and more opportunities for high-value projects.

Moreover, the competitive edge received from having robust insurance cannot be overlooked. Striking a partnership with clients can be much smoother when they know your business is fully insured. This assurance can often be the deciding factor between you and another contractor who may not have the necessary protection.

Identifying Essential Insurance Components

Evaluate the essential components that should be part of your contractor insurance policy, such as general liability, professional liability, and equipment coverage. Understanding these components helps you tailor the coverage to match your business needs.

General liability insurance covers a broad array of potential risks, but tailoring your insurance policy to include professional liability offers coverage for errors and omissions in your service. This becomes crucial if your expertise or advice leads to financial harm to a client. It’s also important to consider tools and equipment coverage, especially if your business depends heavily on specialty equipment. This ensures that in the event of damage or theft, your project timelines won’t be derailed.

By understanding common risks contractors face, you can better align your insurance policy with the needs of your business. It’s essential to regularly review these components to ensure all potential vulnerabilities are mitigated with the appropriate coverage.

Evaluating Insurance Providers

Choosing a reliable insurance provider is crucial. Look for factors like reputation, customer service, coverage options, and financial stability. Reading reviews and asking for recommendations can help in making an informed choice.

Don’t underestimate the value of a thorough background check on potential insurance providers. A provider’s reputation can indicate the quality of service you will receive. Additionally, customer service must be a priority, as you may need prompt assistance and support when dealing with claims. Always prioritize a provider who values transparency and clear communication.

It’s also prudent to look at the provider’s financial stability, as this impacts their ability to pay out claims. Utilize resources like AM Best and Moody’s ratings to get an overview of their financial health. This comprehensive approach to selecting a provider ensures your trust is well-placed and that your business remains protected.

Regularly Reviewing Your Coverage

Regular evaluation of your insurance coverage helps ensure it remains adequate as your business grows and evolves. Adjusting your policy as necessary safeguards your business against new risks and changes in the industry.

In the bustling world of contracting, changes are constant. Whether you’re expanding your service offerings or moving into a new market, these shifts necessitate an updated insurance review. A review might reveal the need for additional coverage, ensuring you aren’t exposed to emerging risks or industry-specific liabilities.

Staying proactive about your insurance needs is part of good business practice. It reflects an understanding of the dynamic nature of the contracting industry and ensures you remain one step ahead in your risk management strategies. To gain more insight into maintaining optimal coverage, you might consider exploring resources that delve into key factors affecting insurance needs.

Protect Your Business with the Right Contractor Insurance

Choosing the right contractor insurance is a crucial investment for the longevity and success of your business. With the right coverage, you not only protect your assets but also gain peace of mind knowing that your business is safeguarded against unforeseen events. Evaluate your options carefully and select an insurance policy that aligns with your business needs and goals. Discover more about how we can assist you in finding the perfect insurance coverage by visiting BGES Group.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com


How Does Builders Risk Insurance Protect My Construction Project?

Embarking on a construction project is an exciting yet challenging endeavor. With so many moving parts, risks abound at every stage, from the initial groundbreaking to the final touches. That’s where builders risk insurance comes into play, offering protection and peace of mind. In this FAQ, we’ll break down how this specialized insurance coverage can safeguard your construction project.

What is Builders Risk Insurance?

Builders risk insurance is a specialized form of property insurance designed to protect construction projects. It covers buildings and structures under construction, safeguarding against risks like fire, theft, and natural disasters.

Imagine you’re in the midst of constructing a new office building or renovating an existing property. During this dynamic period, any number of unexpected occurrences could potentially impact the progress and finances of your project. Builders risk insurance acts as a protective shield, offering coverage against unforeseen incidents that might otherwise derail your endeavor.

This insurance is essential for property owners, contractors, and even sub-contractors, as it not only protects the physical aspect of the construction but also provides a sense of security against various uncertainties that loom over every project.

Key Coverage Areas of Builders Risk Insurance

This insurance covers physical loss or damage to a property due to unforeseen events. It typically includes coverage for materials, equipment, and structures related to the project during the construction phase.

Comprehensive in nature, builders risk insurance offers coverage not just for new builds but also for renovations and remodels. It’s crucial to note that this insurance applies from the start of a project until its completion, ensuring all phases are protected.

Beyond the basics, some policies might cover expenses related to debris removal after a covered loss, thus sparing additional costs that can arise unexpectedly. However, every policy is unique, so it’s essential to choose one that fits the needs of your specific project.

What Risks Are Typically Covered?

Builders risk insurance generally covers perils such as fire, lightning, vandalism, and certain weather-related events. It may also be extended to include theft and accidents leading to the destruction of materials.

These commonly covered risks ensure that incidents such as a storm damaging your new roofing materials or a fire breaking out on-site don’t completely halt or financially ruin your project.

The scope of coverage could also include damages related to construction errors, although this is typically addressed separately. It’s important to tailor your policy carefully based on the potential risks your project may encounter.

What Isn’t Covered by Builders Risk Insurance?

While comprehensive, builders risk insurance doesn’t cover everything. Typical exclusions might include normal wear and tear, employee theft, or certain natural disasters unless specified. It’s essential to understand these exclusions when choosing a policy.

Understanding what isn’t covered by builders risk insurance can prevent misconceptions. For instance, defects in workmanship or lousy design aren’t typically covered, which means remedial actions fall under the purview of other insurance types like professional liability insurance.

How to Choose the Right Policy for Your Project

Selecting the right policy involves assessing the specific needs and risks of your project. Consider the location, scale, type of construction, and project timeline, and consult with an insurance advisor to tailor the coverage effectively.

It’s wise to collaborate closely with a qualified insurance professional who can guide you in understanding the nuances of builders risk insurance. They can provide insights into policy comparisons and help you forecast potential risks you might not have considered.

Ultimately, choosing a policy should offer a balance between comprehensive coverage and affordability, ensuring that your investment in the project is well-protected throughout its duration.

Securing Your Project with Builders Risk Insurance

Builders risk insurance acts as a safety net for your construction project, covering it against various unpredictable and potentially costly risks. By understanding and investing in this type of insurance, you ensure that your project stays on track even when the unexpected occurs, providing reassurance and stability in a complex industry. For more information, visit our homepage.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com


The Importance of New York Contractors Insurance: What You Need to Know

Navigating the busy world of contracting in New York comes with its own set of challenges and responsibilities. One crucial aspect that every contractor should prioritize is securing appropriate insurance. This blog will delve into why having contractors insurance in New York is vital and cover key points that every contractor should know.

Two construction workers wearing helmets at a site in India with a crane and building.

Understanding Contractor Insurance Basics

Contractor insurance is designed to protect businesses from the risks associated with contracting work. It usually includes general liability, property insurance, and worker’s compensation. Each policy is tailored to the specific needs of your business, providing the necessary coverage for the unique challenges faced in the contracting industry.

At the core of every successful contracting business lies a comprehensive understanding of insurance basics. In essence, contractor insurance acts as a protective shield for your business. Often, this includes coverage for liability, property assets, and individuals on your team through worker’s compensation. By tailoring each aspect of insurance to fit your business, you can adequately address the distinctive challenges found within this industry. For instance, general liability insurance covers property damage or bodily injury claims made against your company, which can be especially beneficial when working on large projects in dense urban areas like New York City.

Consider property insurance as another layer of protection that guards against damage to the physical assets of your business. Whether it’s the tools of your trade or the premises from which your team operates, safeguarding these assets ensures your operations run smoothly, even when accidents occur. On the other hand, worker’s compensation insurance is essential for protecting your greatest resources – your team. It provides benefits to employees who suffer work-related injuries, thus maintaining morale and legal compliance. Given the complexity of projects and the high expectations for quality and safety, understanding the nuances of contractor insurance is a valuable first step in fortifying your business’s foundation.

Why It’s Essential for New York Contractors

New York’s contracting landscape is dynamic and competitive, making insurance a critical tool for risk management. Insurance not only shields your business from potential financial losses due to accidents and damages but also assures clients of your professionalism and reliability.

For contractors operating in New York, where the construction scene is as bustling as the city itself, having a solid insurance policy is not just an option, it’s a necessity. From the high-rises in Manhattan to the suburban developments in the outer boroughs, each project comes with its own set of risks and challenges. In this environment, risk management strategies play a pivotal role. Insurance provides a safety net against financial threats resulting from job site injuries, property damage, or other unforeseen circumstances. Not to mention, a proven track record of insured projects speaks volumes to potential clients about your commitment to professionalism and reliability.

Another compelling reason to prioritize contractor insurance in New York is the added advantage of enhancing your competitive edge. Insurance coverage often factor into the decision-making process for clients who weigh their options between multiple contractors. It’s not just about showing you can complete a project but demonstrating your capability to handle incidents effectively. This assurance adds a layer of confidence for clients, knowing they’ve entrusted their projects to a well-prepared contractor.

In New York, contractors must adhere to specific insurance regulations. Failure to comply can lead to severe penalties, including fines and loss of business licenses. Understanding these legalities ensures your operations are above board and minimizes the risk of legal disputes.

Adhering to New York State insurance regulations is not merely part of the bureaucratic process; it’s crucial for the integrity and sustainability of your contracting business. The state has clearly outlined insurance requirements tailored to protect all parties involved, including contractors, workers, and property owners. These legal mandates ensure a baseline of safety and accountability. For example, all contractors must carry worker’s compensation and disability benefits insurance to cover employees in case of work-related injuries. Non-compliance could result in hefty fines or even the loss of your contractor’s license, which would be devastating for any business reliant on project continuity.

Beyond statutory obligations, maintaining proper insurance also serves as a proactive measure against potential legal disputes. Given the litigious nature of construction and contracting in densely populated regions such as New York City, having insurance can be a significant line of defense against lawsuits that may arise from on-site accidents. It’s essential for contractors to remain vigilant and informed about their required insurance obligations to sustain legal and operational credibility.

Types of Coverage Available

Besides the standard general liability and worker’s compensation, other types of coverage are available, such as professional liability, builder’s risk, and equipment insurance. Selecting the right mix depends on your business model and the specific projects your firm undertakes.

In the diverse world of contracting, determining the right insurance mix requires understanding the specific types of risks associated with your projects. Beyond general liability, which covers third-party bodily injuries and property damage, other specialized coverages can add layers of protection. For instance, professional liability insurance is crucial for contractors involved in design or consulting roles, offering coverage against claims of negligence or found errors. Additionally, builder’s risk insurance can be a valuable policy, providing protection against damage to buildings under construction due to events like fire or severe weather.

Tools and equipment insurance is another vital coverage for contractors. This policy covers the tools of the trade, which are often significant investments. Given the high value and necessity of construction equipment, having this insurance can prevent substantial replacement costs in case of theft or damage. Identifying specific project needs and potential risks allows contractors to tailor their insurance coverage, ensuring comprehensive protection aligned with business goals and client expectations.

Choosing the Right Insurance Provider

Not all insurance providers are created equal. Look for providers with a strong track record, excellent customer service, and clear policy terms. Consider working with agents who specialize in contractor insurance to help you navigate your options and find the best fit for your needs.

Finding the right insurance provider is pivotal to securing effective coverage tailored to your business needs. The marketplace is flooded with options, but not all providers offer the same level of service and reliability. When selecting a provider, consider their reputation in the industry, particularly regarding customer service and claims processing. Providers with a strong track record and positive customer reviews are typically more reliable partners in times of need. Opt for a provider whose terms are transparent and easy to understand, ensuring you’re fully aware of what your policy covers and excludes.

Engaging an insurance agent who specializes in contractor insurance can be invaluable. These professionals bring a wealth of knowledge about industry-specific risks and can offer customized recommendations that reflect your unique business requirements. They assist in demystifying complex insurance jargon, allowing you to make informed decisions that align with your company’s future objectives. By partnering with the right provider, contractors can not only meet legal requirements but also strategically position their business for success amidst competitive pressures.

A Secure Foundation for Success

Securing the right insurance is more than just a legal necessity; it is a foundational element of a successful contracting business in New York. Understanding the importance, knowing the types of coverage available, and being aware of the legal ramifications can safeguard your business from unforeseen setbacks. Investing in robust insurance not only offers peace of mind but also builds trust with clients and offers long-term stability.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com


What Should I Consider When Exploring Contractor Liability Insurance Near Me?

Navigating the world of contractor liability insurance can feel overwhelming, especially when you’re looking for the right coverage close to your location. Understanding what to consider is essential for making an informed decision. Let’s break down the key points to help you find the best contractor liability insurance near you.

Understand Your Coverage Needs

Before diving into options, assess what specific coverage your contracting business requires. Consider factors like the size of your projects, your team, and the types of risks you usually encounter. Evaluating your business operations thoroughly will help in identifying the necessary coverage areas. For instance, does your work often involve dangerous equipment or locations? This could influence the level of protection you’ll need.

An essential step in this process is considering potential future developments. As your business grows, its risk exposure might change, necessitating adjustments in your coverage. Tailoring your policy to your business’s evolving circumstances not only provides peace of mind but also ensures that you’re prepared for unexpected situations.

Evaluate Different Types of Coverage

Learn about the various types of liability insurance available, such as general liability, professional liability, and workers’ compensation, to determine which suits your business best. Each type covers different scenarios. For example, general liability insurance typically protects against third-party bodily injury or property damage, whereas professional liability insurance is more focused on errors or negligence in services rendered.

Don’t overlook specialized coverages like equipment insurance if your business relies heavily on machinery. This can be particularly vital if your operations are equipment-intensive. Additionally, excess liability insurance might be worth exploring if you’re aiming for extra protection beyond the standard limits.

Understanding the differences can help you select options that reflect your business’s risk profile and operational particularities. Remember, coverage isn’t just about meeting minimum requirements; it’s about genuinely safeguarding your enterprise against financial setbacks.

Research Local Laws and Regulations

Each location has its own set of laws governing contractor insurance. Familiarize yourself with these regulations to ensure compliance and avoid any legal issues. State and local governments often have specific mandates that dictate minimum coverage levels, types of insurance required, and other guidelines contractors must follow.

Understanding local laws not only helps in compliance but can also guide you in structuring your policies more effectively. Resources like the National Association of Insurance Commissioners (NAIC) offer valuable information that can assist you in grasping what your region requires.

Keep in mind that adhering to these regulations is not just about avoiding fines or penalties; it’s also about ensuring the trust and confidence of your clients. Demonstrating that you’re compliant with all legal requirements enhances your credibility as a responsible business entity.

Consider the Insurer’s Reputation

A reputable insurer is crucial. Look for reviews, ratings, and testimonials of insurance companies near you to gauge their reliability and customer service. Platforms like the Better Business Bureau can provide insights into the experiences of past and current policyholders, helping you make an informed decision.

An insurer with a solid track record is more likely to handle claims efficiently, offer fair pricing, and provide comprehensive customer support. Moreover, checking their financial stability can indicate their ability to pay out claims in the future. Research tools such as A.M. Best can be instrumental in assessing the financial strength of an insurer.

Customer service is another critical aspect to consider. An insurer’s ability to promptly address concerns or questions can make or break the insurance experience. Engaging with peers or industry forums online might give you additional perspectives on which companies prioritize quality service.

Compare Quotes and Policies

Collect quotes from different insurers. Compare not just the price, but also what each policy entails in terms of coverage limits, exclusions, and additional benefits. Tools like online insurance comparison sites can simplify this process, highlighting exactly where each policy stands in relation to another.

While price is important, the cheapest option may not always be the best. Sometimes a policy with a slightly higher premium might provide better protection or additional perks, adding up to long-term savings should you ever need to file a claim.

Additionally, consider any bundles or discounts an insurer might offer for multiple coverages. This can be a cost-effective way to expand your protection while keeping an eye on your budget. Clarify any potential hidden fees or clauses that could impact your decision-making process.

Making an Informed Decision About Contractor Liability Insurance

Choosing the right contractor liability insurance near you involves understanding your specific needs, the coverage types available, the intricacies of local laws, and the reputation of potential insurers. With these considerations, you can make a confident and informed choice that protects your business effectively.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com