What Factors Affect the Cost of Workers Comp Insurance?

Workers compensation insurance is a crucial safety net for both employers and employees. Understanding what factors influence the cost of this insurance can help businesses manage expenses while ensuring adequate coverage. In this blog, we’ll explore the primary factors that can affect the cost of workers comp insurance, in easy-to-understand language and a friendly tone.
A construction worker onsite in a city wearing safety gear and examining scaffolding.

Industry and Type of Business

The nature of your business significantly affects the cost of workers comp insurance. High-risk industries like construction or manufacturing tend to have higher premiums compared to low-risk fields such as accounting or clerical work.

For instance, in construction, workers face potential hazards on a daily basis. The heavier equipment and more involved manual labor increase the chances of accidents. This risk is why businesses in such sectors typically see higher insurance costs. Comparatively, a business consulting firm might pay less, as their typical work environment poses fewer physical dangers to employees.

It’s vital for businesses to understand their industry risks and how they influence insurance costs. Companies can take proactive measures to mitigate these risks, potentially lowering their premiums. Implementing thorough safety protocols and regular training can also positively impact costs.

Company Size and Payroll

The size of your company and the total payroll impact your insurance costs. Generally, larger payrolls result in higher premiums because there’s a greater potential for claims.

Payroll directly correlates with the number of employees covered under the policy. A larger workforce implies a higher likelihood of claims, thus increasing premiums. However, some insurers may offer discounts for larger businesses that implement effective safety programs.

Small businesses, conversely, might experience lower overall costs due to fewer employees, but they don’t necessarily escape high premiums entirely. The risk exposure per employee can still result in significant insurance costs, especially if the business operates within a high-risk industry.

Claims History

A company’s past claims history is a major factor in determining insurance rates. Frequent or severe past claims can increase premiums, while a clean claims record might help secure lower rates.

Insurers consider a company’s claims history as a predictor of future claims. As such, a history replete with numerous claims suggests a higher likelihood of future incidents, driving premiums up. On the other hand, businesses with a track record of fewer or no claims may be perceived as lower risk.

A clean claims history can sometimes lead to discounts on premiums. It demonstrates to insurers that the business takes employee safety seriously. Businesses are encouraged to maintain comprehensive records of incidents and regularly review safety procedures to support low-claims records.

State Requirements

Each state in the U.S. has different requirements and regulations concerning workers comp insurance. These can affect both the coverage needed and the premium costs.

State-specific regulations determine the minimum coverage requirements for businesses, impacting overall costs. Some states mandate certain additional coverages, contributing to potentially higher premiums. It’s imperative for companies to understand their state’s specific requirements to ensure compliance and avoid legal penalties.

Additionally, state-assigned risk classifications may vary, affecting how individual businesses are assessed. Since these classifications play a part in determining premium rates, differences between states can lead to variance in cost for similar business types. At BGES Group, we encourage clients to stay informed about state-specific regulations to optimize their coverage strategy.

Making Informed Decisions About Workers Comp Insurance

Navigating the complexities of workers comp insurance can seem daunting, but by understanding these key factors, businesses can make informed decisions that balance cost and protection. Remember, it’s not just about finding the cheapest rate—it’s about ensuring comprehensive coverage for your workforce.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com


8 Critical Steps to Enhance Risk Assessment for Contractors in the Tri-State Area

Working as a contractor in the Tri-State Area comes with its unique challenges, especially when it comes to managing risk. Getting a handle on risk assessment is crucial for the safety and success of your projects. In this blog, we’ll walk you through some essential steps to make sure you’re fully prepared.

1. Recognizing Potential Hazards

The first step in risk assessment is to identify potential hazards that can affect your project. Understanding what could go wrong allows you to address problems before they arise. In the dynamic world of construction, hazards can come in many forms—from physical dangers like falls and equipment failures to environmental concerns such as chemical spills or noise pollution. Conducting a thorough analysis of past incidents and near-misses in similar projects can offer valuable insights into which areas require your attention. Additionally, engaging with experienced team members during brainstorming sessions can unearth less obvious risks. This collaborative approach not only diversifies the potential hazards identified but also fosters a culture of safety awareness among your workforce.

Another crucial aspect involves keeping abreast of changes in regulations and guidelines, which can pose new compliance risks. Staying updated can aid in adjusting your risk management policies accordingly. Engaging in certification courses or workshops tailored to the construction industry is a proactive step to stay informed. Recognizing hazards isn’t just about identifying what might go wrong—it’s about understanding the full scope of how these hazards could impact not only the project but also the safety of every individual involved. By taking these steps, you set the foundational stage for all subsequent risk management efforts.

2. Understanding the Difference Between General Liability and Labor Law Coverage

A critical aspect of risk assessment is knowing the type of insurance coverage required. Learning the nuances between general liability and labor law coverage can save you from potential legal and financial issues. General liability insurance typically offers coverage for accidents on the job site as well as injuries to non-employees, whereas labor law coverage focuses more on legal protections for workers who are injured on the job. These distinctions might seem minor, but they are monumental when it comes to claims and financial responsibilities. Contractors should have both coverages in place to protect against a wide variety of eventualities.

For contractors in the Tri-State Area, where labor laws can be particularly stringent, understanding the intricacies of coverage types is essential. At a glance, general liability might seem all-encompassing, but it often leaves crucial gaps that specific labor law coverage addresses. Failing to recognize these nuances can lead to substantial out-of-pocket expenses and potential legal ramifications. Be sure to consult with an insurance expert who can tailor coverage to the unique needs of your projects. Taking the time to understand your coverage can elevate your risk management strategies from rudimentary to robust.

3. Evaluating Environmental Impacts

An often overlooked part of risk assessment is evaluating the environmental impacts of your work. Considering these aspects not only prevents regulatory fines but also promotes sustainability. As construction operations are known to significantly impact the environment, every contractor should make it a priority to conduct an environmental assessment before starting any project. This includes evaluating air quality, managing waste disposal, and assessing the impact on local wildlife. Ensuring compliance with local and federal environmental regulations can minimize hazardous effects and mitigate the financial and reputational costs that come with non-compliance. In addition to regulatory compliance, adopting environmentally conscious practices can serve as a positive differentiator for your business, attracting clients who prioritize sustainability.

Furthermore, with rising issues of climate change, integrating green building practices into your projects not only aids in risk management but also aligns your business with global sustainability goals. Techniques like using eco-friendly materials, ensuring energy efficiency, and minimizing water consumption are notable examples. These practices not only enhance your company’s reputation but also lead to tangible financial benefits such as tax rebates and reduced operational costs. As we collectively move toward more sustainable futures, being an early adopter places your company at the forefront of a significant industry shift. Embracing these environmental considerations enriches your risk management strategies and sets you apart as a leader in responsible construction.

4. Conducting Thorough Site Inspections

Regular and thorough site inspections help in identifying potential safety issues early on. This proactive approach allows for immediate action, reducing risk considerably. Conducting inspections involves looking beyond the obvious—scrutinizing equipment conditions, verifying structural soundness, and ensuring safety protocols are being strictly followed. Engaging specialized personnel, such as safety officers, during inspections ensures that even the most overlooked areas receive attention. Modern tools and technologies can streamline the inspection process, enabling real-time updates and ensuring detailed reporting. Mobile apps, in particular, have transformed site inspection efficiency by allowing quick documentation and easing communication between teams.

Moreover, integrating technology can enhance transparency and accountability. Implementing drone technology for aerial inspections adds another layer of comprehensiveness, especially in areas that are hard to access or potentially unsafe for human inspectors. Imagine quickly gathering high-definition photos and videos of vast construction areas, pinpointing issues that need immediate attention. This forward-thinking approach not only ensures a higher level of safety but also saves time and money by reducing the risk of site shutdowns due to unforeseen hazards. Embracing a combination of traditional and modern methods keeps your inspections thorough and your projects secure.

5. Engaging in Continuous Training

Ensuring that your team is well-trained in safety practices is critical. Regular training sessions help maintain a safety-focused work culture and prepare employees for emergency situations. For many, the challenge lies in making training sessions engaging and effective over time. One approach is to diversify training methods—using a blend of hands-on workshops, online modules, and peer-led safety drills can keep staff engaged. By simulating real-world scenarios, your team can tackle potential risks in a controlled environment, which not only embeds safety protocols more deeply but also boosts team confidence in handling emergency situations. Furthermore, training sessions can serve as opportunities to update the workforce on any new regulations or technologies being introduced to the worksite.

In addition, providing access to external certification programs can bolster the credentials of your workforce and raise your company’s overall safety standards. Consider partnerships with professional bodies that offer specialized courses tailored to the unique challenges of the construction industry. Over time, consistently investing in skills development yields richer dividends, culminating in a workforce that is not only competent but also adaptive to new methodologies and proactive in minimizing risks. Remember, a well-trained team is one of your most valuable assets, forming the frontline of your risk management strategy.

6. Implementing Technology for Risk Management

With technology evolving, using specialized software for risk management can streamline the process, provide accurate data, and offer insights for better decision-making. From cloud-based platforms to AI-driven analytics, these innovative tools are transforming how contractors approach risk. Imagine a future where predictive models alert managers of potential risks well before they materialize. Such is the power of integrating data analytics into your risk management strategy. These insights allow for tailored responses, whether it involves adjusting manpower allocation or tweaking timelines to mitigate anticipated setbacks. Moreover, technology enables better documentation, simplifying compliance efforts and facilitating swift retrieval of records during audits.

Another exciting tech innovation in risk management is the use of Internet of Things (IoT) devices. These devices can provide real-time monitoring of various construction parameters, alerting you to any anomalies that might signal a risk. For instance, IoT sensors can track environmental conditions like wind speed or structural stability in real-time, ensuring immediate action can be taken to prevent accidents. Adopting such cutting-edge technology aligns with the growing trend towards digital transformation in the industry. Contractors embracing technology find themselves better equipped to manage the complexities of modern construction projects, ultimately reinforcing both safety and efficiency on-site.

7. Communicating Effectively with Stakeholders

Open and transparent communication with all stakeholders helps in aligning on risk management strategies and ensures collaborative efforts to mitigate risks. Effective communication goes beyond just keeping stakeholders informed—it involves active listening and genuinely incorporating stakeholder feedback into your planning processes. Whether it’s clients, subcontractors, or team members, each party offers a unique perspective that can enhance risk management strategies. Regular meetings and updates serve as platforms for discussing ongoing issues and potential risks, creating a shared understanding of project dynamics.

Moreover, documentation of these communications is vital. A centralized communication system enables seamless information flow across various parties, facilitating timely response to any emerging risks. Contractors should encourage open forums where stakeholders can express concerns and suggest improvements. By fostering a culture of inclusivity and collaboration, the likelihood of unforeseen challenges diminishes. Transparent communication aids in building trust, leading to more cohesive efforts and a unified approach to risk management, ultimately contributing to project success.

8. Reviewing and Adjusting Risk Strategies Regularly

Risk assessment is not a one-time task. Regularly reviewing and adjusting your strategies ensures they remain effective and relevant to current conditions. The construction landscape is dynamic, with regulations evolving and project scopes frequently altering. It’s important to schedule periodic reviews of your risk management strategies, taking into account feedback from recent projects as well as lessons learned. Such reviews allow you to evaluate what strategies worked, identify areas for improvement, and anticipate new challenges that might arise.

Integrating feedback loops into your risk assessment process can highlight inefficiencies and provide direction for future enhancements. The insights gained from these loops can inform adjustments, whether it’s adopting new technologies or redefining safety protocols. Keep in mind that a robust risk management strategy is flexible and adaptive to change, ensuring project resilience against unforeseen challenges. By continually refining your approach, you not only safeguard your projects but also cultivate a culture of continuous improvement—laying the groundwork for consistent progress and innovation.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com
What Should You Look for in the Best Workers Compensation Insurance Companies?

Finding the right workers compensation insurance company can feel like a daunting task. With so many options available, it can be challenging to know what to prioritize when making your choice. In this guide, we’ll walk you through the essential factors to consider to ensure you select the best provider that meets your needs and protects your workers.

Two professionals exchanging documents in an office setting, focusing on paperwork and data analysis.

Assess Financial Stability

It’s vital to choose an insurance company that is financially stable. This ensures they can meet their obligations and provide the necessary coverage when claims arise. Checking their ratings with agencies like AM Best or Standard & Poor’s can offer valuable insights.

Financial stability is more than just having deep pockets. It’s about having the resources to quickly manage claims and a proven record of doing so. Companies with solid financial health are often easier to work with and usually less likely to raise premiums unexpectedly.

You should also look into any public financial records the company may have. Understanding their investment strategies and revenue streams can provide an even deeper understanding of their financial health.

Evaluate Customer Service

Good customer service is key in any insurance provider. Look for companies that offer responsive, clear communication, and have a reputation for efficiently handling claims. Reading reviews and testimonials can help gauge their service quality.

Consider companies that have 24⁄7 support. This is especially important in industries where accidents can happen at any time and immediate assistance is required. Customer service that goes above and beyond will not only ease your mind but may also lead to quicker claim resolutions.

Some companies also offer digital solutions like mobile apps for easy policy management and claim tracking. This convenience might be a factor worth considering, as it could save valuable time.

Review Coverage Options

Ensure the insurer provides comprehensive coverage options that suit your specific industry needs. Each business is unique, so it’s essential that coverage aligns with potential risks in your sector.

Some companies offer customizable insurance packages, allowing you to select only the coverage you need. This can optimize your protection while keeping costs in check. It’s essential to weigh your options and consider how well a package fits your requirements.

Evaluate whether the insurance provider covers legal fees, medical expenses, and wages for injured employees. A full spectrum of coverage can provide peace of mind in challenging times.

Consider Policy Costs

While cost shouldn’t be the sole deciding factor, it’s important to compare the premiums and policy costs. Look for a company that offers competitive rates without compromising on essential coverage.

There might be hidden costs or fees associated with some policies, so it’s crucial to read the fine print carefully. Transparent pricing structures are a sign of a trustworthy provider and help you budget efficiently.

Discuss potential discounts for long-term clients or businesses with a low history of claims. A little negotiation can go a long way and might lead to significant savings over time.

Analyze Claims Process

Understanding the claims process is crucial. Opt for companies that offer a straightforward, transparent process with a history of quick and fair claim resolutions.

Reading client testimonials about their experiences during the claims process can be eye-opening. Some companies may have hidden procedures that can cause delays, which is not something you want during a crisis.

Check if the insurer offers a dedicated claims specialist. Having one point of contact can make the process less complicated and help in expediting claim resolutions efficiently.

Check for Industry Experience

Experience in your industry can be a valuable asset. Insurers with a track record in your line of business are more likely to understand your specific needs and risks involved.

Industries like construction or healthcare have unique challenges and risks. Choosing an insurance provider familiar with these can ensure they offer advice and coverage tailored for these specific areas.

Review any industry awards or recognitions an insurer may have. This often indicates a level of expertise or commitment to service in that particular sector.

Conclusion

Choosing the best workers compensation insurance company is crucial for your business and employees. By considering the factors discussed, you’re well on your way to making an informed decision. Remember, the right insurer not only offers financial protection but also provides support and peace of mind when it’s needed most. Visit BGES Group to learn more about how we can support your business needs.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com


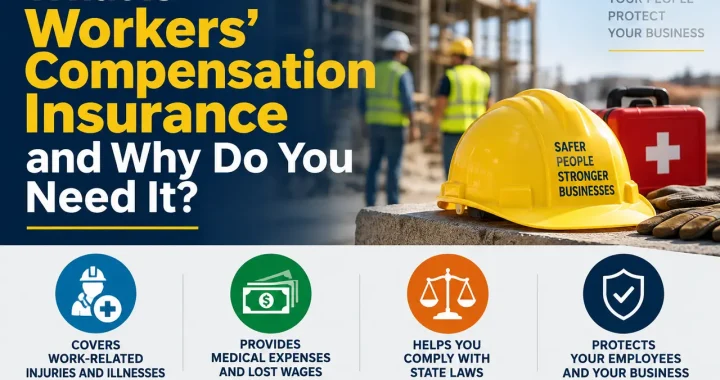
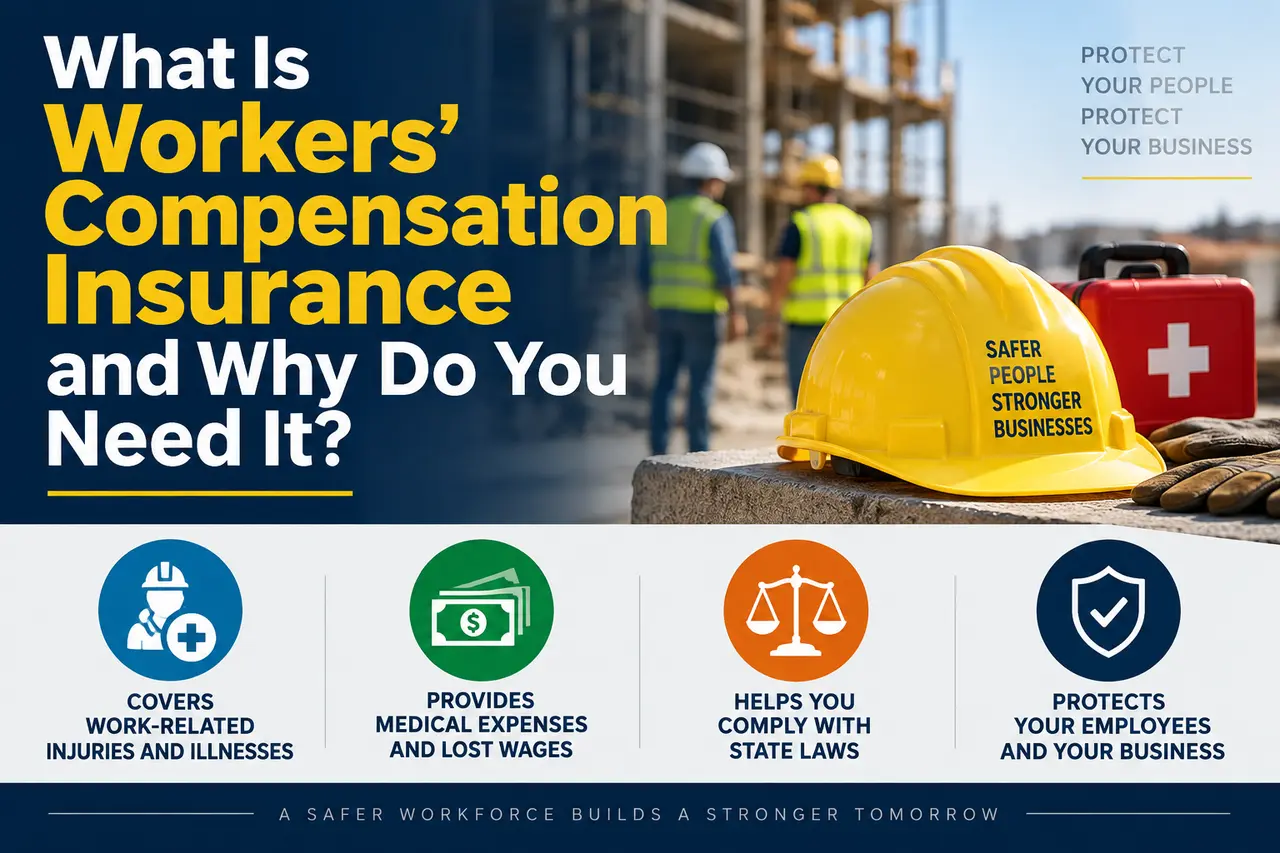
What Is Workers’ Compensation Insurance and Why Do You Need It?

Workers’ compensation insurance can seem like a complex topic, but it’s an essential component for businesses and employees alike. This guide will break it down into simple terms, helping you understand what it is, how it works, and why it is important.

Understanding Workers’ Compensation Insurance

Workers’ compensation insurance is fundamental to maintaining a healthy and safe workplace. At its core, it offers a safety net for employees who suffer injuries or illnesses due to their job responsibilities. Whether it’s a slip and fall, exposure to harmful substances, or repetitive stress injuries, this insurance provides necessary benefits to ease the burden.

This type of insurance is not only beneficial for employees but also provides employers with peace of mind and protection from potential liability. By having workers’ compensation insurance, employers are safeguarded against lawsuits that could otherwise result from workplace accidents.

Moreover, workers’ compensation insurance helps promote a culture of safety within the workplace. Knowing that injuries will be covered can encourage both employers and employees to focus on risk reduction and implementing preventive measures, thereby reducing the likelihood of accidents.

How Does Workers’ Compensation Insurance Work?

The process begins when an employee experiences a work-related injury or illness. It’s crucial for the employee to report the incident to their employer as soon as possible. This prompt notification ensures that the claim process starts efficiently and expedites access to benefits.

Once the employer is notified, they are responsible for filing a claim with their workers’ compensation insurance provider. After receiving the claim, the insurance company will assess the situation, which often involves reviewing medical reports, speaking with the injured employee, and consulting with the employer. It’s their job to determine the validity and extent of the claim to outline what benefits will be provided.

A successful claim results in the insurance covering necessary medical costs, providing compensation for lost wages during recovery, and funding rehabilitation if needed. This coverage ensures that injured employees can focus on recuperation without financial worry.

Employers can also consider seeking the assistance of insurance specialists to guide them through this process, ensuring all legal requirements are met, and the injured worker receives their due benefits swiftly.

Why Is Workers’ Compensation Insurance Important?

For businesses, workers’ compensation insurance is more than just a legal obligation; it is an essential way to operate responsibly. By having the right coverage, businesses can protect against unforeseen medical costs and litigation expenses that arise from workplace incidents, potentially saving them from financial strain.

From the employees’ perspective, the importance of this insurance cannot be overstated. It offers a financial safety net during recovery periods, ensuring that medical bills and other related expenses are not a personal burden. This support can greatly enhance morale and trust, as employees feel valued and secure, knowing their employer has their best interests at heart.

Moreover, a commitment to workers’ compensation insurance reflects a business’s dedication to employee welfare. It demonstrates the company’s proactive approach to fostering a healthy work environment and its readiness to support its workforce through all eventualities.

Who Needs Workers’ Compensation Insurance?

The majority of businesses with employees are legally required to maintain workers’ compensation insurance. However, the specifics can vary depending on factors such as location, business size, and industry.

Small business owners might question whether they need workers’ compensation insurance, especially if they employ only a handful of people. Nevertheless, it’s crucial to understand that even a single employee can pose a significant risk if they suffer an injury on the job without adequate coverage.

Understanding your state’s requirements is essential, as non-compliance could lead to hefty fines or legal actions. For example, some states have particular criteria, such as the number of employees or the nature of the job, that determines coverage necessity.

Consulting with professionals such as legal advisors or contacting insurance providers can help clarify your obligations and ensure you’re not inadvertently violating local labor laws.

How to Choose the Right Workers’ Compensation Insurance

Choosing the perfect plan for your business can seem daunting, but by evaluating your needs and understanding the specifics of workers’ compensation insurance, you can find the right fit. First, analyze your business’s risk profile by considering factors such as industry sector, number of employees, and types of jobs performed.

It’s beneficial to engage with a knowledgeable insurance broker to explore various coverage options available. Their expertise can be invaluable, guiding you through the intricacies of different packages and ensuring you choose a plan that meets both budgetary constraints and coverage requirements.

Furthermore, assess the reputation and customer service of potential insurance providers. A company with excellent track records and support can make a significant difference in times of need, offering swift responses and expert handling of claims.

Remember too that workers’ compensation insurance is not just a box to tick but an ongoing commitment to maintaining a secure and supportive workplace environment.

Why You Should Consider Workers’ Compensation Insurance

Workers’ compensation insurance is not just a legal requirement; it’s a vital safety net for both employers and employees. By understanding its importance and ensuring you have the right coverage, you protect your business and show your employees that you value their well-being. To learn more about how to protect your employees and business, visit our homepage.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com
What Are the Best Workers Compensation Insurance Companies for Contractors?

Navigating the world of workers compensation insurance can be daunting, especially for contractors who have unique needs and risks. Finding the right insurance company can make all the difference in ensuring both compliance and peace of mind. In this guide, we’ll explore some of the best workers compensation insurance companies for contractors, providing insights into what makes them stand out.

Group of construction workers in safety gear collaborating at a city construction site.

Why Contractors Need Specialized Workers Compensation Insurance

Contractors face various risks such as worksite injuries, accidents, and varying project requirements. Standard insurance policies may not address these complexities effectively, making specialized workers compensation insurance essential for this sector. It provides coverage specifically designed to handle the hazards involved in construction and contracting jobs.

Moreover, contractors often work across state lines, each with differing legal requirements. A specialized insurance policy ensures compliance with regulations in all operational regions, safeguarding the business from penalties and legal challenges.

Specialized insurance provides peace of mind by acknowledging the unique demands of contracting work. It reduces financial risks associated with workplace injuries, which might otherwise result in significant business interruptions.

Key Features to Look for in a Workers Compensation Policy

When evaluating workers compensation policies, contractors should prioritize comprehensive coverage that includes medical expenses, rehabilitation costs, and lost wages. This ensures employees recover without financial stress, enhancing workplace morale.

The claims process should be straightforward, facilitating quick responses to incidents and reducing downtime. Look for insurers that offer 24⁄7 claims assistance, as immediate reaction to incidents is crucial in the contracting business.

Customer support should be proactive and knowledgeable, providing timely updates and consultations. This support is vital for navigating complex claims processes or understanding policy details.

Top Companies Offering Workers Compensation Insurance for Contractors

Several companies are known for their exceptional workers compensation insurance offerings tailored to contractors. These include firms with a strong reputation for processing claims efficiently and providing excellent customer service.

For instance, ABC Insurance specializes in customized policies that cater specifically to the needs of contractors. With flexible plans and affordable premiums, they remain a top choice for those in the construction industry.

XYZ Insurance offers a robust online platform where contractors can easily manage their policies and submit claims, demonstrating a commitment to technological adaptation.

Comparing Policies and Finding the Best Fit

Comparing policies is integral to finding the best fit. Look closely at coverage limits, exclusions, and premiums. Balance these against your company’s risk profile and financial capacity.

The reputation of the insurer should weigh heavily in your decision. Opt for companies with high customer satisfaction ratings and positive feedback on claims handling.

How to Apply for Workers Compensation Insurance

The application process for workers compensation insurance is straightforward but requires attention to detail. First, gather all necessary business documents including employee records and safety protocols.

Next, contact potential insurers to discuss your needs and request quotes. Consider engaging with brokers who can offer an unbiased comparison of available options.

Finally, once you’ve selected a policy, fill out the application forms thoroughly. Ensure all information is accurate to avoid delays in processing your coverage.

Making the Right Choice for Your Business

Selecting the best workers compensation insurance company is crucial for contractors who want to safeguard their business and employees. By considering factors like coverage options, customer service, claims process, and pricing, contractors can make a well-informed decision. Ultimately, the best choice will be the one that aligns most closely with their specific business needs and risk profile.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com
 

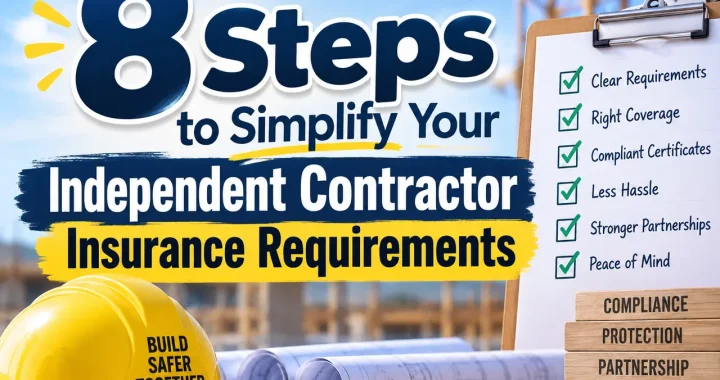
8 Steps to Simplify Your Independent Contractor Insurance Requirements

Navigating the world of independent contractor insurance can feel overwhelming, with so many options and requirements to consider. This guide will walk you through practical steps to make the process less daunting and more manageable, ensuring you get the coverage you need without unnecessary stress.

1. Understanding Your Basic Insurance Needs

Before diving into policies and providers, it’s crucial to identify what types of coverage are essential for your business model and industry. Start by considering general liability insurance, which most businesses need to cover potential claims related to bodily injury or property damage. If your work involves professional advice or services, professional liability insurance, also known as errors and omissions insurance, may be necessary to protect against negligence claims. Additionally, depending on where you operate, workers’ compensation insurance might be required if you have employees or sub-contractors.

Finally, be sure to examine the unique risks your line of work entails. For instance, if you’re a freelance photographer or videographer, you might need specialized equipment insurance. Understanding these foundational needs helps you avoid overpaying or assuming unnecessary risks that could financially destabilize you and your business.

2. Researching Different Insurance Policy Options

Exploring the variety of insurance policies available helps ensure you choose the most appropriate coverage to suit your specific needs as an independent contractor. Start by utilizing online comparison tools that provide insights into what different insurers offer for similar premiums. Such resources can save you time while ensuring you aren’t missing key protections relevant to your field of work.

Additionally, review insurance company reputations and customer feedback. This can often be discovered through forums and platforms where independent contractors discuss experiences. Ask your industry peers or mentors for recommendations. Understanding the nuances and fine print of various policies will guide you to make informed decisions, ensuring you adequately protect your livelihood and professional reputation.

3. Consulting with a Reliable Insurance Advisor

An insurance advisor can clarify complex policy details and recommend the best options based on your unique situation and requirements. Advisors possess the expertise to navigate the intricate details of policy language, which can often be confusing. They can ensure you’re not over-insured or under-insured by focusing on what’s necessary for your unique situation, providing peace of mind that you’ve protected your business interests appropriately.

Consider setting up a consultation with an advisor who specializes in insurance for independent contractors. Their industry-specific knowledge will further tailor recommendations to meet your specific needs. This personalized help is essential when considering how to protect your business assets and ensure continuity in your operations. Remember that consulting a professional could save you both time and resources while shielding you from potential liabilities.

4. Assessing the Coverage for Common Risks

Consider the typical risks associated with your profession to decide on the most necessary coverage and avoid under-insurance. Common risks might include client lawsuits, data breaches, or work-related injuries, depending on your industry. By identifying these, you can better understand what coverage is most critical.

Each industry has its own unique set of risks, and identifying them will lead to a more customized and effective insurance plan. For instance, if you work in the digital space, cyber liability insurance might become a priority. Keep up-to-date information on newer industry risks by reading relevant literature and industry reports. This ongoing study helps you tweak your insurance to match evolving professional hazards.

5. Comparing Quotes from Different Insurers

Gathering quotes from various insurance providers enables you to make an informed choice about the best coverage at a competitive price. Use online tools to collect these offers swiftly, ensuring you’re comparing apples to apples by matching policies on coverage limits and conditions.

Comparing might involve checking policies against each other for elements such as deductibles, exclusions, and additional perks like legal support. This process ensures you extract the best possible value from your insurance spending. Always consider the provider’s reliability and history alongside price to strike a balance between cost and coverage efficiency. Seeking assistance through a pricing comparison service can streamline this process considerably.

6. Customizing Your Insurance Policy

Tailoring a policy specific to your operations can help ensure it fully aligns with your business needs and protects against your particular risks. Customization can involve adding riders for certain risks or adjusting coverage limits based on your asset valuation. Don’t hesitate to update your policies as your business grows or pivots in its focus.

This involves ongoing dialogue with your insurance provider to adapt your policy as necessary. Whether seeking reduced premiums by demonstrating reduced risk factors or upgrading coverage as new business activities arise, adequate customization maintains alignments between business growth and protection. Being proactive in your policy’s viability means longer-term cost savings and uninterrupted business continuity.

7. Keeping Documentation Organized

Maintaining a clear organizational system for your insurance documentation simplifies managing your policies and renewals. Develop a dedicated digital and physical folder system, ensuring you have easy access when policy renewals or claims situations arise.

Consider leveraging digital tools or management apps that help you keep track of premium payments, renewal dates, and contact details. Utilizing technology solutions helps you stay on top of important insurance details efficiently, freeing you to focus on growing your business without administrative burdens.

8. Reviewing Your Coverage Regularly

Regular reviews of your insurance coverage ensure it continues to meet the changing needs of your independent contracting work. This can be annually or whenever significant changes occur, like company expansions, shifts in client profiles, or new service offerings.

As your professional landscape evolves, so too should your insurance coverage. Keep ahead of potential adverse scenarios by scheduling annual check-ins on your policy’s relevancy. Adjusting as needed not only brings peace of mind but can also refine your premium costs, supporting your bottom line more effectively. Additionally, these reviews help identify and rectify gaps in coverage you may not have originally anticipated.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com


20 Professional Liability Insurance Myths Debunked

Professional liability insurance is a crucial protection for many businesses, yet it remains shrouded in myths and misunderstandings. In this blog, we’ll clear up some of the common misconceptions about professional liability insurance so that you can confidently understand and utilize your coverage.

Close-up of business professionals reviewing documents at a meeting.

1. Its Only for Large Corporations

Many believe that professional liability insurance is only necessary for large companies, but small businesses and freelancers also face risks that could lead to costly legal actions. Imagine a scenario where a small consulting firm provides advice that the client claims led to financial losses. Without proper insurance, the legal ramifications could be devastating for the firm’s finances and reputation.

Navigating these risks without coverage is much like sailing without a life jacket. For instance, consider how a freelance graphic designer might inadvertently infringe on intellectual property rights because they failed to thoroughly verify their creative resources. In such cases, having professional liability insurance becomes the safety net that protects both the freelancer’s livelihood and reputation.

2. General Liability Insurance Covers Everything

While general liability insurance provides some protection, it doesn’t cover the specific risks associated with professional services, which is where professional liability insurance comes in. General liability might offer coverage for physical injuries or property damage on your business premises, but it falls short when handling negligence claims arising from your professional advice or services.

Consider the example of an architect whose design results in structural issues. While general liability might cover the physical repairs, it wouldn’t address the legal costs associated with defending the professional work. This is precisely why professional liability insurance is critical: it fills this crucial gap, offering a specialized shield that addresses risks unique to services-based professions.

3. Its Too Expensive for Small Businesses

Contrary to popular belief, professional liability insurance can be quite affordable, and the cost of not having it could be exponentially higher if a lawsuit arises. Small businesses often operate on tight budgets, but investing in this form of protection can save them from financial distress in case of claims.

Several insurance providers offer tailored plans based on industry and size, which can make this insurance surprisingly cost-effective. Plus, having coverage can sometimes result in better business relationships, as clients see your willingness to stand behind your work, instilling further confidence and potentially leading to more contracts.

4. Freelancers Dont Need Coverage

Freelancers can be held liable for any advice or services they provide, making professional liability insurance an essential safeguard even if you’re working independently. Unlike employees, freelancers aren’t protected by the umbrella of a larger company’s insurance policy, putting them at increased risk.

The gig economy is booming, and with this rise comes the necessity for freelancers to protect their niches. For example, a freelance consultant might offer strategic advice that a client later claims caused their business to falter. In such incidents, the financial outcome could be disastrous without insurance to mitigate legal costs.

5. It Only Covers Mistakes

Besides protecting against errors, professional liability insurance also covers omissions, negligence, and some breach of duty claims. This means if you forget to include a vital piece of information or unintentionally provide misleading advice, your policy can still offer protection.

The scope of this insurance is broader than many realize. Let’s say you run a tax consultancy—a small oversight in the client’s filing advice could lead to a penalty case. Here, professional liability insurance ensures that you’re covered not only for overt mistakes but also for any lapses in judgment or failure to provide correct recommendations.

6. Claims Are Rare

Many small business owners think claims are unlikely, but even one small mistake or allegation can lead to significant legal fees without proper coverage. While it might seem that the chances of facing a professional liability claim are minimal, the reality is that in our increasingly litigious society, the probability can be higher than anticipated.

7. Its Not Necessary for Every Industry

Every industry that provides a service should consider professional liability insurance, as it offers protection tailored to the risks specific to their field. Even in less high-profile professions, the possibility of a mistake impacting a client’s outcomes means it’s wise to stay protected.

8. You Can Add It Later as Needed

Waiting until after a claim arises is too late; having coverage in place beforehand ensures any potential issue is managed from the start. Insurance is not retrospective; it works proactively to mitigate risks that might arise from an oversight or unexpected client dissatisfaction.

9. My Business Is Too Young to Need Insurance

Even new businesses are vulnerable to claims from the outset, and professional liability insurance is essential to protect against early missteps. Just starting out might be when you need it most, as errors or customer dissatisfaction could have more severe impacts before you’ve established yourself in your field.

Professional liability insurance can also cover claims from third parties affected indirectly by your services, broadening the scope of protection. This is especially significant in industries where collaboration or subcontracting is common, ensuring all parties involved in delivering a service are appropriately protected.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com


Understanding Contractor Liability Insurance: A Clear Guide for New York Builders

Navigating the world of insurance can be daunting, especially for New York builders. Contractor liability insurance is crucial, yet often misunderstood. In this guide, we’ll break down what it means, why it’s essential, and how it can protect your business.

Two workers discussing plans on a sandy construction site, wearing safety gear.

What is Contractor Liability Insurance?

Contractor liability insurance is a type of coverage that protects contractors from financial losses due to claims of property damage, bodily injury, or personal and advertising injury. It is an essential safeguard for those in the construction industry, especially in a bustling state like New York. With the construction sector being one of the most risk-laden fields, this insurance acts as a financial shield, absorbing the adverse impacts that can arise from unforeseen lawsuits or claims. Whether it’s a minor slip by the site or a significant construction mishap, having the right insurance policy ensures that these incidents don’t turn into financial nightmares.

A unique aspect of contractor liability insurance is that it not only covers the usual property and bodily injuries but can also include personal and advertising injuries. This can be particularly relevant for builders engaging in marketing and promotional activities. Since legal landscapes are continually evolving, being informed about these aspects can go a long way in ensuring comprehensive coverage. Having a policy that encompasses these parts is often what distinguishes robust insurance plans from basic ones.

Why New York Builders Need It

In New York, regulations and standards for construction projects are stringent. Liability insurance not only ensures compliance with industry standards but also offers peace of mind by protecting against unexpected lawsuits and claims. The constant evolution of urban landscapes in New York means that projects often involve renovations and constructions in densely populated areas. This increases the likelihood of accidents, affecting third-party properties or individuals. Builder expectations in New York are high, and maintaining a flawless record requires mitigating risks judiciously.

Moreover, a significant factor for New York builders is the reputation that comes with having proper insurance coverage. Clients and partners prefer to work with builders who have taken the necessary steps to secure their operations against potential liabilities. This not only showcases a business’s professionalism but also builds trust, enabling growth within the industry. Simply put, having contractor liability insurance can be the deciding factor in winning more contracts and establishing a reputable standing in the competitive market.

Another critical aspect to consider is the financial stability that comes with being insured. New York’s construction projects often entail high capital investment, and a single lawsuit can derail financial plans. Insurance thus becomes more than just a safety net—it is an integral part of the strategic planning of any construction business aiming for longevity and success.

Key Components of a Policy

Understanding the key components such as coverage limits, exclusions, and deductibles is critical. Builders must ensure that the policy adequately meets their specific needs and covers all potential risks. For instance, coverage limits dictate the maximum amount an insurer will pay on a claim, essential for budgeting and risk management. Exclusions, on the other hand, are situations or circumstances the policy will not cover, which builders must be acutely aware of to avoid blind spots in their protection.

Navigating through a policy can uncover surprising clauses; hence, a keen eye for detail is indispensable. Additionally, deductibles play a crucial role as they determine out-of-pocket expenses before insurance kicks in. A balance between deductible amounts and premium costs is essential to maintaining cash flow efficiency while ensuring robust coverage. Understanding these aspects allows builders not just to comply with regulations but also to strategically allocate resources, minimizing overhead and maximizing protection.

New York builders may face specific challenges that aren’t common in other states, necessitating personalized policy terms. Customization is key, allowing insurance providers to tailor coverage plans to meet unique risks associated with different project scopes, locations, and regulatory requirements. This nuanced understanding of policy components is what empowers contractors, providing them with the tools to avoid costly legal pitfalls.

How to Choose the Right Policy

Choosing the right policy involves assessing the scope of your projects, the potential risks involved, and consulting with insurance professionals who understand the unique challenges New York builders face. It’s a multi-step process that begins with a thorough evaluation of the types of projects undertaken and the specific risks each project type might present. Consultation with professionals who have a deep understanding of the local legal and regulatory environment often provides invaluable insights into a tailored approach.

Engaging with a knowledgeable insurance advisor can make the process of selecting appropriate coverage less overwhelming. These experts can help guide decisions on policy features, interpret complex legal language, and assist with adjustments as project needs evolve. The intersection of legal advice and policy selection is crucial, ensuring that builders are not only protecting physical assets but also aligning their practices with legal obligations.

Considerations such as past claims history or unique project-specific regulations might further inform decision-making. Maintaining an open line of communication with the insurer throughout the duration of the policy can also optimize the benefits of coverage, ensuring that there is ample room for recalibration should project dynamics change or new risks emerge. Ultimately, selecting the right policy is about leveraging expertise to build a resilient foundation for ongoing and future project security.

Common Misconceptions

Many builders believe that general liability insurance is sufficient. However, contractor liability insurance specifically caters to the complexities of construction projects, covering more specific risks. While general liability might cover basic issues such as third-party damages, it often falls short in addressing the nuanced risks of construction, like specific environmental hazards or subcontractor errors.

A prevailing misconception is that all insurance covers are uniform and interchangeable, which is far from the reality that contractors face. Each policy is uniquely structured to cater to distinct facets of construction projects. For instance, pollution from hazardous materials or damages from faulty workmanship might require additional cover beyond general policies. The primary takeaway for contractors is understanding the differentiation in coverage scope between various insurance types.

To dismantle these misconceptions, builders are encouraged to educate themselves on the breadth of their coverage. Engaging in workshops or sessions focused on contractor liability risks can illuminate specific scenarios that their plans might not automatically cover. This form of proactive learning can prevent unwelcome surprises during claim filing, providing clarity and assurance in the event of disputes.

Steps to Secure Coverage

Securing a contractor liability insurance policy involves evaluating different insurers, comparing policy features, and understanding the fine print. Builders should be thorough in their research to ensure comprehensive protection. Start by collecting quotes from a variety of insurers, analyzing their offerings in terms of coverage types, limits, and exclusions. Look for insurers with a strong presence and reputation in the New York state area as they are more likely to align with regulatory standards.

Given the critical nature of securing the right insurance, partnerships with specialized brokers can ease navigation through policy options. These intermediaries act as a bridge, leveraging industry expertise to match builders with policies that suit their specific project demands and risk profiles. Evaluating insurers based not only on policy provisions but also on customer service quality and claim processing efficiency can result in a more holistic understanding and confidence in a partnership.

Once options are narrowed, the subsequent step involves negotiation. Often, insurers are willing to amend terms to better fit a contractor’s needs if approached strategically. This often entails discussing aspects like premium adjustments, modifying coverage limits, or exploring unique endorsements suitable for particular projects. Builders should also be vigilant in documenting all communications to protect interests throughout the life of the policy.

Our company specializes in providing comprehensive solutions tailored to your needs. Visit our homepage to learn more about how we can help secure your projects with the right strategies. Collaborating with experienced insurance providers ensures that the risk management strategy implemented is both practical and effective, giving builders a solid foundation to proceed with confidence.

Protecting Your Business with Confidence

Securing contractor liability insurance is a vital step in safeguarding your business against potential risks and liabilities. By understanding the specifics of the policy and working with a knowledgeable insurer, New York builders can operate with confidence and peace of mind.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com


12 Common Myths About Contractor Liability Insurance, Debunked

Contractor liability insurance can seem like a complex topic, steeped in industry jargon and legal terms. This often leads to misconceptions and myths that can cloud your understanding of what this insurance truly covers. In this blog, we’ll clear up the confusion by debunking some of the most common myths surrounding contractor liability insurance.

Two engineers in hardhats discuss projects at a busy construction site.

1. Insurance Covers Everything

It’s a common belief that contractor liability insurance covers all potential business risks. However, this insurance typically only covers specific types of damage or injury. It’s important to understand your policy details to know exactly what is and isn’t covered. Many people mistakenly assume that if they have this insurance, they’re safe from any liability, but the reality is far more nuanced. For example, contractor liability insurance generally does not cover intentional harm or damages related to the failure of a project to meet cost or time expectations. It’s essential to read the fine print and consult with an insurance expert to ensure you’re getting the coverage you need for your specific business scenario.

2. Low Risk Means No Insurance Needed

Some contractors think that if their business is low risk, they don’t need insurance. But accidents can happen in any working environment, and liability insurance can protect against unforeseen circumstances. Consider the implications if something were to go awry on a supposedly ‘low-risk’ project. Even minor mishaps can result in costly legal defenses or settlements. Furthermore, liability insurance not only protects the contractor but also reassures clients, showcasing professionalism and dedication to covering all bases, regardless of the perceived risk. So, rather than gambling on being low risk, it’s wiser to invest in an appropriate level of insurance coverage.

3. Personal Insurance is Sufficient

Relying on personal insurance for a business is a risk. Personal insurance policies are not designed to cover business-related incidents, leaving you exposed to significant gaps in protection. Many contractors believe that their homeowner’s insurance or personal liability policy will cover any incidents that happen while conducting business, but that’s not the case. Personal insurance policies generally exclude business activities, meaning contractors are left vulnerable to significant financial loss in the event of a claim. It’s vital to differentiate between personal and business insurance as the specifics of coverage can impact financial safety and professional credibility.

4. Only Large Contractors Need Insurance

It’s a myth that only large companies or contractors need liability insurance. Whether you’re a sole proprietor or running a small partnership, having the right protection is vital. The size of your operation does not make you immune to risks. Small businesses and individual contractors might face unique challenges that could lead to lawsuits or legal actions. Liability insurance can provide crucial financial support in these scenarios, ensuring that your personal and business assets are protected from several types of claims. Therefore, instead of viewing insurance as a burden, think of it as a shield against unforeseen financial setbacks.

While liability insurance often helps with legal costs, not all policies guarantee full legal defense coverage. Check the specifics of your policy to understand the extent of legal protection provided. It’s easy to assume that every policy will cover all legal expenses, but limits and exclusions can set boundaries on what is actually paid for by your insurer. Some policies offer reimbursement for legal costs up to a certain amount, while others may exclude certain legal procedures altogether. This variability emphasizes the importance of understanding your policy’s terms and the necessity of asking questions before purchasing coverage.

6. All Damages are Covered

Contractor liability insurance doesn’t cover every type of damage. For instance, damages due to faulty workmanship are usually excluded, highlighting the need to review your policy keenly. This means that if the quality of your work is in question or if a project doesn’t perform to expected standards, your insurance may not offer the financial relief you anticipate. It’s also typical for policies to exclude damage arising from wear and tear or particular environmental conditions. Such exclusions stress the importance of understanding the breadth of your coverage and possibly supplementing your policy with additional types of insurance to cover gaps in protection.

7. It Protects Against Professional Errors

This policy does not cover professional errors, which require errors and omissions insurance. Understanding the difference between policies ensures the correct coverage. Many contractors fall into the trap of thinking their liability insurance is a catch-all, but in reality, it primarily covers third-party claims for bodily injury or property damage. If a client sues for economic loss caused by negligence or failure to deliver promised services, contractor liability insurance may not be applicable. Securing a comprehensive risk management strategy, therefore, often involves multiple policies to safeguard against the nuanced risks particular to your trade.

8. Premiums are Non-Negotiable

Many believe premiums are fixed and non-negotiable. In reality, premiums can often be adjusted based on your safety record, claims history, and the specific coverages you need. Insurers assess risk differently, and showing you run a safe and efficient operation can lower your premium costs. For instance, maintaining a clean safety record and implementing robust risk management strategies can not only reduce the likelihood of incidents but also lower your premium over time. It’s advisable to work closely with a knowledgeable insurance agent to tailor a policy to your needs, potentially obtaining discounts or customized coverage.

9. Claims Always Lead to Premium Increases

While it’s true that claims can lead to premium increases, it’s not guaranteed. Insurers look at several factors before deciding to increase premiums. The nature and frequency of claims, their severity, and the overall claims history of a policyholder are considered. Furthermore, insurers often weigh these claims against industry standards and your overall risk profile. In some cases, a single minor claim might not affect your premiums significantly. Being proactive about risk management and promptly addressing any issues that arise can help you maintain more stable insurance rates over time.

10. Past Coverage Protects Future Work

Contractor liability insurance is typically not retroactive, meaning past coverage doesn’t protect future work. Continuous coverage must be maintained for ongoing protection. It’s a common misconception that simply having been insured in the past provides a buffer for future projects. Each new contract or job comes with distinct risks that require up-to-date protection. Moreover, switching insurers or allowing a policy to lapse can create gaps in coverage, potentially leaving you vulnerable to claims arising from ongoing projects or newly completed work. To ensure seamless protection, continue your coverage without interruptions.

11. Cancelling Saves Costs Without Consequences

Canceling a policy might seem like a cost-saving measure, but it leaves you open to risks. Always consider the potential consequences before canceling your coverage. Without liability insurance, you’re exposed to financial damages from claims, which can far exceed the cost of maintaining your policy. Moreover, future attempts to insure your business might result in higher premiums if insurers view the gap in coverage unfavorably. Rather than haphazardly canceling your policy, evaluate your coverage needs continuously and adjust your policy or provider to better match your financial situation without sacrificing essential protection.

12. Shopping Around Isn’t Necessary

Many assume shopping for multiple insurance quotes is a waste of time. However, exploring different options can lead to better coverage and savings tailored to your business. Not all insurance policies are created equal, with varying limits, exclusions, and premiums. Spending time comparing offers allows you to find a policy that best fits your specific needs and budget. Also, different insurers may offer unique benefits or discounts that aren’t universally available. By being proactive and thorough in your search, you’ll not only find the most competitive pricing but also gain peace of mind knowing that you’ve secured the best possible protection for your business.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com


12 Smart Strategies to Minimize Your Contractor Insurance NY Cost

Managing the costs associated with contractor insurance in New York can sometimes be challenging, but with smart strategies, it’s possible to keep expenses in check. In this blog, we’ll uncover practical tips to help you reduce your insurance costs without compromising on coverage.

Architects wearing hard hats review blueprints inside a building under construction.

1. Understanding Your Coverage Needs

Knowing exactly what coverage you need prevents unnecessary spending and helps you select the optimal policy for your business. Start by evaluating the specific risks associated with your operations. Consider factors such as the size of your business, the number of employees, and the type of projects you undertake. By clearly defining these needs, you can avoid overpaying for unnecessary coverage.

Break down each aspect of your business to get a clearer picture. For instance, if your operations are primarily carpentry-related, you can focus on specific policies that cater to potential carpentry risks. This tailored approach not only minimizes your premium but also ensures that you’re adequately protected against relevant risks.

2. Shop Around for Competitively Priced Policies

Comparing quotes from multiple insurers can reveal significant differences in pricing, allowing you to choose the best deal for your budget. Don’t be afraid to leverage online tools to expedite this process. Sites that aggregate insurance providers can give you instantaneous access to a range of quotes, letting you compare them at a glance.

Additionally, fostering relationships with insurance brokers can be beneficial. They often have industry insights that can help you navigate complex pricing structures, ensuring you never overspend on your premiums.

3. Bundle Your Policies for Discounts

Many insurers offer discounts if you combine multiple types of insurance, such as general liability and property insurance. This approach is not only cost-effective, but it also simplifies managing your policies, reducing administrative overhead.

Before committing, assess if the bundled coverage meets your full needs. Review the terms carefully to avoid any coverage gaps that could leave your business vulnerable. Bundling is a great way to streamline costs, but it’s crucial to maintain comprehensive coverage.

4. Maintain a Clean Claim History

A good claim history can lead to discounts and favorable rates from insurers, reflecting your risk management practices. Strive to minimize incidents that could lead to claims by fostering a safety-conscious work culture.

Consider implementing a training program for your staff focused on job safety and incident prevention. This not only enhances the skill set of your team but also reinforces the importance of maintaining a claim-free record.

5. Invest in Workplace Safety

Implementing robust safety protocols can decrease the likelihood of accidents, leading to lower insurance costs over time. Install safety gear and ensure it’s regularly checked and maintained. Moreover, conduct regular training sessions and safety audits to identify aspects that can be improved.

Employing technologies like wearable safety devices can further enhance workplace safety by monitoring worker movements and environment conditions in real-time. Such proactive steps not only safeguard your employees but also demonstrate your commitment to minimizing workplace hazards, which is favorable in the eyes of insurers.

6. Raise Your Deductible

Opting for a higher deductible reduces the insurance premium, which can be beneficial if your business rarely files claims. However, it’s crucial to evaluate your business’s financial readiness to cover these increased out-of-pocket costs in the event of a claim.

This strategy is best suited for businesses with sufficient cash reserves to manage unexpected expenses. It’s a calculated risk, but when managed well, it can significantly lower your monthly premium payments while keeping critical insurance coverage intact.

7. Utilize Claims-Free Credits

Some insurers reward businesses that do not file claims with credits, which can reduce your premium costs. To maximize these benefits, ensure preventive measures are in place to mitigate potential risks.

Regularly consult with your insurance provider to explore how you can maintain and maximize these credits. This proactive management demonstrates your commitment to maintaining a low-risk profile, encouraging more favorable terms from insurers.

8. Review Your Policy Annually

Regularly reassessing your coverage ensures it still aligns with your current business operations and prevents over-insurance. Each year, when you review your policies, consider changes in business size, scope, and operations that could impact your insurance needs.

Policy assessments should include consultation with your provider, discussing any changes that could affect your coverage needs and costs. Staying on top of your policy ensures that you are always optimally covered without overspending.

9. Implement Risk Reduction Strategies

Showing insurers that you’re actively managing risk can lead to lower premiums. Risk management systems could include measures like routine equipment maintenance, employee training, and implementation of safety regulations.

Incorporating risk assessment software can assist in identifying potential hazards before they occur. Demonstrating such vigilance can reassure insurers of your business’s commitment to safety, translating into lower premium rates.

10. Consider Membership Associations

Joining professional associations may offer access to discounted insurance rates specifically for members. These associations often have partnerships with insurance providers to offer exclusive rates to members.

Being part of a professional community not only offers cost benefits but also provides networking opportunities to share best practices, further enhancing your business’s efficiency and risk management strategies.

11. Negotiate With Your Insurer

Open communication with your insurer about your budget can sometimes lead to better offers and rates. Don’t hesitate to ask for discounts or inquire about any promotional rates that might be available.

Negotiation isn’t just about price; it can also include tailoring coverage to better suit your specific needs. Building a strong relationship with your insurer can lead to more personalized service and potential cost savings.

12. Stay Updated on State Regulations

Being informed about changes in local regulations ensures your coverage remains compliant and cost-effective. Regulatory changes can affect your coverage requirements and, ultimately, your premiums.

Stay connected with local industry groups and regulatory boards to receive timely updates on any changes. This proactive approach not only helps you avoid non-compliance penalties but also aids in optimizing your insurance coverage efficiently.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com