12 Myths About Contractor Insurance Companies Debunked for New York Contractors

Navigating contractor insurance can be confusing, especially with so many myths floating around. As a New York contractor, it’s important to have a clear understanding to protect your business effectively. Let’s dive into and debunk some of the common misconceptions about contractor insurance companies.
1. Contractor Insurance is Unnecessary if You Have a Small Business

Even small businesses face risks that could lead to financial ruin. Insurance protects against potential liabilities that could arise at any scale. Many small business owners believe that their minimal operations exempt them from needing comprehensive insurance coverage. However, accidents or mishaps don’t discriminate based on company size. Whether it’s a slip and fall at your office or a minor error on a site, these incidents can result in substantial financial loss. Investing in contractor insurance can protect your business from unforeseen claims and ensure its longevity in the industry.

2. All Contractor Insurance Policies are the Same

Insurance needs vary greatly depending on project size and type. Customizing your policy ensures you’re covered for specific risks. Not all contractor insurance policies are created equal. Some might offer protection against property damage while others provide coverage for bodily injuries or equipment loss. For example, a contractor working on high-rise buildings may need different coverage than someone only handling residential projects. By understanding the distinct nuances of your projects, you can choose a policy that aligns closely with your unique business demands. This tailored approach not only provides peace of mind but also maximizes your investment in insurance.

3. Claims Are Rare, So Insurance is a Waste of Money

Unexpected accidents and mistakes are more common than you’d think. Insurance is a safety net that can prove invaluable. Many contractors mistakenly assume that claims are infrequent, leading them to question the value of their insurance premiums. However, even well-managed projects can encounter unforeseen hiccups. Whether it’s adverse weather causing delays or unexpected material defects, having insurance in place offers a lifeline. This not only cushions the financial impact but also ensures the continuity of operations, safeguarding both current and future projects.

4. Contractor Insurance is Too Expensive

Prices can be manageable by comparing plans and choosing coverage that fits your needs. Investing in insurance can save money in the long run. The perception that contractor insurance comes with an exorbitant price tag is a widespread myth. While some premiums can seem costly upfront, the potential expenses from an uncovered claim can dwarf these initial costs. With strategic planning, you can select coverage that fits your budget without compromising on essential protections. For example, bundling different types of coverage or opting for a higher deductible often results in reduced premiums, making comprehensive insurance a more attainable option.

5. You Only Need Basic Liability Insurance

While liability is important, other types of coverage, like property and worker insurance, can be crucial to comprehensive protection. Basic liability insurance is a foundational component, offering protection against third-party claims. However, this alone may not suffice for every contractor’s needs. Depending on your projects, you might need additional coverage such as tools and equipment insurance, professional liability, or workers’ compensation. Each aspect fortifies a different facet of your operations, creating a safety net that guards against varied risks inherent in the construction industry.

6. Once Covered, No Need to Review Your Policy

Regularly reviewing your insurance ensures it evolves with your business and continues to meet your requirements. Over time, a contractor’s business can experience considerable change. Whether it’s an expansion into new markets, updating equipment, or shifting your service focus, these modifications can significantly influence your insurance needs. As your operations expand, so might your liability. Regularly revisiting your insurance policy ensures that it accurately reflects your current business risks. Additionally, periodic reviews can highlight potential savings opportunities or new coverage options that might not have been available when the policy was first issued.

7. Insurance Companies Never Pay Out Claims

While frustrating, claims can be denied for valid reasons. Choosing a reputable insurer and understanding your policy minimizes issues. Contractors may harbor skepticism about an insurer’s willingness to honor claims. In reality, most denied claims result from misunderstandings about coverage specifics or from failing to meet policy terms. Building a transparent relationship with a reputable insurance provider can alleviate such concerns. Not only do trustworthy companies prioritize clear communication, but they also guide clients in understanding policy details, ensuring smoother claims processes when the unexpected arises.

8. Filing a Claim Will Always Raise Your Rates

While frequent claims can affect rates, a well-chosen policy with a good history often prevents drastic increases. Contractors often worry that filing a claim will instantly drive up their premium rates. While it’s true that a history of frequent claims can lead to an insurer reassessing your risk profile, isolated claims may not have as significant an impact. Opting for policies with claims forgiveness features can safeguard against rate hikes after your first incident. Additionally, maintaining a long-term relationship with an insurer who values consistency and loyalty can offer protection against abrupt rate changes.

9. Contractor Insurance Covers All Types of Damage

Policies specify exclusions and limitations. Knowing these ensures you’re aware of any additional coverage needs. One prevalent myth is that once you’re insured, any kind of damage will be covered without exceptions. In reality, every insurance policy has limitations and specific exclusions. Understanding what’s not covered—be it certain natural disasters, specific job types, or pre-existing damages—prepares contractors for potential additional liabilities. Reviewing the fine print and discussing these exclusions with your insurer can provide clarity, indicating if additional coverage is needed to comprehensively shield your business.

10. Only Liability Insurance Covers Court Costs

Different policies may cover legal expenses depending on the claim. Understanding your options helps in creating a strong defense. Legal challenges can arise from various aspects—be it client disputes, employee matters, or third-party claims. Liability insurance is often considered the go-to for covering legal expenses. Yet, other forms of insurance, such as professional liability or even certain endorsements within a policy, might offer legal cost coverage depending on the nature of the claim. By exploring these options, contractors can ensure they’re not left to bear the brunt of legal defenses alone.

11. Online Reviews are the Best Way to Choose an Insurer

While helpful, reviews don’t tell the whole story. Consulting an expert can provide a clearer picture and guide better choices. In the age of digital information, it’s tempting to rely solely on online reviews when selecting an insurance provider. While reviews provide valuable insights into user experiences, they often lack comprehensive details about specific policy terms or personalized service. Engaging with an insurance expert or broker can provide a deeper understanding of what each insurer offers, from tailored coverage options to claims processes, ensuring that you make a well-rounded and informed choice.

12. All Agents Offer the Same Deals and Coverage

Agents and brokers can have access to different policies and discounts. It’s vital to shop around to get the best deal. The assumption that every insurance agent or broker operates under a uniform framework is misleading. Each agent can possess unique affiliations with insurance companies, allowing them access to bespoke deals, endorsements, or discounts. By engaging with multiple agents, contractors can explore a variety of coverage options tailored to their specific needs. This process not only helps in finding competitive rates but ensures you select coverage options most beneficial for your unique circumstances.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com


How Does Risk Assessment Influence Contractor Insurance Cost?

Understanding the intricacies of contractor insurance costs can be challenging, especially when factors like risk assessment come into play. In this blog, we will break down how risk assessments can significantly influence the cost of insurance for contractors, providing clarity on its importance and impact.

Female engineer in safety gear at a construction site with steel structure background.

What is Risk Assessment?

Risk assessment involves identifying potential hazards and evaluating their likelihood and impact. It is an essential step in mitigating risks associated with various contracting projects. By undertaking rigorous risk assessments, contractors can create safer work environments, reducing the chances of accidents and the potential for liabilities.

In the world of contracting, risk assessment is not just a formality; it has practical implications on project success. By systematically studying the worksite and marking out potential hazards, contractors can devise strategies to prevent accidents before they occur. This proactive approach not only safeguards workers but also ensures the smooth progression of projects, minimizing downtime caused by unforeseen incidents.

Why Risk Assessment Matters for Contractors

Contractors face numerous risks, from physical dangers to financial liabilities. Proper risk assessments help contractors take preventive measures, ensuring a safer work environment and protecting their business interests. Addressing risks upfront can shield contractors from heavy financial losses and legal repercussions, fostering trust with clients and stakeholders.

Moreover, thorough risk assessment is paramount for securing project approvals and permits. It conveys a contractor’s dedication to implementing safety standards, thus potentiate the likelihood of winning contracts or tenders. This foundational practice highlights a contractor’s accountability and foresight, qualities that are highly valued in the industry.

Beyond safety and legal compliance, risk assessment plays a pivotal role in project planning and cost management. By anticipating potential hurdles, contractors can allocate resources more efficiently, avoiding costly interruptions. This strategic foresight not only optimizes operational budgets but also bolsters project timelines, ensuring completion within specified durations.

How Risk Assessment Affects Insurance Premiums

Insurance providers analyze risk assessments to determine the level of risk involved in a project. A thorough risk assessment can lead to reduced insurance costs as it demonstrates a contractor’s commitment to safety and risk management. Preemptive identification and mitigation of risks signal to insurers a lower likelihood of claims, often resulting in premium discounts.

The depth and quality of a risk assessment can directly impact how insurers perceive a contractor’s profile. By providing detailed reports on hazard control measures and safety training initiatives, contractors can depict their proactive attitude towards potential issues. Insurers appreciate this diligence as it reflects reliability and minimizes their potential payout, rewarding contractors with competitive insurance rates.

Conversely, inadequate or superficial risk assessments may portray a contractor as high-risk. Such perceptions can inflate insurance premiums or even result in policy declinations. Insurers need assurance that safety is a priority, which can only be attained through robust risk assessment practices. Thus, investing time and resources into comprehensive assessments is a prudent financial decision for any contractor.

Conducting an Effective Risk Assessment

To conduct an effective risk assessment, contractors should systematically identify, evaluate, and document the risks associated with their projects. Implementing control measures and regularly reviewing assessments are crucial steps. Incorporating feedback from onsite workers can provide invaluable insights into unrecognized hazards, ensuring all aspects of the project are protected.

Utilizing modern technologies can enhance the accuracy of risk assessments. For instance, drones and other remote sensing tools can access hard-to-reach areas and provide data for comprehensive analysis. Additionally, leveraging software for tracking and managing risk management tasks ensures that assessments are consistently updated, reflecting any changes in the project landscape.

Equally important is cultivating a culture of safety where workers understand the importance of reporting potential risks. Regular training sessions should be organized to update employees on safety protocols and emergency procedures. A workforce that is educated on risk assessment principles contributes actively to on-site safety.

Tips for Reducing Contractor Insurance Costs

Apart from thorough risk assessments, contractors can reduce insurance costs by maintaining safety records, complying with regulations, and investing in employee training programs. Demonstrating a commitment to ongoing safety improvements can make a contractor more attractive to insurers, potentially leading to lower premiums.

Another effective strategy is to invest in technology that aids in tracking safety metrics. For example, wearable devices that monitor worker vital signs or environmental conditions can provide real-time data, allowing contractors to swiftly address any developing issues and reduce the chance of worksite injuries.

Open communication with insurance providers can also be beneficial. Discussing your company’s specific risk mitigation strategies and safety training modules can lead to customized insurance plans, tailored to the unique needs of your operations, optimizing cost-efficiency.

Implementing a proactive approach to equipment maintenance is another critical component. Regular inspections and timely repair of machinery help prevent accidents and maintain the integrity of safety protocols on-site, reflecting positively in insurance evaluations.

Summing Up Risk Assessment’s Impact

Risk assessments play a critical role in determining contractor insurance costs. By accurately evaluating potential hazards, contractors can adopt proactive measures that not only ensure safety but can also result in more favorable insurance premiums. The key lies in understanding the specific risks associated with each project and mitigating them effectively.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com


Customizing Roofers Insurance for Maximum Protection

Navigating the world of insurance can be daunting, especially for specialized professions like roofing. Roofers face unique risks and challenges, making it crucial to have a tailored insurance policy that provides comprehensive coverage. In this blog, we’ll explore how to customize roofers insurance to ensure maximum protection, addressing specific needs and potential risks.

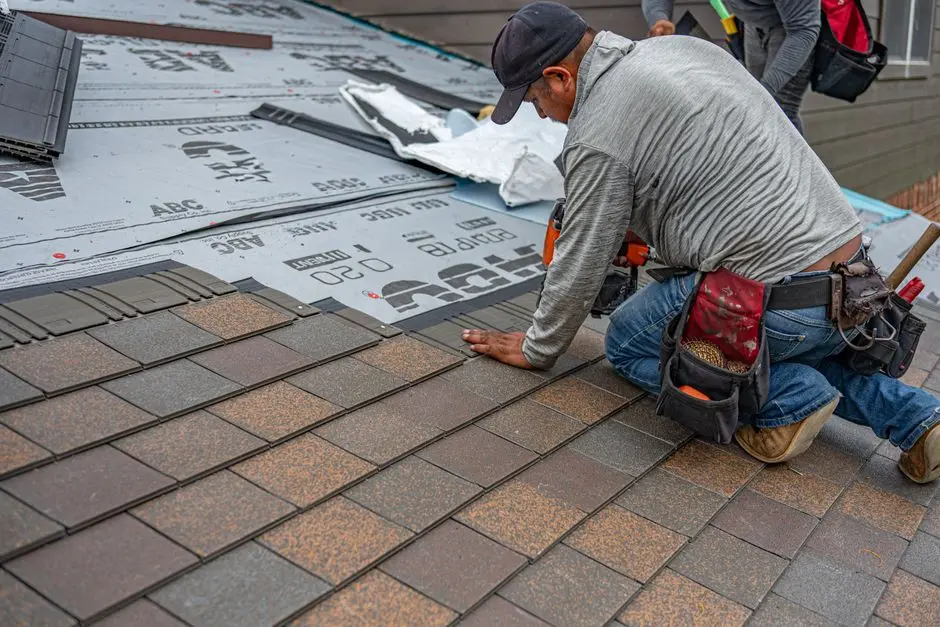
Skilled roofer installing asphalt shingles, ensuring quality home renovation.

Understanding the Risks in the Roofing Business

Roofers encounter numerous risks daily, from working at great heights to handling heavy materials. Accidents can occur in the blink of an eye, and factors such as weather conditions or equipment malfunction can exacerbate these risks. Slip and fall accidents are common, given the nature of rooftops and the materials used, while the potential for more serious incidents—like falling off a roof entirely—remains a significant concern. Understanding these risks is the foundation upon which comprehensive insurance is built. By grasping these potential hazards, roofers can make more informed decisions about what specific coverages to include in their insurance policy to reduce potential liabilities and protect their workforce.

In addition to physical risks, roofers also face liability risks when accidents or damages occur while working on client properties. This includes scenarios where workers accidentally damage a client’s property during installation or repair. Environmental factors, such as storms or extreme heat, can also contribute to the unpredictability and danger of the work environment. Fires and water damage can arise from unexpected weather changes, impacting not only the project at hand but the overall safety of the job site. By acknowledging these risks, roofers can adequately inform their insurance providers to ensure all such eventualities are covered, safeguarding their business operations.

Essential Insurance Components for Roofers

A comprehensive insurance strategy for roofers should encompass a variety of essential coverage components. General liability insurance acts as the bedrock, protecting your business against claims related to bodily injury or property damage that may arise while conducting work on clients’ roofs. This type of insurance is indispensable as it mitigates financial risks associated with litigation and compensatory claims from third parties. Without it, a single accident could potentially shutter your business due to overwhelming legal fees or settlements.

Another critical component is workers’ compensation insurance. This covers medical expenses and lost wages for employees injured on the job. Considering the inherent dangers of roofing, this type of insurance is non-negotiable for those in the industry. Additionally, property insurance is essential as it provides coverage for the physical assets of your business, such as equipment and tools, which are vital for daily operations. Together, these components not only offer a safety net but also convey professionalism and responsibility to clients, reassuring them that you are a credible business capable of managing unexpected incidents.

Tailoring Coverage to Fit Your Business Needs

Every roofing business is different, and therefore, needs a personalized approach to insurance. For small businesses or freelancers, a basic coverage package like general liability may suffice initially. However, as your business grows or your operations expand, additional coverages become necessary. For instance, operating in a high-risk area might require a more robust property insurance policy to account for increased exposure to environmental hazards. Furthermore, if your company undertakes diverse services such as installation, repair, and maintenance, consider policies that cater specifically to these varied jobs to ensure comprehensive protection.

Insurance needs can also vary depending on the geographical location of the roofing business. For instance, businesses operating in hurricane-prone areas may need to include specialized coverage to protect against storm damage. Similarly, companies might need to secure additional endorsements that cover subcontractors if they frequently use third-party services. An effective strategy involves closely examining historical data and future forecasts specific to your area to identify potential risks better and work with your insurance provider to tailor a policy that is as exhaustive as it is cost-effective.

Working with Insurance Providers for Optimal Cover

Choosing the right insurance provider can make all the difference. Building a strong relationship with your insurer is key to securing a policy that addresses your precise business needs while remaining financially feasible. When evaluating potential providers, consider their track record in serving businesses similar to yours and their ability to adapt policies as industry standards and legal requirements evolve. Transparency is crucial, so it is important to communicate openly about your business operations and any unique aspects that might affect coverage. This level of communication ensures your insurance policy is continuously aligned with your business’s evolving dynamics.

Engaging with insurance providers isn’t just a one-off transaction; think of it as an ongoing partnership. Provide your insurance agent with updates on any changes in your business model, such as diversification of services or expansion to new locations, which might necessitate adjustments in coverage. Insurers can offer insights into best practices for risk management and expose you to additional services like regular safety audits, which can lead to potential discounts on premiums, effectively lowering long-term costs while enhancing the safety of your operations.

Balancing Cost with Comprehensive Coverage

Insurance premiums can take a significant bite out of your business budget. Finding the sweet spot between affordability and adequate coverage can be challenging, but it’s not impossible. One effective strategy is to leverage bundling options provided by insurers. By combining multiple policy types—like general liability, property, and workers’ compensation—into one comprehensive package, businesses can often save significantly on overall costs. Moreover, higher deductibles can lower monthly premiums, but this should be approached cautiously as it shifts greater financial risk onto the business.

Another approach is conducting regular risk assessments to pinpoint areas where safety measures can be increased, potentially lowering insurance costs over time. Implementing on-site safety training and investing in quality equipment to reduce accident rates are proactive steps that demonstrate a commitment to minimizing risks, which insurers often recognize through premium reductions. By being strategic about the way risks are managed and leveraging the expertise of insurance providers, roofing businesses can successfully balance the need for comprehensive coverage with the constraints of their budget.

Securing Your Roofing Business with Customized Insurance

Customizing roofers insurance is not just about protecting your business but also about providing peace of mind. By understanding the unique risks your roofing business faces, you can tailor an insurance policy that covers all bases. This not only ensures safety but also allows you to focus on what you do best, knowing that your business is well protected. Consider working collaboratively with your insurance provider to tailor a policy that suits your specific needs, striking a balance between comprehensive coverage and cost-efficiency.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com


12 Questions to Ask Before Buying Window Installation Insurance

Choosing the right insurance for window installation can be a daunting task. With so many options to consider, it’s essential to know the right questions to ask to ensure you’re making an informed decision. In this listicle, we’ll guide you through the crucial questions to help you secure the best coverage for your needs.

1. What Does the Policy Cover?

Understanding the scope of your insurance policy is crucial. Ensure the policy provides coverage for all potential damages or liabilities related to window installation. This might include things like accidental damage to the windows during installation or injury to the installation team. It’s also vital to consider if the policy covers structural damage to your property that might occur during the process of installation. Always inquire deeply into the specifics of coverage, as general terms can sometimes mask the true extent of what an insurance policy includes. Knowing exactly what is covered can save you from unexpected costs in the future.

2. Are There Any Exclusions?

Every insurance policy comes with its exclusions. You should be aware of what circumstances or damages aren’t covered to avoid surprises later. Exclusions can often include pre-existing damages or wear and tear that occurs over time, which aren’t typically covered. Some policies might also exclude coverage for natural disasters unless specifically added to the policy. It’s important to ask the insurance provider for a clear explanation of exclusions, as this understanding will help prevent miscommunications and ensure you have the right expectations about what will be supported if you need to file a claim.

3. What is the Coverage Limit?

Check the maximum amount the insurance will pay out in the event of a claim. This will help determine if the coverage aligns with your project’s needs. Knowing your coverage limits is essential to assessing how protected you will be in worst-case scenarios. Sometimes, the financial repercussions of an incident might exceed the limit set by your policy, leaving you with a substantial out-of-pocket expense. To best protect your investment, evaluate whether the coverage limits are sufficient for both routine installations and larger scale or more complex window setups.

When examining coverage limits, it’s also beneficial to compare limits across different policies to ensure you’re getting the best deal for your needs. Some policies may appear similar at first glance but have significant differences in payout limits, which can be crucial during a claim. Therefore, conducting a thorough analysis is key to making a wise decision.

4. What Are the Premium Costs?

Knowing the cost of premiums is essential for budgeting. Compare different policies to ensure you’re getting a fair rate for the coverage provided. Insurance premiums can vary based on the extent of coverage, the insurer, and other factors, so it’s important to look at what you’re getting for your monthly or annual payment. When deciding, consider the balance between cost and benefit; the cheapest policy may not provide the thorough coverage you need, which could lead to more significant expenses should a claim arise. Therefore, it’s vital to find a policy that offers the best value for its price.

5. Is There a Deductible?

Find out if you’ll need to pay a deductible before the insurance kicks in. Understanding out-of-pocket costs is important for financial planning. Deductibles can significantly affect your cash flow, especially if a claim needs to be made quickly. In some cases, opting for a higher deductible might lower your premium costs, but this trade-off needs careful consideration based on your financial capability to cover that initial expense. As you review your policy options, consider both your current financial situation and potential future incidents that could require a claim.

6. How Easy is the Claim Process?

Inquire about the steps involved in filing a claim. A smooth and efficient process is crucial in the event of an incident. Insurers should be able to provide a clear outline of the claim process, including the necessary documentation and the expected timeframe for a response. Consider policies that offer streamlined digital claim filing options or dedicated customer support that can ease the burden when a claim needs to be filed. Understanding this process before you commit to a policy can prevent stress and confusion during what is already a trying time.

7. Are There Discounts Available?

Some companies offer discounts for bundling policies or installing safety features. Explore your options for potential savings. By combining different types of insurance—like liability and property insurance—you might receive a discounted overall rate. Additionally, installing advanced security measures on your property can not only protect against damage and theft but might also earn you a reduction in your insurance costs. Always ask your insurer about available discounts and actively seek ways to qualify for them as part of your negotiations.

8. Who is the Underwriter?

Research the insurance company or underwriter. A reputable company can provide peace of mind that claims will be handled fairly. Looking into customer reviews and ratings for these companies online can provide insight into their reliability and customer service. Try to find underwriters with a solid history and positive customer feedback, ensuring you are partnering with a company that’s trustworthiness is equal to the quality of service they offer. This research helps establish a partnership based on trust and reassurance.

9. How Long is the Policy Term?

Understand the duration of your coverage. Make sure it aligns with your needs or any specific project timelines you have in mind. Some projects may have extended timelines, making it essential that your insurance policy can cover the entire duration without requiring renewal. Check if the policy length is adaptable or if there are options to extend the coverage without significant cost increases. Evaluating the policy term allows for efficient planning and helps prevent gaps in coverage.

10. Are There Policy Renewal Terms?

Check what happens at the end of your policy term. Knowing renewal terms can prevent any lapse in coverage. Some policies automatically renew, while others may require action on your part to continue coverage. Understanding these terms ensures you remain continuously protected. Additionally, engaging with the insurer about potential changes in terms or costs upon renewal can prepare you better for any adjustments you might need to make to maintain coverage.

11. What About Customer Support?

Good customer support is invaluable. Verify that the provider offers reliable assistance when you need it. Immediate access to knowledgeable representatives can influence your overall satisfaction with your insurance provider, especially during emergencies. Evaluate their support systems, including the availability of online resources, chat support, and phone assistance, to ensure you can access help whenever necessary. This aspect of service is often overlooked but contributes significantly to the user experience.

12. Can the Policy Be Customized?

Your needs might be unique, and a one-size-fits-all policy may not be ideal. Ask about custom options to tailor the insurance to fit your specific requirements. Customization could involve adding specific coverage types to protect against unique risks associated with your installation techniques or business model. Working closely with a provider that values personalized attention can lead to more effective coverage and potentially significant long-term savings by only paying for what you genuinely need.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com