Fired Your Insurance Agency Yet? Why Thousands of New York Contractors Are Looking for a Better Insurance Partner

If you’re a contractor operating in New York, chances are you’ve experienced frustration with your insurance agency at one time or another. Whether you’re a general contractor, roofer, restoration contractor, interior demolition contractor, electrician, plumber, HVAC contractor, mason, or specialty trade contractor, your insurance program is one of the most important aspects of your business. Yet every day, contractors throughout New York are becoming increasingly dissatisfied with the service they receive from their insurance agencies.

Many contractors search Google using phrases such as “best contractor insurance agency New York,” “construction insurance broker near me,” “workers compensation insurance for contractors NY,” or “commercial insurance specialist for contractors.” They’re searching because they believe there has to be a better way.

The truth is, they’re often right.

The Phone Never Gets Answered

One of the biggest complaints contractors have about their insurance agency is poor communication. Construction moves fast. When a contractor needs a certificate of insurance, additional insured endorsement, waiver of subrogation, or answers regarding a claim, they don’t have days to wait.

Unfortunately, many agencies today are understaffed, overloaded, or simply don’t prioritize customer service the way they once did. Contractors often find themselves leaving multiple voicemails, sending repeated emails, and becoming increasingly frustrated.

When you’re trying to secure a project, satisfy a general contractor’s insurance requirements, or get paid for completed work, delays can cost thousands of dollars.

Your Insurance Agency Isn’t Shopping Your Account

Perhaps the biggest misconception contractors have is believing their insurance agency markets their account every year.

The reality is that many agencies simply renew policies with the same insurance company year after year because it’s easier and requires less effort. Meanwhile, contractors continue paying increasing premiums without ever knowing if better coverage or pricing options exist.

If you’ve searched online for “contractor liability insurance New York,” “workers compensation quotes for contractors,” or “construction insurance companies near me,” you may already suspect your account isn’t being properly marketed.

A good insurance agency should constantly evaluate available markets and coverage options, not simply process renewals.

Excessive Fees Are Becoming the New Normal

Many contractors are shocked when they discover the amount of fees they’re paying in addition to their insurance premiums.

Policy fees, broker fees, service fees, installment fees, inspection fees, and administrative fees can add hundreds or even thousands of dollars annually to the cost of insurance coverage.

Contractors work too hard to have unnecessary fees quietly added to their insurance bills.

Transparency matters.

You deserve to know exactly what you’re paying for and why.

Most Agencies Don’t Truly Understand Construction Insurance

Construction insurance in New York is unlike insurance in almost any other industry.

Issues involving Labor Law 240 and 241, action-over claims, subcontractor agreements, additional insured requirements, contractual liability, workers compensation classifications, payroll limitations, and risk transfer require specialized expertise.

Unfortunately, many insurance agencies try to be everything to everyone. They insure restaurants, retail stores, office buildings, manufacturers, and contractors without ever becoming experts in any particular field.

When a claim occurs or a coverage issue arises, contractors often discover their agency lacks the specialized knowledge needed to properly protect their business.

Certificates Take Too Long

Every contractor has experienced the frustration of needing a certificate of insurance immediately and waiting days to receive it.

In today’s competitive construction market, speed matters. A delay in obtaining a certificate, additional insured endorsement, or waiver of subrogation can result in lost opportunities, delayed payments, and unhappy customers.

Contractors deserve an insurance agency that understands urgency and responds accordingly.

Workers Compensation Costs Continue to Rise

Workers compensation insurance remains one of the largest expenses facing New York contractors.

Many contractors search online for “how to lower workers compensation premiums,” “New York construction workers comp specialists,” or “best workers compensation insurance for contractors” because they believe they’re paying too much.

In many cases, they are.

Contractors need agencies that understand:

  • Workers compensation classifications
  • Experience modification factors
  • Payroll caps
  • NYCPAP credits
  • Safety group opportunities
  • Pay-as-you-go workers compensation programs
  • Professional Employer Organization (PEO) programs
  • Premium audits
  • Claims management strategies

Without specialized guidance, contractors often pay substantially more than necessary.

Contractors Want a Relationship, Not a Transaction

Perhaps the greatest frustration contractors experience is feeling like just another account number.

Construction business owners want an insurance professional who answers the phone, understands their business, explains coverages, reviews contracts, provides guidance, and helps solve problems before they become expensive claims.

They want an advisor.

They want someone who genuinely cares about their business.

Why More Contractors Are Choosing BGES Group

At BGES Group, we understand why so many contractors become unhappy with their insurance agencies because we’ve spent the last 45 years listening to those frustrations and helping contractors solve them.

BGES Group specializes in construction insurance and works with contractors throughout New York, New Jersey, and Connecticut. We understand the unique exposures contractors face and provide the personalized service that many larger agencies have abandoned.

Our areas of expertise include:

  • Contractor General Liability Insurance
  • Workers Compensation Insurance
  • Umbrella Liability Coverage
  • Business Auto Insurance
  • Builders Risk Insurance
  • Professional Employer Organization (PEO) Programs
  • Pay-As-You-Go Workers Compensation Programs
  • Payroll Services
  • New York State Disability Insurance
  • Paid Family Leave Coverage
  • Bid and Performance Bonds
  • Workers Compensation Premium Recovery Programs

Unlike many agencies where one account manager handles hundreds of clients, BGES Group believes in personalized service and building long-term relationships.

We work with multiple insurance companies and specialized construction programs to help contractors find competitive pricing and comprehensive coverage options.

If you’re unhappy with your current insurance agency because they don’t return calls, don’t market your account, charge excessive fees, don’t understand construction insurance, or simply don’t provide the level of service you deserve, we’d welcome the opportunity to help.

If you’ve recently searched for:

  • “Best contractor insurance agency New York”
  • “Construction insurance broker near me”
  • “Workers compensation insurance for contractors”
  • “Contractor liability insurance New York”
  • “Construction insurance specialist”
  • “Commercial insurance for contractors”

then perhaps it’s time to see what BGES Group can do for your business.

You work hard building New York.

You deserve an insurance agency that works just as hard for you.

Contact BGES Group Today

Gary Wallach
BGES Group
Construction Insurance Specialist with 45 Years of Experience

Phone: (914) 806-5853
Email: bgesgroup@gmail.com
Website: www.bgesgroup.com

Contact BGES Group today for a complimentary review of your current insurance program and discover why more contractors are making the switch to an agency that understands construction, values relationships, and puts customer service first.
Are You a New York Contractor Unhappy with Your Insurance Agency Because They Have Turned Into a Large Factory and Their Service is Really Lousy and Frustrates The Crap out of You?

Unfortunately, many contractors have found that the agencies they once trusted have changed dramatically.

Over the past several years, many of the largest insurance agencies serving the New York construction industry have become what many contractors describe as “factories.” Through acquisitions, mergers, and rapid growth, personal service has often taken a back seat to volume.

If you’ve experienced any of the following, you’re certainly not alone:

  • Constant turnover in customer service representatives.
  • A different account executive every time you call.
  • Account managers responsible for hundreds of contractor accounts.
  • Long wait times to receive certificates of insurance.
  • Phone calls that go directly to voicemail.
  • Emails that take days to receive a response.
  • Costly mistakes involving certificates or policy changes.
  • Unexpected service or policy fees.
  • Feeling like you’re just another account number instead of a valued client.

For a contractor working under strict deadlines, these problems can cost far more than frustration—they can cost jobs.

Construction Insurance Isn’t Something That Can Be Put on Autopilot

The New York construction insurance marketplace is one of the most challenging in the country.

General liability policies continue to evolve. Workers’ compensation classifications require careful attention. Additional insured requirements, waiver of subrogation endorsements, primary and non-contributory wording, OCIP and CCIP projects, umbrella liability, labor law exposures, and contractual insurance requirements all require experience and attention to detail.

Contractors deserve an insurance broker who understands construction—not someone reading from a script or handling hundreds of unrelated accounts.

Bigger Doesn’t Always Mean Better

Large agencies often promote their size as an advantage.

In reality, many contractors discover that larger organizations can create additional layers of bureaucracy. Instead of speaking directly with the person responsible for their account, they may deal with multiple departments, automated systems, or rotating service teams.

The result is often slower service and less accountability.

When an important certificate needs to be issued before a crew can begin work at 7:00 a.m., waiting several hours—or even until the next day—is simply unacceptable.

Personal Service Still Matters

At BGES Group, we believe contractors deserve something different.

We believe you should know the person handling your account.

We believe your phone calls should be returned.

We believe certificates should be processed quickly.

We believe your coverage should be reviewed carefully—not rushed through an assembly line.

Most importantly, we believe you deserve an insurance broker who understands your business and treats your company as if it were their own.

Experience Makes a Difference

Gary Wallach has spent more than four decades helping contractors throughout New York, New Jersey, and Connecticut navigate one of the toughest insurance markets in America.

Construction insurance isn’t a side business—it’s one of our specialties.

We understand:

  • General Liability
  • Workers’ Compensation
  • Commercial Auto
  • Umbrella and Excess Liability
  • Inland Marine
  • Builders Risk
  • Property Insurance
  • Bonds
  • Contractor-specific insurance requirements
  • Risk management strategies designed to help protect your business

Whether you’re a small contractor or a growing construction company, we work to find solutions that fit your business—not force your business into a one-size-fits-all program.

The AI Question

Artificial intelligence is changing every industry, including insurance.

Many large agencies are investing heavily in automation to reduce operating costs. While technology certainly has its place, construction insurance often requires judgment, experience, and real conversations.

When you’re dealing with a complex claim, reviewing a contract, negotiating with an insurance carrier, or trying to understand coverage, you don’t want to rely solely on automated systems or chatbots.

You want someone who knows your account and is willing to answer the phone.

Technology should enhance customer service—not replace it.

See What Other Contractors Are Saying

One of the best ways to evaluate an insurance agency is to hear directly from its clients.

Rather than relying solely on marketing promises, we invite you to read our Google reviews.

With 147 Google Reviews, contractors and business owners have shared their experiences working with BGES Group.

Many mention our responsiveness, personal attention, industry knowledge, and commitment to helping clients solve problems quickly.

We believe referrals remain the highest compliment any business can receive. Reading the experiences of other contractors is like getting a recommendation from a trusted friend.

You Deserve Excellence

You work hard every day to build homes, offices, schools, apartment buildings, and commercial properties.

You meet demanding schedules, manage employees, coordinate subcontractors, and assume significant risks.

The insurance premiums you pay each year represent a major investment in protecting everything you’ve built.

Shouldn’t the service you receive reflect that investment?

If you’re tired of feeling like just another policy number, it may be time to experience a different kind of insurance agency.

At BGES Group, we pride ourselves on delivering knowledgeable advice, responsive service, and personal attention to every contractor we serve.

If you’re unhappy with your current insurance agency—or simply want a second opinion on your insurance program—we’d welcome the opportunity to earn your business.

Contact Gary Wallach today:

BGES Group

📞 914-806-5853

📧 bgesgroup@gmail.com

🌐 www.bgesgroup.com

Discover why so many contractors throughout the Tri-State area trust BGES Group for their insurance needs. When you deserve exceptional service, experience matters.

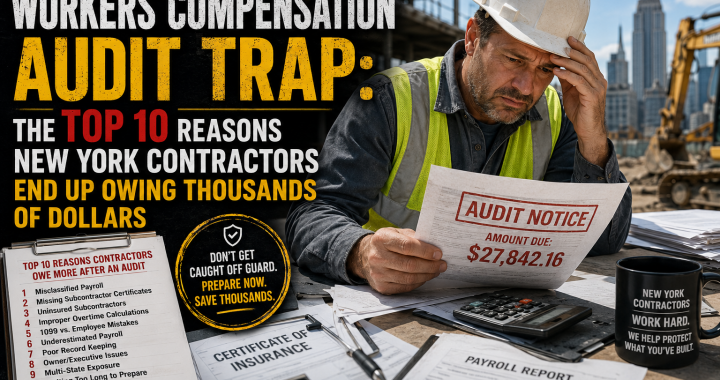
The Workers Compensation Audit Trap: The Top 10 Reasons New York Contractors End Up Owing Thousands of Dollars

For many New York contractors, receiving a workers compensation audit notice can produce more anxiety than almost any other business document. A policy that began with an estimated premium of $15,000 can suddenly generate an additional bill for $25,000, $50,000, or even more after the annual audit is completed. Unfortunately, many contractors don’t discover their mistakes until the audit is finalized and payment is due.

Workers compensation audits are a normal part of doing business in New York construction, but they don’t have to become a financial disaster. Understanding the most common audit pitfalls can help contractors avoid costly surprises and better manage their insurance costs.

Below are the top ten reasons New York contractors find themselves owing thousands of dollars after their workers compensation audit.

1. Misclassifying Employee Payroll

One of the most common and expensive mistakes contractors make is placing employees in the wrong workers compensation classification codes.

For example, a contractor may classify an employee as a clerical worker when the employee regularly visits job sites. Others may improperly classify workers performing high-hazard activities under lower-rated classifications. During an audit, insurance companies review payroll records, job descriptions, and business operations to ensure classifications are accurate.

Even an honest mistake can result in substantial additional premium charges.

2. Failing to Obtain Certificates of Insurance From Subcontractors

Many contractors assume that because a subcontractor says they have insurance, everything is covered. Unfortunately, auditors require proof.

If a contractor cannot provide valid certificates of insurance and supporting documentation for subcontractors, the insurance company may include those subcontractor payments as payroll exposure. This can dramatically increase the audited premium.

Keeping current certificates of insurance on file throughout the policy period is one of the most important risk management practices any contractor can implement.

3. Using Uninsured or Underinsured Subcontractors

In New York, hiring uninsured subcontractors can create a financial nightmare. If the subcontractor lacks proper workers compensation coverage, the hiring contractor can become responsible for the exposure.

Auditors routinely review subcontractor payments, contracts, invoices, and certificates. Missing or inadequate coverage documentation can result in thousands of dollars in unexpected premium charges.

4. Improper Treatment of Overtime Payroll

Many contractors don’t realize that workers compensation rules generally allow the premium portion of overtime wages to be excluded from the audit calculation.

For example, if an employee earns time-and-a-half pay, the premium portion of that overtime may not be subject to workers compensation premium. However, contractors must maintain detailed payroll records separating regular and overtime wages.

Without proper documentation, auditors may include all overtime compensation, increasing the premium unnecessarily.

5. Paying Employees as Independent Contractors

Simply issuing a 1099 form does not automatically make someone an independent contractor.

New York applies strict standards when determining worker classification. If an auditor concludes that a worker classified as an independent contractor should actually be treated as an employee, the payroll associated with that worker may be added to the audit.

This issue frequently affects construction trades, trucking operations, and specialty subcontractors.

6. Underestimating Payroll at Policy Inception

Workers compensation policies are based on estimated annual payroll. If business grows significantly during the policy year, contractors can experience major audit adjustments.

While growth is usually a positive development, rapidly increasing payroll without notifying your insurance broker can create a substantial audit bill at the end of the policy period.

Regular communication with your insurance advisor can help prevent unpleasant surprises.

7. Poor Record Keeping

Incomplete payroll records are one of the biggest reasons contractors lose audit disputes.

Auditors typically review:

  • Payroll journals
  • Tax returns
  • Quarterly payroll reports
  • General ledgers
  • Cash disbursement journals
  • Subcontractor records
  • Certificates of insurance
  • Federal tax filings

When records are incomplete or inconsistent, auditors often apply the most conservative interpretation, which usually results in higher premiums.

8. Failing to Track Owners and Executive Exclusions Properly

New York workers compensation rules regarding business owners can be complicated.

Depending on the business structure, owners may or may not be included in workers compensation calculations. Improper handling of owner payroll, executive exclusions, or partnership structures can lead to costly audit adjustments.

Contractors should periodically review ownership status and exclusion forms with their insurance professional.

9. Misunderstanding Multi-State Operations

Many New York contractors perform work in neighboring states such as New Jersey and Connecticut. Different states have different workers compensation rules, classifications, and reporting requirements.

Failure to properly report out-of-state operations can create significant audit problems and potentially uninsured exposures.

Contractors performing work across state lines should ensure their policies are properly structured before beginning operations.

10. Waiting Until the Audit Notice Arrives

Perhaps the biggest mistake contractors make is preparing for the audit only after receiving the audit appointment letter.

Successful contractors prepare throughout the entire policy year. They maintain organized payroll records, collect subcontractor certificates immediately, monitor payroll changes, and consult their insurance advisor regularly.

Workers compensation audits should never be viewed as a once-a-year event. Instead, they should be considered an ongoing business management process.

Three Common Google Searches Contractors Use When Looking for Workers Compensation Help

When contractors begin experiencing workers compensation problems, they often search online using phrases such as:

  • “How to reduce workers compensation costs for New York contractors”
  • “Workers compensation audit help near me”
  • “Best insurance broker for New York construction companies”

Understanding these issues before the audit occurs can save contractors thousands—or even tens of thousands—of dollars.

How BGES Group Can Help

BGES Group is a boutique insurance brokerage specializing in New York construction insurance and workers compensation programs. With more than 45 years of experience, we understand the unique challenges contractors face in New York’s demanding insurance environment.

We assist contractors with:

  • Workers compensation program design
  • Workers compensation audit preparation and review
  • General liability insurance
  • Umbrella liability coverage
  • Pay-as-you-go workers compensation plans
  • Construction risk management
  • Subcontractor insurance compliance
  • Builders risk insurance
  • Commercial auto insurance
  • Surety and bonding solutions

Unlike many large agencies where account managers may handle hundreds of accounts, BGES Group provides personalized service and direct access to experienced professionals who understand New York construction insurance.

If you’re concerned about an upcoming workers compensation audit, rising insurance costs, or gaps in your coverage program, we can help.

Contact BGES Group

Gary Wallach
Phone: (914) 806-5853
Email: bgesgroup@gmail.com
Website: BGES Group⁠

Financial and Informational Disclaimer: This article is intended solely for general informational and educational purposes and should not be construed as legal, tax, accounting, or insurance advice. Workers compensation laws, classifications, and audit procedures vary based on individual circumstances and regulatory requirements. Contractors should consult qualified legal, accounting, and insurance professionals regarding their specific situations before making business or insurance decisions.

The Fine Print That Can Bankrupt a Contractor: Hidden General Liability Exclusions Every New York Contractor Must Understand

Most New York contractors believe that once they purchase a commercial general liability (CGL) policy, they are protected against lawsuits and property damage claims. Unfortunately, that assumption can prove devastatingly wrong.

In today’s insurance marketplace, especially in New York construction, many policies contain exclusions and limitations that can significantly reduce or even eliminate coverage for some of the most common construction-related claims. Contractors often discover these hidden exclusions only after a claim occurs—when it is too late to purchase additional protection.

With New York’s aggressive litigation environment, complex Labor Law exposures, and increasingly restrictive underwriting standards, understanding what your general liability policy does not cover may be just as important as understanding what it does cover.

Here are some of the most important hidden general liability exclusions that every New York contractor should know about.

1. Action-Over Exclusions

Perhaps no exclusion creates more concern for New York contractors than the action-over exclusion.

New York Labor Law Sections 240 and 241 allow injured employees of subcontractors to pursue claims against general contractors and property owners under certain circumstances. An action-over exclusion can eliminate coverage for these claims, leaving contractors exposed to potentially catastrophic lawsuits.

Many contractors don’t realize their policy contains this exclusion until they receive a denial letter after a serious workplace injury.

If you perform construction work in New York, understanding your policy’s action-over language is critical.

2. Height Limitation Exclusions

Many general liability policies issued to contractors now contain strict height restrictions.

Examples include exclusions for work performed:

  • Above two stories
  • Above three stories
  • Above fifteen feet
  • Above thirty feet

This presents a serious problem because many contractors regularly perform work that exceeds these limits without realizing they may be operating outside their coverage parameters.

Roofers, painters, masons, restoration contractors, window installers, and siding contractors are particularly vulnerable to height restriction exclusions.

3. Residential Construction Exclusions

Numerous insurance carriers restrict or exclude work performed on residential projects.

A contractor may believe they have coverage for all operations only to discover their policy excludes:

  • Single-family residences
  • Multi-family housing
  • Condominium projects
  • Apartment buildings
  • Mixed-use residential properties

Given the large amount of residential construction activity in New York, failing to identify these exclusions can create substantial uninsured exposure.

4. Subcontractor Warranty Endorsements

Many policies contain subcontractor warranty provisions that require contractors to obtain specific documentation before coverage applies.

These requirements often include:

  • Written contracts
  • Hold harmless agreements
  • Additional insured endorsements
  • Certificates of insurance
  • Primary and non-contributory wording
  • Waivers of subrogation

Failure to obtain even one required document may allow an insurer to deny coverage for a claim involving a subcontractor.

Many contractors mistakenly believe that simply receiving a certificate of insurance satisfies all policy requirements.

5. Exterior Insulation and Finish System (EIFS) Exclusions

EIFS claims have historically produced significant losses for insurance companies. As a result, many contractors’ policies specifically exclude work involving EIFS materials.

Contractors performing stucco, synthetic stucco, waterproofing, or exterior finishing operations should carefully review their policies to determine whether these exclusions apply.

Even contractors performing repair work on EIFS systems may discover they have little or no coverage.

6. Classification Limitation Endorsements

Insurance companies frequently issue policies restricting coverage only to the classifications specifically listed on the declarations page.

For example, a contractor insured as a carpenter who performs roofing, demolition, excavation, or concrete work may discover that these operations are excluded because they were never properly reported.

As businesses evolve and expand, coverage gaps can develop if operations are not updated regularly.

7. Designated Ongoing Operations Exclusions

Some policies specifically exclude certain operations, equipment, or activities.

Examples include exclusions for:

  • Demolition
  • Excavation
  • Structural work
  • Roofing
  • Waterproofing
  • Environmental work
  • Lead or asbestos exposures
  • Fire suppression systems

Contractors should review these endorsements carefully to ensure their actual operations match what the policy covers.

8. Professional Liability Exclusions

General liability insurance typically does not cover professional services.

Contractors who provide:

  • Design services
  • Engineering recommendations
  • Construction management
  • Project consulting
  • Building specifications

may require separate professional liability coverage.

A contractor can be sued for professional negligence even if no physical property damage occurs.

9. Employee Injury Exclusions

General liability policies generally exclude bodily injury claims brought by employees.

Contractors sometimes mistakenly assume that if workers compensation denies a claim, their general liability policy will respond. In most cases, employee injury exclusions prevent this.

This makes maintaining proper workers compensation coverage absolutely essential.

10. Contractual Liability Limitations

Many construction projects require contractors to sign broad indemnification agreements.

However, not all contractual obligations assumed by contractors are covered under general liability policies.

Some contractual promises may extend beyond what the insurance policy actually covers, potentially creating significant uninsured liabilities.

Contractors should always have construction contracts reviewed carefully before signing.

Why These Exclusions Matter More in New York

New York remains one of the most challenging insurance environments in the country for contractors. High litigation costs, Labor Law exposures, rising jury verdicts, and increasingly restrictive insurance markets have forced many carriers to limit coverage through exclusions and endorsements.

A policy with a low premium may ultimately become the most expensive insurance purchase a contractor ever makes if a claim occurs and coverage is denied.

The difference between a properly structured policy and an improperly structured policy can literally determine whether a contractor survives a major lawsuit.

Three Common Google Searches Contractors Use When Looking for General Liability Help

Contractors searching for answers regarding coverage problems frequently use search phrases such as:

  • “Best general liability insurance for New York contractors”
  • “What does contractor general liability insurance cover?”
  • “Insurance broker specializing in New York construction insurance”

If you’re searching these phrases, it’s probably time to have your coverage reviewed by a professional who understands New York construction risks.

How BGES Group Can Help

BGES Group is a boutique insurance brokerage specializing in New York construction insurance. For more than 45 years, we have helped contractors navigate the increasingly complex insurance marketplace while identifying potential coverage gaps before they become financial disasters.

We specialize in:

  • Commercial General Liability Insurance
  • Workers Compensation Insurance
  • Umbrella and Excess Liability Coverage
  • Builders Risk Insurance
  • Contractor Package Policies
  • Commercial Auto Insurance
  • Surety and Bonding Programs
  • Subcontractor Risk Management
  • Contract Review Assistance
  • Construction Risk Analysis

Unlike many large insurance agencies where accounts may be serviced by multiple people, BGES Group provides personalized service with direct access to experienced construction insurance professionals who understand the unique challenges facing New York contractors.

Our goal is simple: help contractors identify coverage gaps, reduce risk, and protect the businesses they have worked so hard to build.

Contact BGES Group

Gary Wallach
BGES Group

Phone: (914) 806-5853
Email: bgesgroup@gmail.com
Website: BGES Group⁠

Informational Disclaimer: This article is provided for educational and informational purposes only and does not constitute legal, insurance, tax, or professional advice. Insurance policies vary significantly by carrier, endorsement, and jurisdiction. Coverage determinations depend upon the specific terms, conditions, exclusions, and endorsements contained within each individual policy. Contractors should consult qualified legal counsel and licensed insurance professionals regarding their particular circumstances and insurance needs before making coverage decisions.

The Contractor’s Insurance Survival Guide: 7 Questions Every New York Contractor Should Ask Before Renewing Coverage

For contractors working in New York, insurance renewal is not just an administrative task—it is a critical financial checkpoint that can determine whether a business is properly protected or dangerously exposed. In a state where construction liability laws are among the most aggressive in the country, especially under New York Labor Law §§240 and 241, the difference between a well-structured insurance program and a poorly designed one can mean millions of dollars in uncovered losses.

Yet many contractors approach renewal with a single focus: premium. If the price is close to last year’s, or slightly lower, the policy is often renewed without deeper review. That approach may work in simpler industries, but in New York construction, it is one of the most dangerous mistakes a contractor can make.

A smarter approach is to ask the right questions before signing on the dotted line. Below are seven essential questions every New York contractor should ask before renewing general liability and related insurance coverage.

1. Does My Policy Truly Cover New York Labor Law Claims?

New York Labor Law §§240 and 241—often referred to as the “Scaffold Law” and its companion statute—create strict liability exposure for contractors and property owners involving elevation-related injuries and construction site safety violations.

In practical terms, this means a contractor can be held fully responsible for a serious injury even if they did not directly cause it or if the worker contributed to the accident.

Many contractors assume their general liability policy automatically covers these exposures. Unfortunately, some policies contain:

  • Labor Law exclusions
  • Sub-limits for construction-related injury claims
  • Restrictive endorsements that narrow protection

If Labor Law coverage is missing or limited, a single fall from a ladder or scaffold can result in catastrophic uninsured losses.

2. Are There Any Exclusions That Could Eliminate Coverage When I Need It Most?

Insurance policies are defined not only by what they cover—but by what they exclude. In New York contractor policies, exclusions are often where the real risk lies.

Common exclusions include:

  • Height restrictions (e.g., no work above 10–15 feet)
  • Roofing exclusions
  • Residential construction exclusions
  • Employee injury or cross-employee exclusions
  • Action-over exclusions
  • Designated operations exclusions

The danger is not always obvious during renewal. A policy may appear identical year to year, but subtle endorsement changes can dramatically reduce protection.

One overlooked exclusion can turn a major claim into a total financial loss.

3. Do I Have Proper Additional Insured Coverage for All Contracts?

In New York construction, nearly every contract requires subcontractors to provide additional insured status to:

  • Property owners
  • General contractors
  • Construction managers

However, not all additional insured endorsements are equal.

Contract requirements often specify:

  • CG 20 10 (ongoing operations)
  • CG 20 37 (completed operations)
  • Primary and non-contributory wording
  • Coverage triggered by written contract language

If the policy does not match contractual requirements exactly, the contractor may technically be in breach of contract—even if a certificate was issued.

Worse, when a claim occurs, the insurance company may deny defense or indemnity for the upstream parties, leaving the contractor exposed to lawsuits from both sides.

4. Is My Umbrella or Excess Liability Coverage Enough for a Serious Loss?

Primary general liability policies typically provide $1 million per occurrence limits. In today’s New York construction environment, that amount is often not enough.

Serious construction accidents can easily result in:

  • Multi-million-dollar settlements
  • Permanent disability claims
  • Lifetime medical care obligations
  • Pain and suffering awards

It is not unusual for Labor Law claims to exceed $5 million, $10 million, or more.

Without sufficient umbrella or excess liability coverage, contractors may find themselves personally exposed after primary limits are exhausted.

Renewal time is the moment to evaluate whether your excess protection actually matches your risk—not just your contract minimums.

5. Are My Subcontractors Properly Insured and Verified?

One of the most common sources of uninsured liability comes from subcontractor risk.

Contractors often assume that subcontractors carry proper insurance. However, problems arise when subcontractors:

  • Provide expired certificates
  • Lack proper endorsements
  • Do not carry sufficient limits
  • Fail to name the contractor as additional insured

If a subcontractor causes an accident and their insurance is inadequate or invalid, liability may flow back to the hiring contractor.

A strong insurance program includes a system for:

  • Certificate tracking
  • Endorsement verification
  • Ongoing compliance review
  • Contract alignment

Without this, contractors may unknowingly absorb risk that was supposed to be transferred.

6. Are My Completed Operations Covered Properly?

Completed operations coverage is one of the most overlooked but critical components of a contractor’s insurance program.

This coverage protects against claims that arise after a project is finished, including:

  • Structural failures
  • Water damage
  • Construction defects
  • Falling materials
  • Electrical or mechanical issues

Many contractors assume they are no longer exposed once the job is completed. In reality, claims can arise months or even years later.

Even more important is whether completed operations coverage extends to additional insureds. Without it, owners and general contractors may be left exposed long after the project is finished.

7. Is My Policy Structured for New York Construction Risk—or Just a Generic Form?

Not all general liability policies are designed for New York construction.

Some policies are written for broad national use and may not properly account for:

  • New York Labor Law exposures
  • Action-over claims
  • Contractual indemnification requirements
  • Multi-party litigation scenarios
  • High-severity injury environments

A generic policy may meet minimum requirements on paper but fail under real-world New York construction conditions.

The key question contractors must ask is:

Is my insurance program designed for New York construction reality—or just insurance compliance?

There is a major difference between the two.

Final Thought: Renewal Is a Risk Audit, Not a Formality

Insurance renewal should be treated as a full risk audit of your business. It is the one time each year when contractors have the opportunity to correct gaps, strengthen protection, and ensure alignment with contracts and exposures.

Unfortunately, many contractors treat renewal as routine paperwork.

In New York construction, that mindset can be costly.

The right insurance program is not just about compliance—it is about survival.

About BGES Group

At BGES Group, we specialize in helping New York contractors navigate the complex and high-risk world of construction insurance.

For more than 45 years, owner Gary Wallach has worked directly with contractors throughout New York, New Jersey, and Connecticut, helping them build insurance programs designed to withstand the realities of construction litigation and Labor Law exposure.

We specialize in:

  • General Liability Insurance
  • Workers Compensation Insurance
  • Excess and Umbrella Liability
  • New York Labor Law Risk Analysis
  • Additional Insured Compliance
  • Contract Review and Risk Transfer
  • Contractor Insurance Programs
  • Builders Risk Insurance
  • Commercial Auto Insurance
  • Subcontractor Insurance Verification

As a boutique agency, BGES Group provides hands-on service, fast certificate issuance, and direct access to experienced professionals who understand New York construction risk at a detailed level. We work closely with contractors to identify coverage gaps before they become costly problems.

If you are a contractor, subcontractor, developer, or property owner, we welcome the opportunity to review your current insurance program and help ensure your business is properly protected.

Gary Wallach
BGES Group
Phone: 914-806-5853
Email: bgesgroup@gmail.com
Website: www.bgesgroup.com

Important Financial and Informational Disclaimer

This article is provided for informational and educational purposes only and does not constitute legal, insurance, financial, or risk management advice. Insurance coverage terms, exclusions, endorsements, policy forms, underwriting requirements, and legal exposures vary significantly based on individual circumstances and carrier guidelines. Readers should consult licensed insurance professionals and qualified legal counsel regarding their specific situation. No guarantee of coverage, claim outcome, or future results is expressed or implied.

The New York Construction Lawsuit Machine: How One Workplace Injury Can Trigger Multiple Insurance Policies

For contractors operating in New York, every construction project carries risk. Most contractors understand the obvious dangers: falls, equipment accidents, property damage, and workplace injuries. What many contractors, property owners, and even some insurance professionals fail to appreciate is how a single workplace accident can trigger a cascade of lawsuits, insurance claims, and legal obligations involving numerous parties and multiple insurance policies.

In New York’s unique legal environment, one construction injury can quickly evolve into a complex web of litigation involving workers compensation carriers, general liability insurers, umbrella carriers, property owners, general contractors, subcontractors, and excess insurance companies. Understanding how this process works is critical for protecting your business, your assets, and your future.

One Accident. Multiple Lawsuits.

Imagine the following scenario.

A masonry subcontractor’s employee is working on scaffolding at a commercial construction project in New York. While performing routine work, the scaffold shifts, causing the worker to fall two stories and suffer severe injuries.

What happens next?

Most contractors assume the employee files a workers compensation claim and the matter ends there.

In New York, that’s often only the beginning.

The injured worker immediately files a workers compensation claim through his employer’s workers compensation insurance carrier. Medical bills begin accumulating. Wage replacement benefits commence.

Then the injured worker’s attorney files lawsuits against:

  • The property owner
  • The general contractor
  • The construction manager
  • Other contractors on the project
  • Equipment manufacturers, if applicable

What initially appeared to be a workers compensation claim has now become a major liability lawsuit.

Why New York Labor Laws Change Everything

New York Labor Law Sections 240 and 241 create some of the most challenging liability exposures in the country.

Labor Law 240, often called the “Scaffold Law,” imposes extraordinary liability on owners and contractors for gravity-related accidents, including falls from heights and injuries caused by falling objects.

Labor Law 241 imposes additional obligations related to construction site safety and compliance with New York Industrial Code regulations.

As a result, injured workers frequently sue virtually every entity associated with a construction project.

The damages sought often include:

  • Medical expenses
  • Lost wages
  • Future lost earnings
  • Pain and suffering
  • Permanent disability
  • Loss of quality of life
  • Future medical care costs

These claims can easily reach millions of dollars.

Workers Compensation: The First Layer

The first insurance policy typically triggered is workers compensation insurance.

Workers compensation provides:

  • Medical treatment
  • Wage replacement
  • Rehabilitation expenses
  • Disability benefits
  • Death benefits, if applicable

Many contractors mistakenly believe that workers compensation is the exclusive remedy.

While workers generally cannot sue their direct employer, they often retain the right to sue numerous third parties involved in the construction project.

This distinction is what creates the “construction lawsuit machine” that New York contractors face every day.

The General Liability Policy Gets Pulled In

Once the injured worker files suit against the owner and general contractor, those defendants frequently seek defense and indemnification from the employer-subcontractor.

This process triggers the subcontractor’s commercial general liability policy.

The general liability carrier now faces potential exposure for:

  • Legal defense costs
  • Settlement negotiations
  • Trial expenses
  • Indemnification obligations
  • Additional insured obligations

The costs associated with defending a serious construction accident can reach hundreds of thousands of dollars before a case ever reaches trial.

Additional Insured Coverage Becomes Critical

Most construction contracts require subcontractors to provide additional insured status to upstream parties.

As a result, the subcontractor’s insurance company may also become responsible for defending:

  • Property owners
  • General contractors
  • Construction managers
  • Developers

One accident can therefore require a single insurance company to provide legal representation and coverage to multiple defendants simultaneously.

This is why additional insured endorsements are among the most important risk transfer tools in the construction industry.

Without proper additional insured coverage, contractual disputes and uninsured exposures can quickly emerge.

The Action-Over Claim

One of the most feared scenarios in New York construction is the action-over claim.

Here’s how it develops:

  • The employee receives workers compensation benefits.
  • The employee sues the owner and general contractor.
  • The owner and general contractor file claims against the employer-subcontractor.
  • The subcontractor’s liability insurance becomes involved.

What started as a workers compensation claim has transformed into a complex liability lawsuit involving multiple parties and multiple insurance carriers.

For contractors with inadequate insurance coverage, action-over claims can be financially devastating.

Umbrella and Excess Liability Coverage

Serious construction accidents rarely remain within the limits of primary insurance policies.

Consider the following example:

  • General liability limit: $1 million
  • Settlement demand: $7 million

Where does the additional $6 million come from?

This is where umbrella and excess liability policies become essential.

Excess liability coverage provides additional layers of protection once primary limits have been exhausted.

In New York construction, catastrophic injury claims involving paralysis, traumatic brain injuries, amputations, or wrongful death can result in settlements and verdicts exceeding $10 million, $20 million, or even higher.

Contractors who fail to purchase adequate umbrella coverage often discover the true value of insurance only after disaster strikes.

Contractual Indemnification

Construction contracts typically contain indemnification provisions requiring one party to protect another from liability.

These provisions often trigger additional disputes involving:

  • Contract interpretation
  • Insurance obligations
  • Defense responsibilities
  • Risk transfer provisions
  • Additional insured status

Multiple law firms, insurance adjusters, and experts may spend years litigating who ultimately bears responsibility for a single accident.

The legal expenses alone can be enormous.

The Hidden Cost of Cheap Insurance

Many contractors purchase insurance based primarily on price.

Unfortunately, low-cost policies often contain restrictions such as:

  • Labor Law exclusions
  • Height limitations
  • Action-over exclusions
  • Employee injury exclusions
  • Residential construction exclusions
  • Restrictive additional insured endorsements

The contractor believes they have purchased protection.

The insurance company believes it has limited its exposure.

The disagreement often becomes apparent only after a major claim occurs.

By then, the contractor may face millions of dollars in uninsured liability.

Protecting Your Construction Business

The best defense against New York’s construction lawsuit environment involves several critical components:

  • Strong workplace safety practices
  • Proper subcontractor agreements
  • Comprehensive insurance coverage
  • Adequate umbrella liability limits
  • Effective contractual risk transfer
  • Proper additional insured endorsements
  • Experienced legal and insurance advisors

Insurance should never be viewed simply as an expense.

It is a financial protection system designed to preserve the business you have spent years building.

Experience Matters

New York construction insurance is among the most specialized and complex areas of commercial insurance.

A contractor’s insurance program should not simply satisfy a contract requirement.

It should be designed to survive the realities of New York construction litigation.

The difference between surviving a catastrophic claim and losing everything often comes down to the experience and expertise of the professionals designing your insurance program.

About BGES Group

At BGES Group, we specialize in helping contractors navigate the challenging world of New York construction insurance.

For more than 45 years, owner Gary Wallach has worked with contractors throughout New York, New Jersey, and Connecticut, helping businesses secure comprehensive protection while controlling insurance costs and managing risk.

Our areas of expertise include:

  • General Liability Insurance
  • Workers Compensation Insurance
  • Excess and Umbrella Liability
  • New York Labor Law Exposures
  • Additional Insured Requirements
  • Contractual Risk Transfer
  • Contractor Package Policies
  • Commercial Auto Insurance
  • Builder’s Risk Insurance
  • Contract Review Assistance
  • Specialized New York Contractor Insurance Programs

As a boutique agency, BGES Group provides personalized service that many larger agencies cannot match. We understand New York construction risks, issue certificates quickly, respond rapidly to client needs, and work directly with contractors to identify potential gaps in coverage before losses occur.

If you are a contractor, subcontractor, property owner, or developer operating in New York, we welcome the opportunity to review your current insurance program and help ensure your business is properly protected.

Gary Wallach
BGES Group

Phone: 914-806-5853
Email: bgesgroup@gmail.com
Website: www.bgesgroup.com

Important Financial and Informational Disclaimer

This article is provided solely for informational and educational purposes and does not constitute legal, insurance, financial, tax, or risk management advice. Insurance coverages, policy forms, endorsements, contractual obligations, and legal liabilities vary substantially depending upon the facts and circumstances involved. Readers should consult qualified legal counsel and licensed insurance professionals regarding their specific situations. Coverage availability, policy provisions, underwriting requirements, and pricing vary among insurance carriers. No representation, warranty, or guarantee of coverage, legal outcome, or future results is expressed or implied.

The Million-Dollar Risk: Why Every New York Contractor Must Understand Labor Law 240 and 241

If you are a contractor, subcontractor, property owner, or developer operating in New York, there is one legal reality you cannot afford to ignore: New York Labor Law §§240 and 241. These laws have created some of the largest construction injury verdicts and insurance claims in the country and continue to shape virtually every aspect of construction liability insurance in New York. Understanding these laws isn’t simply good business practice—it can mean the difference between staying in business and facing a devastating financial loss. (Justia⁠)

The Law That Makes New York Different

New York Labor Law §240, commonly known as the “Scaffold Law,” was originally enacted in 1885 to protect construction workers from gravity-related injuries. Today, it remains unique because New York is the only state in the nation that imposes what is commonly referred to as “absolute” or “strict” liability on property owners and contractors for many elevation-related accidents. (LegalClarity⁠)

What does this mean in practical terms?

If a worker falls from a ladder, scaffold, roof, lift, or elevated platform—or if a worker is struck by a falling object—owners and contractors may be held fully responsible, even if they exercised reasonable care and even if the worker contributed to the accident. Unlike most states, comparative negligence often provides little or no protection in these cases. (LegalClarity⁠)

For contractors, this creates one of the most challenging liability environments anywhere in the United States.

What Exactly Does Labor Law 240 Cover?

Labor Law 240 applies to workers engaged in:

  • Construction
  • Demolition
  • Repair work
  • Alteration
  • Painting
  • Cleaning
  • Pointing of buildings and structures

The law requires owners and contractors to provide proper safety devices, including:

  • Scaffolds
  • Ladders
  • Hoists
  • Safety harnesses
  • Ropes
  • Braces
  • Slings
  • Fall protection systems
  • Other protective equipment necessary to protect workers from gravity-related hazards (Justia⁠)

Common claims that trigger Labor Law 240 include:

  • Falls from ladders
  • Falls from scaffolds
  • Falls from roofs
  • Falls into excavations
  • Injuries caused by falling tools
  • Injuries caused by falling construction materials
  • Scaffold collapses
  • Lift and hoist accidents (BGES Insurance⁠)

Labor Law 241: The Hidden Companion Risk

While Labor Law 240 receives most of the attention, Labor Law 241 presents another substantial exposure for contractors and property owners.

Labor Law 241 requires owners and contractors to provide reasonable and adequate protection and safety for workers on construction sites and references hundreds of specific provisions contained within New York’s Industrial Code. Violations of these regulations can result in substantial liability claims, even when no Labor Law 240 claim exists. (Reddit⁠)

Examples include:

  • Unsafe excavation practices
  • Improper housekeeping
  • Defective barriers
  • Inadequate lighting
  • Unsafe equipment operation
  • Failure to comply with specific construction safety regulations

A single construction accident can trigger claims under Labor Law 200, Labor Law 240, Labor Law 241, OSHA regulations, workers compensation laws, and contractual indemnification provisions simultaneously.

Why Insurance Costs Are So High in New York

Many contractors wonder why their general liability premiums are substantially higher than contractors operating elsewhere in the country.

The answer is simple: Labor Law claims produce some of the most severe losses in the insurance industry. Because owners and contractors can face full liability for catastrophic injuries, insurers must price their policies accordingly. (Times Union⁠)

A serious Labor Law claim can involve:

  • Multiple surgeries
  • Permanent disability
  • Lifetime medical care
  • Lost wages
  • Pain and suffering awards
  • Multi-million-dollar settlements or verdicts

As a result, insurance carriers frequently impose:

  • Height restrictions
  • Labor Law exclusions
  • Residential construction exclusions
  • Employee injury exclusions
  • Action-over exclusions
  • Subcontractor limitations

Many contractors do not discover these restrictions until after a claim occurs.

The “Action Over” Problem

One of the most misunderstood risks facing New York contractors is the “action over” claim.

Here’s how it works:

A worker is injured and receives workers compensation benefits. The worker then sues the property owner and general contractor under Labor Law 240 or 241. The property owner and general contractor subsequently file a lawsuit against the employer-contractor seeking indemnification.

Suddenly, a workers compensation claim becomes a multi-million-dollar liability lawsuit involving multiple parties and insurance policies. (YouTube⁠)

Without the proper insurance structure, this scenario can threaten the financial survival of a construction company.

Why Buying Cheap Insurance Can Be Dangerous

In today’s competitive market, contractors are understandably focused on price. However, selecting coverage based solely on premium can create enormous problems.

Questions every New York contractor should ask include:

  • Does my policy cover Labor Law claims?
  • Are there employee injury exclusions?
  • Are there action-over exclusions?
  • What height limitations apply?
  • Is residential work excluded?
  • Do I have sufficient umbrella coverage?
  • Are my subcontractors properly insured?
  • Do my additional insured endorsements satisfy contract requirements?

The cheapest policy is often the most expensive mistake.

Protecting Your Business

The best defense against Labor Law exposure is a combination of:

  • Strong safety practices
  • Proper contracts
  • Effective risk transfer
  • Experienced legal counsel
  • Comprehensive insurance coverage
  • Knowledgeable insurance representation

Contractors operating in New York need brokers who understand the complex interaction between Labor Law liability, workers compensation, contractual indemnification, additional insured requirements, and excess liability coverage.

About BGES Group

At BGES Group, we specialize in helping New York contractors navigate one of the most difficult insurance environments in America.

For more than 45 years, owner Gary Wallach has worked with contractors throughout New York, New Jersey, and Connecticut, helping construction businesses secure comprehensive protection while controlling insurance costs.

We specialize in:

  • General Liability Insurance
  • Workers Compensation Insurance
  • Excess and Umbrella Liability
  • Labor Law Coverage Analysis
  • Contractor Package Policies
  • Commercial Auto Insurance
  • Builders Risk Insurance
  • Additional Insured Requirements
  • Risk Transfer and Contract Review Assistance
  • Specialized Programs for New York Contractors

As a boutique agency, we provide personalized service that larger agencies often cannot match. Certificates are frequently issued within minutes, and when problems arise, you’ll speak directly with experienced professionals who understand New York construction insurance.

If you are a contractor, subcontractor, developer, or property owner operating in New York, we would welcome the opportunity to review your current insurance program and identify potential gaps in coverage.

Gary Wallach
BGES Group
Phone: 914-806-5853
Email: bgesgroup@gmail.com
Website: www.bgesgroup.com

Important Financial and Informational Disclaimer

This article is provided for general informational and educational purposes only and does not constitute legal, insurance, financial, or risk management advice. Labor Law exposures and insurance coverage vary significantly depending upon the facts, contracts, policy forms, endorsements, and applicable law. Readers should consult qualified legal counsel and licensed insurance professionals regarding their specific circumstances. Coverage availability, terms, conditions, exclusions, and pricing vary by insurer and jurisdiction. No guarantee of coverage or future results is expressed or implied.

Additional Insured Endorsements: The Insurance Requirement That Can Make or Break a New York Construction Contract

In the world of New York construction, contractors spend enormous amounts of time focusing on project costs, labor, materials, scheduling, and safety. Yet one of the most important factors determining whether a contractor survives a lawsuit or faces financial disaster is often buried deep within the insurance policy itself: the additional insured endorsement.

To many contractors, the phrase “additional insured” sounds like just another piece of paperwork required before work begins. A certificate gets issued, a contract gets signed, and everyone moves on.

Unfortunately, this misunderstanding has contributed to countless insurance disputes, denied claims, breach of contract allegations, and multi-million-dollar lawsuits.

In New York’s complex construction environment, additional insured endorsements are not simply administrative requirements—they are one of the most important risk transfer mechanisms available to contractors, property owners, and developers.

What Is an Additional Insured?

An additional insured is a person or organization added to another party’s insurance policy for liability protection arising out of the named insured’s operations.

In construction, this typically means:

  • A subcontractor adds the general contractor as an additional insured.
  • The subcontractor also adds the property owner.
  • The general contractor may add the project owner.
  • Multiple tiers of contractors may provide additional insured coverage to one another.

The purpose is simple: transfer risk away from the owner and upstream contractors to the party performing the work.

Without proper additional insured protection, every construction accident can become a financial battle involving multiple parties and multiple insurance companies.

Why Additional Insured Coverage Matters So Much in New York

No state presents greater liability challenges for construction businesses than New York.

New York Labor Laws Sections 240 and 241 create significant exposures for property owners and contractors. When an injury occurs, plaintiffs’ attorneys frequently sue everyone involved in the project, including:

  • Property owners
  • Developers
  • General contractors
  • Construction managers
  • Subcontractors
  • Equipment suppliers

Because of these risks, owners and general contractors require subcontractors to provide additional insured protection to shift liability exposure downstream.

Without these endorsements, project owners and general contractors could be forced to rely solely on their own insurance programs, substantially increasing their losses and premiums.

A Certificate of Insurance Is Not Insurance

One of the most common misconceptions in construction is that a certificate of insurance creates coverage.

It does not.

A certificate merely provides evidence that a policy exists. The actual coverage is determined by the insurance policy itself and, more importantly, by the endorsements attached to the policy.

Every year, contractors discover that:

  • The certificate was issued incorrectly.
  • The endorsement required by contract was never added.
  • Completed operations coverage was excluded.
  • The required wording was missing.
  • Coverage was more limited than expected.

When a serious claim occurs, these mistakes can become catastrophic.

The Most Common Additional Insured Endorsements

Several endorsements dominate the New York construction marketplace.

CG 20 10

The CG 20 10 endorsement provides additional insured coverage for liability arising out of ongoing operations performed by the named insured.

This endorsement protects owners and general contractors while construction work is actively being performed.

CG 20 37

The CG 20 37 endorsement extends additional insured coverage to completed operations.

This coverage is critical because many construction claims arise long after the project has been completed.

CG 20 33 and CG 20 38

These endorsements provide additional insured status when required by written contract and have become increasingly common among insurance carriers.

However, the specific language and scope of protection can vary significantly.

The Importance of Completed Operations Coverage

Many contractors mistakenly believe that once a project is completed, their liability exposure disappears.

Unfortunately, construction defect claims, injury claims, and property damage claims frequently emerge months or years after project completion.

Examples include:

  • Falling facade materials
  • Structural failures
  • Water intrusion
  • Electrical defects
  • Fire losses
  • Injuries caused by completed work

Without completed operations additional insured coverage, owners and general contractors may pursue indemnification directly against the contractor.

Primary and Non-Contributory Coverage

Another phrase appearing in virtually every New York construction contract is:

“Coverage shall be primary and non-contributory.”

What does this mean?

It means the contractor’s insurance policy must respond first before the owner’s or general contractor’s insurance contributes to the loss.

Without proper primary and non-contributory wording, disputes between insurance companies often arise, creating delays, legal expenses, and potential uninsured exposures.

Many contractors assume this wording is automatically included in their policies.

Often, it is not.

Contractual Requirements Matter

An additional insured endorsement is only part of the equation.

Construction contracts frequently require:

  • Specific additional insured forms
  • Written contracts executed before work begins
  • Primary and non-contributory wording
  • Waivers of subrogation
  • Completed operations coverage
  • Specific liability limits
  • Excess liability requirements

Failure to comply with these provisions can result in:

  • Breach of contract allegations
  • Loss of indemnification rights
  • Uninsured liability exposure
  • Payment disputes
  • Project delays

A contractor may believe they have complied with the contract, only to discover after a claim that critical requirements were overlooked.

The Action-Over Problem

Additional insured endorsements become especially important in New York action-over claims.

Consider this scenario:

A subcontractor’s employee falls from a scaffold and suffers catastrophic injuries.

The employee collects workers compensation benefits and then sues the property owner and general contractor under Labor Law Sections 240 and 241.

The owner and general contractor seek defense and indemnification under the subcontractor’s additional insured coverage.

If the additional insured endorsements are inadequate, missing, or improperly structured, the resulting litigation can cost millions of dollars.

This is not a rare occurrence.

It is one of the most common and expensive liability scenarios in New York construction.

The Cheapest Policy May Be the Most Expensive Mistake

In today’s competitive insurance marketplace, contractors often focus primarily on price.

However, many low-cost policies achieve their lower premiums through:

  • Restrictive additional insured endorsements
  • Labor Law exclusions
  • Height restrictions
  • Residential exclusions
  • Action-over exclusions
  • Limited completed operations coverage

A policy that saves several thousand dollars in premium can ultimately create millions of dollars in uninsured exposure.

Insurance should never be purchased solely based on price.

It should be purchased based on protection.

Experience Matters

The difference between a properly structured construction insurance program and an inadequate one often comes down to experience.

New York contractor insurance requires understanding:

  • Labor Law exposures
  • Contractual risk transfer
  • Additional insured requirements
  • Action-over claims
  • Umbrella liability structures
  • Workers compensation interactions
  • Excess liability coverage

The right insurance program can protect decades of hard work.

The wrong program can destroy it.

About BGES Group

At BGES Group, we specialize in helping New York contractors navigate the complex world of construction insurance and contractual risk transfer.

For more than 45 years, owner Gary Wallach has worked with contractors throughout New York, New Jersey, and Connecticut, helping businesses secure comprehensive protection while controlling insurance costs.

Our specialties include:

  • General Liability Insurance
  • Workers Compensation Insurance
  • Excess and Umbrella Liability
  • Additional Insured Requirements
  • Labor Law Exposure Analysis
  • Contract Review Assistance
  • Builder’s Risk Insurance
  • Commercial Auto Insurance
  • Contractor Package Policies
  • Risk Transfer Strategies
  • Specialized New York Contractor Insurance Programs

As a boutique insurance agency, we provide personalized service that many large agencies simply cannot match. We understand New York construction risks, issue certificates quickly, and work directly with contractors to identify hidden coverage gaps before claims occur.

If you are a contractor, subcontractor, property owner, or developer, we welcome the opportunity to review your insurance program and help ensure that your coverage protects both your business and your future.

Gary Wallach
BGES Group

Phone: 914-806-5853
Email: bgesgroup@gmail.com
Website: www.bgesgroup.com

Important Financial and Informational Disclaimer

This article is provided solely for informational and educational purposes and does not constitute legal, insurance, financial, tax, or risk management advice. Insurance coverages, policy forms, endorsements, contractual obligations, and legal liabilities vary significantly based upon individual circumstances, applicable law, and insurance carrier requirements. Readers should consult qualified legal counsel and licensed insurance professionals regarding their specific situations. No representation, warranty, or guarantee of coverage, legal outcome, or future results is expressed or implied.

Why Cheap General Liability Insurance Can Bankrupt a New York Contractor

In the highly competitive world of New York construction, every dollar matters. Contractors constantly face pressure to reduce costs, sharpen bids, and remain profitable in one of the most expensive construction markets in the country. When insurance renewal season arrives, many contractors naturally focus on one number above all others: premium.

Unfortunately, when it comes to New York contractor general liability insurance, buying the cheapest policy available can become one of the most expensive mistakes a contractor ever makes.

The difference between a properly structured general liability program and a bargain-basement policy may not become apparent until after a catastrophic accident occurs. By then, it is often too late. The result can be devastating lawsuits, denied claims, bankrupt businesses, and personal financial ruin.

New York Is Not Like Other States

Construction liability in New York is unique. Unlike virtually every other state, New York’s Labor Law Sections 240 and 241 create extraordinary legal exposures for contractors, subcontractors, property owners, and developers.

A worker falling from a ladder, scaffold, roof, or elevated work surface can trigger claims worth millions of dollars. Even contractors with excellent safety records can become defendants in major lawsuits simply because they were involved in the project.

Because of these risks, insurance companies carefully manage their exposure. Some carriers specialize in New York construction risks. Others simply try to avoid them by inserting exclusions and restrictions into their policies.

The problem is that many contractors never realize what coverage they have purchased until a claim occurs.

The Illusion of Cheap Insurance

Imagine two contractors receive quotes:

  • Contractor A pays $18,000 annually.
  • Contractor B pays $10,500 annually.

At first glance, Contractor B appears to have saved $7,500.

But what if Contractor B’s policy contains:

  • Labor Law exclusions
  • Height limitations
  • Residential construction exclusions
  • Employee injury exclusions
  • Action-over exclusions
  • Subcontractor warranty requirements
  • Designated operations exclusions

That $7,500 savings can quickly become a multi-million-dollar uncovered loss.

The cheapest policy is often only cheap because important protections have been removed.

Labor Law Exclusions: The Hidden Time Bomb

Perhaps the most dangerous exclusion found in some contractor policies is the Labor Law exclusion.

New York Labor Law claims represent some of the largest losses in the insurance industry. Because of this, certain carriers simply exclude them altogether.

Imagine this scenario:

A subcontractor employee falls from a scaffold and suffers permanent injuries. The employee sues the building owner and general contractor under Labor Law 240. The owner and general contractor then seek indemnification from your company.

You notify your insurance carrier.

The carrier responds:

“Coverage denied due to Labor Law exclusion.”

At that moment, the insurance policy you purchased to protect your business may provide little or no protection.

Height Restrictions Can Destroy Coverage

Many contractors are surprised to discover that their policy contains height restrictions.

Common limitations include:

  • No work above 10 feet
  • No work above 15 feet
  • No work above two stories
  • No roofing operations
  • No exterior work above certain elevations

The problem is obvious.

If your employee performs work outside the permitted height restriction—even briefly—the insurance company may argue that coverage does not apply.

A contractor may spend years paying premiums only to discover that the work actually being performed was excluded from coverage all along.

Residential Construction Exclusions

Residential construction remains one of the most challenging classes of business for insurance companies.

As a result, some policies contain exclusions for:

  • Single-family homes
  • Multi-family homes
  • Condominium projects
  • Apartment renovations
  • Mixed-use buildings
  • Residential conversions

Many contractors operate in both commercial and residential sectors without fully understanding the restrictions contained within their policies.

A contractor performing what appears to be a routine renovation project could unknowingly create a substantial uninsured exposure.

The Action-Over Problem

One of the most misunderstood exposures in New York construction is the “action-over” claim.

Here’s how it works:

Your employee is injured on a construction site.

Workers compensation pays benefits.

The injured worker then sues the property owner and general contractor under Labor Law 240 or 241.

The owner and general contractor then sue your company for indemnification.

What began as a workers compensation claim suddenly becomes a multi-million-dollar liability lawsuit.

Some policies specifically exclude these action-over claims.

Others provide limited protection.

Many contractors never ask the question.

Additional Insured Problems

Most New York construction contracts require contractors to provide additional insured status to owners and general contractors.

However, not all additional insured endorsements are created equal.

Common problems include:

  • Incorrect endorsements
  • Missing completed operations coverage
  • Failure to provide primary and non-contributory wording
  • Restrictive contractual requirements
  • Insufficient limits

A contractor who fails to provide the required additional insured coverage may find themselves in breach of contract and exposed to uninsured liability.

Excess Liability: The Missing Piece

Even contractors with excellent primary liability coverage often fail to purchase adequate excess or umbrella insurance.

In today’s legal environment, a $1 million general liability policy may be insufficient protection.

Serious Labor Law claims can easily exceed:

  • $2 million
  • $5 million
  • $10 million
  • $20 million or more

Excess liability coverage often represents the difference between surviving a catastrophic claim and losing everything.

Price Is Important—But Value Is Essential

Every contractor wants competitive pricing.

However, insurance should never be viewed simply as a commodity purchase.

The right questions are:

  • Does my policy cover Labor Law claims?
  • Are action-over claims covered?
  • What height restrictions apply?
  • Is residential work excluded?
  • Do I have sufficient umbrella coverage?
  • Are subcontractor requirements clearly defined?
  • Do my additional insured endorsements comply with contracts?
  • Has someone experienced reviewed my exposures?

The objective is not merely to buy insurance.

The objective is to transfer risk.

Experience Matters

New York contractor insurance is among the most specialized areas of commercial insurance.

A policy that appears identical on the declaration page may contain dramatically different coverage provisions.

The difference between adequate and inadequate coverage is often found in endorsements, exclusions, definitions, and contract requirements that many contractors never see.

That is why working with experienced New York construction insurance professionals can be one of the most important business decisions a contractor makes.

About BGES Group

At BGES Group, we specialize in helping contractors navigate the complex and often dangerous world of New York construction insurance.

For more than 45 years, owner Gary Wallach has helped contractors throughout New York, New Jersey, and Connecticut secure comprehensive insurance protection while managing costs and reducing risk.

We understand the unique challenges facing contractors, including:

  • New York Labor Law exposures
  • General Liability Insurance
  • Workers Compensation Insurance
  • Excess and Umbrella Liability
  • Contractor Package Policies
  • Commercial Auto Insurance
  • Builders Risk Insurance
  • Additional Insured Requirements
  • Contract Review Assistance
  • Risk Transfer Strategies
  • Specialized New York Contractor Programs

As a boutique agency, BGES Group provides personalized service, rapid certificate issuance, and direct access to experienced insurance professionals who understand New York construction risks.

Before renewing your insurance, allow us to review your current program and identify potential gaps that could place your business at risk.

Gary Wallach
BGES Group
Phone: 914-806-5853
Email: bgesgroup@gmail.com
Website: www.bgesgroup.com

Important Financial and Informational Disclaimer

This article is provided solely for informational and educational purposes and does not constitute legal, insurance, financial, tax, or risk management advice. Insurance coverages, exclusions, endorsements, policy terms, legal obligations, and Labor Law exposures vary substantially depending upon the specific facts, jurisdiction, policy forms, contractual requirements, and circumstances involved. Readers should consult qualified legal counsel and licensed insurance professionals regarding their particular situations. Coverage availability, underwriting requirements, pricing, and policy provisions vary among insurance carriers. No representation, warranty, or guarantee of coverage or future results is expressed or implied.

The Truth About New York Labor Law Coverage: What Many Insurance Brokers Never Explain

If you’re a New York contractor, you’ve probably noticed your insurance premiums climbing year after year. You may have also experienced insurance companies refusing to quote your business, reducing coverage, or adding exclusions you’ve never seen before.

The reason is simple: New York Labor Law.

Unfortunately, many insurance brokers never fully explain how these laws affect your business or review whether your insurance program truly protects you. They simply shop for the lowest premium, issue a certificate of insurance, and move on.

That can be a very expensive mistake.

Understanding New York Labor Law

New York Labor Law Sections 200, 240, and 241 are among the most contractor-unfriendly laws in the country. Labor Law 240, often called the Scaffold Law, imposes strict liability on owners and general contractors for many gravity-related injuries involving falls from heights or falling objects. Labor Law 241 establishes safety requirements for construction, excavation, and demolition work, while Labor Law 200 addresses general workplace safety obligations. These laws are a major reason why insurance for New York contractors is more expensive and harder to obtain than in most other states.

Because of these laws, a single accident can result in a lawsuit involving the property owner, general contractor, construction manager, subcontractors, and multiple insurance companies.

When millions of dollars are at stake, every word in your insurance policy matters.

The Biggest Mistake Contractors Make

Many contractors believe they are protected simply because they have:

  • General Liability Insurance
  • Workers’ Compensation Insurance
  • Umbrella Liability Insurance

That is not always true.

Insurance companies have spent years rewriting policy language to reduce their exposure to New York Labor Law claims. If your broker doesn’t carefully review your policy forms and endorsements, you could discover important coverage limitations only after a serious accident occurs.

Coverage Gaps Your Broker Should Be Reviewing

A construction insurance specialist should carefully review your policies for issues such as:

Labor Law Exclusions

Some policies contain endorsements that limit or exclude certain New York Labor Law exposures.

Action Over Exclusions

These exclusions can significantly reduce or eliminate coverage when an injured employee of a subcontractor brings a claim that is passed upstream to a general contractor or owner.

Injury to Employee Exclusions

These endorsements may severely limit coverage involving employee injury claims.

Additional Insured Endorsements

Many contracts require you to provide additional insured status. Using the wrong endorsement can create disputes when a claim occurs.

Primary & Non-Contributory Coverage

Many project owners require your insurance to respond before theirs. If your policy doesn’t satisfy the contract requirements, you could face major problems.

Waiver of Subrogation

This endorsement is frequently required by construction contracts and should be verified before work begins.

Contractual Liability

Construction contracts often require broad indemnification provisions. Your insurance should be reviewed to ensure it supports the obligations you agree to.

Excess & Umbrella Liability

Not every umbrella policy follows the underlying general liability policy in the same manner. Coverage differences can become significant during large claims.

Certificates of Insurance Are Not Enough

Many contractors assume that receiving a certificate of insurance means they have the protection required by their contract.

It doesn’t.

A certificate is simply evidence that insurance existed on the day it was issued. It does not modify your policy, expand coverage, or override exclusions. The actual policy forms and endorsements determine how a claim will be handled.

Article content

Why Experience Matters

Construction insurance in New York has become one of the most specialized areas of the insurance industry.

Many carriers have reduced their appetite for contractors or stopped writing certain construction classes altogether because of the risks associated with New York Labor Law claims. That makes selecting the right insurance company—and the right broker—even more important.

An experienced construction insurance broker should understand:

  • Labor Law exposures
  • Contract review
  • Additional insured requirements
  • OCIP and CCIP projects
  • Hold harmless agreements
  • Excess liability structures
  • Risk transfer strategies
  • Workers’ Compensation programs
  • Safety and loss control

These are not topics that every insurance agency understands.

Why Contractors Choose BGES Group

At BGES Group, construction insurance isn’t just another department—it’s our specialty.

We have spent decades helping New York contractors navigate one of the toughest insurance markets in the country. We understand the challenges contractors face because we work with them every day.

When you work with BGES Group, you receive more than an insurance policy—you gain an advocate who understands your business.

We Specialize In:

  • New York Construction Insurance
  • General Liability Insurance
  • Workers’ Compensation Insurance
  • Excess & Umbrella Liability
  • Builders Risk
  • Commercial Auto
  • Inland Marine
  • Bid & Performance Bonds

Why Contractors Call BGES Group

  • We specialize in New York construction insurance.
  • We understand New York Labor Law exposures.
  • We review your coverage—not just your premium.
  • We represent numerous top-rated insurance carriers to help find competitive pricing.
  • We issue certificates of insurance quickly—often within minutes.
  • We answer our phones. When you need help, you’ll speak with a real person, not an automated system.
  • We provide personalized service from experienced professionals who understand construction.

Our goal is simple:

Help protect your business before a claim happens—not after.

Get a Second Opinion

If your current insurance broker has never discussed your Labor Law exposure, reviewed your endorsements, explained potential coverage gaps, or helped you understand how your insurance responds to New York construction claims, it may be time for a second opinion.

A thorough review of your insurance program could identify issues before they become costly problems.

There is no obligation, and the peace of mind may be worth far more than the cost of your insurance.

Contact BGES Group Today

If you’re a New York contractor looking for experienced guidance and personalized service, we’d love the opportunity to earn your business.

Contact – Gary Wallach

Phone:914-806-5853

Email: bgesgroup@gmail.com

Website: www.bgesgroup.com

Don’t wait until after a claim to find out what your insurance doesn’t cover. Call BGES Group today and discover why so many New York contractors trust us to help protect the businesses they’ve worked so hard to build.