15 Essential Workers’ Compensation Insurance NY Requirements for Small Businesses

Navigating the world of workers’ compensation insurance in New York can be a daunting task, especially for small business owners. This essential coverage not only protects your employees but also safeguards your business from potential legal and financial setbacks. In this guide, we’ll break down the key requirements you need to know to ensure compliance and peace of mind.
A top view image of small business tools including a calendar, coins, and a smartphone calculator.

1. Understanding the Basics

Before diving into specific requirements, it’s vital to grasp the basics of what workers’ compensation insurance covers and why it’s essential for your business. In essence, workers’ compensation insurance is designed to provide monetary benefits to employees who suffer work-related injuries or illnesses. This coverage is not just a legal requirement but also a crucial safety net that ensures employees receive the necessary medical care and financial support during their recovery period. As a business owner, understanding the foundational aspects of this insurance can help you navigate the complexities that follow. A well-rounded overview of workers’ compensation can offer further insights into this critical safety measure.

2. Who Needs Coverage

In New York, virtually all businesses with employees are required to have workers’ compensation insurance. This includes both for-profit and non-profit organizations, ensuring that most part-time and full-time employees are protected. However, it’s important to note that there are some exceptions, such as sole proprietors with no employees and certain independent contractors. Understanding the details of these requirements is crucial in preventing any legal repercussions for your business. By visiting New York’s requirements for workers’ compensation insurance, you can grasp a clearer picture of who needs this coverage.

Beyond the mandates, it’s naturally wise for businesses to explore inclusion of additional types of coverage. This added protection might cover situations unique to your industry or employee roles. By assessing potential risk areas specific to your operations, you can tailor your policy to provide ample coverage. In this way, you create a safer, more compliant work environment, enhancing overall employee well-being.

3. Calculating Premiums

Calculating the premiums for workers’ compensation insurance can feel like cracking a code, especially considering the variety of factors affecting the total cost. The primary components include the size of your payroll, the industry in which your business operates, and the risk classification assigned to jobs performed by your employees. Additionally, your claims history can also significantly influence premiums. Businesses with a higher number of past claims typically face steeper premium costs. For small business owners striving to manage costs, investing in robust safety programs may help reduce these expenses over time by potentially lowering your risk classification. Understanding how these elements interact can be clarified by referring to various premium calculation guides discussing New York regulations.

4. Choosing the Right Policy

Choosing the right workers’ compensation policy is paramount for a small business. The first step lies in evaluating your business size, industry risks, and potential exposure. Policies differ widely in terms of coverage scope and cost; hence, a policy that aligns closely with your business operations is essential. Connecting with experienced insurance brokers can aid in breaking down the breadth of policies available, ultimately guiding you to the most fitting decision. For personalized solutions, you can delve into coverage options that resonate with specific business requirements, ensuring every possible risk is well mitigated.

In addition to policy selection, it is beneficial to continuously assess coverage adequacy in light of business evolution. As the business landscape shifts, your objective is to maintain a dynamic insurance strategy that evolves along with the changing operational environment. With professionalism and attention to detail, you can forge a policy path that effectively safeguards your business and its valued employees.

5. Employee Status Considerations

Employee classification plays a crucial role in determining your workers’ compensation responsibilities. Whether your staff consists of full-time, part-time, or independent contractors influences your insurance coverage requirements. Full-time employees are typically covered under workers’ comp policies, while part-time employees should be evaluated based on hours worked and job roles. In contrast, independent contractors may not always need to be covered, depending on the contractual agreements and state-specific laws. For a comprehensive understanding, employers should familiarize themselves with the IRS guidelines on proper employee classification.

6. Staying Compliant with State Laws

Compliance with New York’s state-specific laws is essential to ensure legal and operational continuity. The state mandates that all businesses must secure insurance coverage for their employees. Non-compliance can result in severe penalties, including fines and possible criminal charges. Business owners should regularly consult with legal advisors and industry experts to remain abreast of evolving laws and regulations. This proactive approach not only protects the business legally but also demonstrates a commitment to employee welfare.

Furthermore, engaging with ongoing employee education programs can be beneficial. By informing employees about state regulations and their rights under workers’ compensation insurance, businesses promote a transparent workplace culture. This aids in fostering trust and alignment across organization teams, ultimately contributing to a healthier working environment.

7. The Role of Safety Programs

Safety programs serve a dual purpose within organizations: they safeguard employee well-being and simultaneously impact insurance costs. By systematically reducing workplace accidents and illnesses through authorized safety measures, businesses can achieve profound benefits. Such reductions in claim incidents, over time, lead to potential decreases in premium expenses, creating a financially favorable scenario. Resources providing insights on effective workplace safety strategies are available for business consideration.

8. Handling Claims Process

A seamless and efficient claims process is fundamental in maintaining workplace harmony and limiting business disruptions. When an incident occurs, it’s essential to follow established procedures for reporting and notifying relevant parties promptly. Thorough documentation and accurate reporting are integral to securing a fair resolution to claims. For enhanced efficiency, smaller businesses can leverage guidebooks on claims management to navigate the often complex landscape of workers’ compensation claims.

Moreover, ongoing communication with both the injured employee and their medical providers is crucial. This helps to avoid misunderstandings and ensures that both parties reach an appropriate agreement swiftly. By upholding transparency and clear communication channels, businesses enhance their reputation as employers attentive to employee needs, fostering a supportive organizational atmosphere.

9. Dealing with Fraud

Workers’ compensation fraud is an issue that can drastically affect a business’s financial health. Fraudulent claims increase insurance premiums and place unnecessary strain on company resources. Vigilant monitoring and implementation of fraud detection measures are vital. By instituting identification and reporting procedures, businesses can minimize fraudulent activities. Training employees to detect signs of fraud is an indispensable step in safeguarding your business. For further reading, references on preventing insurance fraud offer practical advice.

10. Keeping Up with Policy Changes

Workers’ compensation insurance policies are not static and are subject to evolving legal landscapes. Staying informed about updates and changes is crucial for ensuring continued compliance and protection. Regular consultation with insurance professionals and subscription to industry newsletters can aid in staying informed. Proactively adjusting your policies in response to legislative changes can help avoid possible compliance issues. Access to comprehensive insights into the regulatory environment ensures you’re prepared for any policy shifts.

11. Assessing Coverage Gaps

Identifying potential coverage gaps requires a keen eye and thorough policy scrutiny. Gaps may arise from changes in business operations, increased exposure levels, or improper policy customization. To effectively bridge these gaps, businesses should regularly evaluate their policy parameters and identify potential vulnerabilities in coverage. Through consultation with insurance experts, you can ensure your coverage provides maximum protection from unanticipated liabilities.

Moreover, by conducting regular policy assessments, businesses are empowered to adapt strategically to changes. This proactive stance allows for a more resilient business position, equipped to handle a broad spectrum of risk scenarios. Ensuring comprehensive protection entails not only resolving existing deficiencies but also anticipating future needs for complete operational stability.

12. Renewal and Audit Practices

Regular policy renewal and audit practices play an indispensable role in maintaining effective insurance coverage. By routinely reassessing your insurance needs and updating policies accordingly, you guard against outdated coverage that fails to align with your business’s current realities. Audits also ensure accuracy in claims and compliance with any new regulations that have been enacted over the policy term. For a structured audit methodology, referring to professional auditing guidelines can further equip businesses with necessary insights.

Additionally, cultivating strong relationships with insurance providers can facilitate the renewal process. Regularly scheduled reviews with policy professionals increase the likelihood of securing suitable coverage decisions promptly. Such practices illustrate business commitment to proactive management and organizational diligence, ultimately maintaining robust protective measures.

13. The Impact of Business Growth

As small businesses grow in size and operations, it’s essential to revisit and reassess their workers’ compensation insurance policies. New partnerships, expanded geographical presence, and increased employee counts are factors that necessitate adjustments to your coverage. These changes can lead to higher insurance premiums, making it imperative to manage and anticipate costs proactively.

Additionally, expansion might require you to comply with different state laws if new locations are opened outside New York. Maintaining updated policies ensures not only regulatory adherence but also resilient business operations. Engaging with seasoned business consultants or legal advisors can aid in strategizing an effective insurance management plan that aligns with your growing business footprint.

14. Utilizing Professional Services

Navigating the intricacies of workers’ compensation insurance can be streamlined by leveraging professional services. Collaborating with insurance brokers or consultants provides tailored insights and expert guidance, crucial for sound decision-making processes. These professionals assist in policy selection and customization, ensuring congruence with industry standards and unique business needs. Insights on working effectively with insurance consultants offer a comprehensive perspective on the value of professional advice.

15. Leveraging Technology Solutions

Technology integration into insurance management processes paves the way for operational efficiencies and enhanced accuracy. Innovative software solutions can simplify complex administrative tasks, such as tracking claims and maintaining compliance records. By adopting reliable tech tools, businesses can minimize errors and effortlessly align their operations with regulatory standards. Well-executed technology solutions contribute to smoother claim handling and reduce administrative burdens, leading to enhanced productivity and cost-effectiveness.

Moreover, data analytics derived from technological systems provide valuable insights into claim patterns and risk assessments. Leveraging these insights empowers businesses to predict potential challenges and strategically shape future policy decisions. Transforming insurance management through digital transformation allows for efficient process enhancements and supports a forward-thinking business model.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com
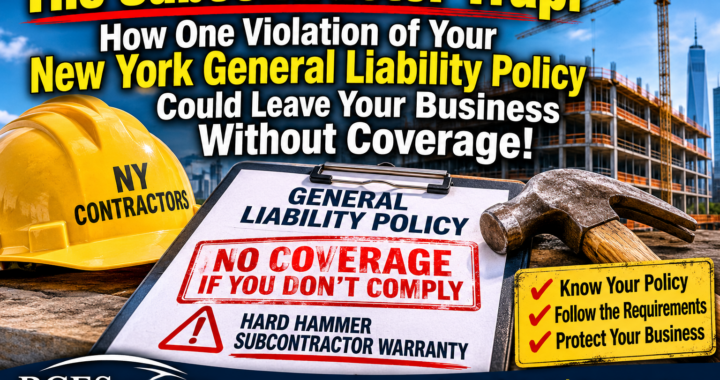


The Subcontractor Trap: How One Violation of Your New York General Liability Policy Could Leave Your Construction Business Without Coverage

New York Contractors: Your General Liability Policy May Not Protect You If You Fail to Follow Its Subcontractor Requirements.

If you are a New York construction contractor, you probably purchased general liability insurance believing that it would protect your business if something went wrong on a jobsite. You pay your premiums, provide certificates of insurance when requested, and assume that your insurance company will be there if a lawsuit or serious accident occurs.

But there is something many contractors overlook that could put their entire business at risk: the subcontractor warranty endorsement contained in their general liability policy.

Some New York contractors have policies containing what insurance professionals refer to as a Hard Hammer Subcontractor Warranty.

This is not just another piece of insurance paperwork. It can be one of the most important provisions in your entire general liability policy.

If you fail to comply with its requirements, you could discover that the insurance coverage you thought you had may not be available when you need it most.

Let’s take a closer look at how these warranties work and why every New York contractor needs to understand them.

1. What Is a Hard Hammer Subcontractor Warranty?

A Hard Hammer Subcontractor Warranty is an endorsement attached to a general liability policy that establishes specific requirements a contractor must follow when hiring and using subcontractors.

The insurance company is essentially saying:

“We are agreeing to insure your construction business, but you must follow certain rules when hiring subcontractors and transferring risk.”

These requirements are generally designed to make sure that subcontractors carry appropriate insurance and that the general contractor is properly protected from liability arising out of subcontracted work.

Depending on the actual endorsement, requirements may include:

  • Obtaining certificates of insurance from every subcontractor before work begins.
  • Maintaining copies of subcontractors’ insurance policies or other required documentation.
  • Requiring subcontractors to carry specified general liability limits.
  • Obtaining additional insured endorsements naming your business as an additional insured.
  • Obtaining written contracts containing specific insurance and indemnification provisions.
  • Making sure subcontractors maintain workers’ compensation insurance when legally required.
  • Maintaining records demonstrating compliance with the warranty requirements.

The important thing to understand is that the exact requirements are determined by the wording of your particular endorsement.

One insurance company’s requirements may differ substantially from another’s.

Never assume that obtaining a certificate of insurance alone satisfies your subcontractor warranty.

2. Why Is It Called a Hard Hammer?

The term Hard Hammer is used in the insurance industry to describe particularly strict subcontractor warranty requirements.

Unlike a more flexible arrangement, a hard hammer provision can impose serious consequences when a contractor fails to follow the required procedures.

For example, imagine you are a New York general contractor hired to renovate a commercial building.

You hire a framing subcontractor, a plumbing contractor, an electrician and a drywall company.

You obtain certificates of insurance from some of these subcontractors, but you fail to obtain the required additional insured endorsements. Perhaps one subcontractor starts working before you collect the required documentation.

Everything appears to be going smoothly until an employee of one of those subcontractors suffers a serious injury.

A lawsuit follows, naming your company, the property owner and other parties.

You immediately notify your general liability insurance carrier and expect it to defend you.

But then the insurance company examines your policy and discovers that you did not comply with the subcontractor warranty.

Suddenly, you have a potentially serious insurance problem.

Depending on the endorsement’s language, the nature of the violation and applicable law, the carrier may assert that coverage is unavailable, restricted or otherwise affected.

You could find yourself paying substantial legal expenses and potentially facing a significant uninsured liability.

That is a risk no contractor should take lightly.

3. A Certificate of Insurance Does Not Necessarily Protect You

This is one of the biggest misconceptions in the construction industry.

Many contractors believe that obtaining a certificate of insurance from a subcontractor means they have satisfied their insurance obligations.

That is not necessarily true.

A certificate of insurance is primarily evidence of insurance at a particular point in time. It does not amend the policy, create additional insured coverage or guarantee that the subcontractor’s policy provides the protection you need.

For example, your subcontractor might provide a certificate showing $1 million in general liability coverage.

However, your insurance company’s warranty might require:

  • A specific additional insured endorsement.
  • Coverage for both ongoing and completed operations.
  • Specific liability limits.
  • A written contract executed before work begins.
  • Verification that the subcontractor’s policy does not contain certain exclusions.

If the required endorsements or documentation are missing, you may not have satisfied your policy’s requirements.

The difference between having a certificate and having the actual required insurance protection can be enormous.

4. What Happens If a Subcontractor Does Not Have Insurance?

Here is another situation that deserves attention.

Suppose you hire a small subcontractor who gives you a very attractive price for a particular job.

The subcontractor tells you that he does not carry general liability insurance but promises that he will take responsibility for anything that happens.

You decide to hire him anyway.

Unfortunately, if your general liability policy contains a hard hammer subcontractor warranty requiring every subcontractor to maintain specified insurance, you may have violated the warranty.

Now imagine that someone gets injured while that subcontractor is working on your project.

Your general liability carrier may take the position that you failed to comply with the policy’s requirements.

The consequences could be devastating.

The contractor who saved a few dollars by hiring an uninsured subcontractor could end up facing a lawsuit without the insurance protection he expected.

Saving money on subcontractor costs is never worth jeopardizing your general liability coverage.

5. What About 1099 Workers?

This is another area where contractors need to be especially careful.

Many construction businesses use independent contractors, temporary workers and individuals paid on a 1099 basis.

Some contractors assume that because these individuals are not traditional employees, they do not fall under the subcontractor requirements.

That assumption can be dangerous.

An insurance company may consider a 1099 worker a subcontractor for purposes of the warranty, depending on the policy language and the actual working relationship.

If that individual does not carry the required insurance, the contractor could have a compliance problem.

Before allowing a 1099 worker or independent contractor onto a jobsite, review your policy and determine exactly what documentation and insurance protection are required.

Do not wait until an accident occurs to find out.

6. What Should New York Contractors Do to Protect Themselves?

If you are a general contractor, construction manager or subcontractor operating in New York, there are several steps you should take.

First: Read your general liability policy.

Do not simply look at the declarations page to see your limits and premium. Review the endorsements attached to your policy.

Pay particular attention to any subcontractor warranty, subcontractor exclusion or other endorsement dealing with subcontracted work.

Second: Understand the requirements before hiring subcontractors.

Make sure you know what insurance limits, endorsements, contracts and documentation your carrier requires.

Third: Collect the necessary documentation before work begins.

Do not allow subcontractors to start working while you are still waiting for insurance documents.

Fourth: Verify the actual coverage.

Certificates are not always sufficient. Obtain and review the endorsements and other documentation required by your policy.

Fifth: Maintain organized records.

Keep certificates, endorsements, written contracts and other required documentation readily available.

Sixth: Have your insurance broker review your policy.

An experienced construction insurance broker should be able to identify potentially problematic endorsements and explain what your company must do to remain compliant.

7. The Bottom Line: Your General Liability Policy Is Only as Good as Your Understanding of It

New York construction is already a difficult business.

Contractors face significant exposure from construction accidents, New York Labor Law claims, employee injuries, property damage and lawsuits involving owners, general contractors and subcontractors.

Your general liability insurance is supposed to help protect your business from these risks.

But purchasing a policy does not mean you can ignore the conditions, exclusions and endorsements attached to it.

A Hard Hammer Subcontractor Warranty deserves particular attention because failure to follow its requirements can have serious coverage consequences.

Do not assume that your insurance company will overlook a missing certificate, an improperly insured subcontractor or a missing additional insured endorsement after a serious accident.

The time to understand your insurance requirements is before a claim happens, not after you receive a lawsuit.

One overlooked endorsement could become one of the most expensive mistakes your construction business ever makes.

About BGES Group

BGES Group is an independent, boutique insurance brokerage specializing in insurance solutions for New York construction contractors and business owners throughout New York, New Jersey and Connecticut.

We understand the unique insurance challenges facing the construction industry, including general liability, subcontractor requirements, workers’ compensation, umbrella and excess liability, commercial auto, disability insurance and other essential business coverages.

At BGES Group, we believe in doing business the old-fashioned way, with modern technology and personal attention.

We are not an internet insurance factory. We believe in knowing our clients, answering the phone, understanding their businesses and being available when they need us.

Our philosophy is simple:

  • Personal service and one-on-one attention.
  • Phone calls answered promptly.
  • Certificates of insurance handled quickly.
  • Competitive insurance markets and practical solutions.
  • Experienced guidance when insurance problems arise.
  • Helping contractors obtain coverage when other brokers cannot.

We have been helping businesses navigate the insurance industry since 2002, bringing more than 45 years of insurance experience to the table.

At BGES Group, you are not just another policy number. You are a client, and we treat you that way.

Contact BGES Group

Gary Wallach

BGES Group

Phone: 914-806-5853

Email: bgesgroup@gmail.com

Website: www.bgesgroup.com

If you are a New York contractor and have questions about your general liability policy, subcontractor warranties or whether your current insurance program adequately protects your business, give us a call.

Let’s make sure you understand what you are buying before you need to use it.

What is Construction Workers Comp Insurance in New York?

Navigating the world of insurance can be tricky, especially when it comes to understanding Construction Workers Comp Insurance in New York. In this FAQ, we’ll break down the key aspects of this essential coverage, helping you understand what it is, why it’s important, and how it works.

Construction workers wearing safety gear at an indoor building site in Delhi.

What is Construction Workers Comp Insurance?

Construction Workers Comp Insurance is a vital type of coverage that safeguards employees in the construction industry by providing benefits if they are injured or fall ill due to their job. This specific coverage becomes crucial due to the high-risk nature of the construction sector, ensuring that workers receive financial support for recovery while also protecting employers from potential lawsuits. With the right insurance policy, workers can focus on their recovery without worrying about financial burdens.

Beyond medical expenses, Construction Workers Comp Insurance encompasses a variety of protections, including wage replacement for the time workers are unable to return to work. In doing so, it helps maintain financial stability for families impacted by workplace injuries. For employers, this insurance acts as a buffer, preventing costly legal battles and fostering a safe work environment that prioritizes employee health and well-being.

Why is it Important in New York?

In a bustling city like New York, where construction sites are as common as yellow cabs, the importance of Workers Comp Insurance cannot be overstated. New York state mandates this insurance to protect construction workers from the inherent risks associated with their jobs. By having this coverage, not only do companies comply with New York state laws, but they also demonstrate a commitment to their workers’ safety and financial security.

Consider this: without adequate compensation insurance, an accident in one of New York’s many skyscraping projects could leave an employee struggling to pay medical bills while unable to work. This insurance is designed to prevent such scenarios, offering a comprehensive safety net for the workforce and a level of assurance for construction firms aiming to uphold a sterling industry reputation.

What Does it Cover?

The coverage of Construction Workers Comp Insurance extends well beyond basic medical costs. It also includes compensation for lost wages when employees are unable to work due to their injuries. Moreover, should an injury result in a permanent disability, the policy covers disability benefits that support the worker indefinitely. This ensures continuous support during extended recovery periods.

Furthermore, the insurance often offers vocational rehabilitation services, aiding workers in gaining new skills if they can’t return to their previous job roles due to the extent of their injuries. These programs are essential for helping employees reintegrate into the workforce, turning a potentially life-altering setback into an opportunity for career transformation.

Depending on the policy specifics, some insurance plans might also cover death benefits for fatal accidents, helping families with funeral costs and other immediate financial needs. This comprehensive approach underscores the multifaceted support that construction workers comp insurance aims to provide.

How to Obtain Coverage?

Securing coverage for construction workers comp insurance involves several steps. Initially, businesses should evaluate the scale and specific needs of their operations. This evaluation helps in tailoring the policy to cover all potential risks pertinent to their industry domain. Once this is clear, companies can choose to acquire insurance through private insurers or state-funded programs.

It’s crucial to conduct a comprehensive comparison of different policies offered by various insurers, considering elements such as premium costs, coverage limits, and claim processing efficiency. This comparison enables businesses to adopt a plan that aligns well with their financial and operational goals, ensuring thorough protection for their workforce. Consulting with an expert in workers compensation services can also provide invaluable insights and guidance.

Additionally, businesses must stay updated with regulatory changes to remain compliant with state requirements, avoiding potential fines or legal entanglements. Maintaining open communication with insurance providers ensures that the chosen policy remains relevant and comprehensive as business needs evolve.

Wrapping Up: Key Takeaways

Understanding Construction Workers Comp Insurance is crucial for anyone involved in the construction industry in New York. By grasping the essentials of this insurance, you ensure not only compliance with state regulations but also the safety and protection of your workforce.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com
Exploring the Benefits of General Contractor Insurance NYC

Navigating the bustling construction landscape of New York City requires more than just skill and expertise. For general contractors, safeguarding their projects and interests is crucial. General contractor insurance offers comprehensive protection, ensuring that contractors can focus on their work without worrying about potential liabilities. In this blog, we’ll explore the various benefits of having general contractor insurance in NYC.

Aerial view of a construction site in downtown New York City with surrounding buildings.

Understanding General Contractor Insurance

General contractor insurance is designed to cover the unique risks associated with construction projects. It typically includes general liability insurance, which protects against claims of bodily injury or property damage that may occur during a project.

Exploring the nitty-gritty, general contractor insurance aims to provide a safeguarding net for contractors largely exposed to various risks inherent in construction. This insurance is not just an accessory but a fundamental aspect of stability and legality in operations. Apart from general liability insurance, many policies integrate elements like workers’ compensation, equipment protection, and even coverage for unforeseen delays or errors. In a city brimming with opportunities and potential hazards like NYC, such an all-encompassing protection plan becomes invaluable.

An essential component of general contractor insurance is the coverage it offers for completed operations. This specific aspect ensures that contractors are protected even after their work on a project is finished. If claims are made regarding a service provided, such as a repair work done wrong or a construction flaw that emerges months later, having this insurance protects against costly financial repercussion. It’s intricacies like these that make contractor insurance a wise investment.

Why Insurance is Essential in NYC

Operating in a densely populated and regulated city like NYC means facing a myriad of challenges and legal requirements. Having robust insurance helps contractors comply with local laws, making it easier to secure necessary permits and contracts.

In NYC, the hustle of construction is paired with stringent legal frameworks that demand diligence and thoroughness from contractors. Due to the city’s vast legal landscape, possessing the appropriate insurance is not only a pathway to mitigating risks but also a means to swiftly navigate these regulations. It empowers contractors, enabling them to focus on delivering quality projects without being hampered by potential bureaucratic obstacles or unexpected legal challenges.

Moreover, insurance plays a crucial role in enhancing a contractor’s reputation in NYC. The construction industry is competitive, and demonstrating a commitment to risk management not only signifies responsible business practice but also sets a contractor apart in the eyes of potential clients and partners. By consistently maintaining comprehensive insurance, contractors align with industry standards, adhering to NYC’s high safety and operational benchmarks.

Protecting Your Business from Financial Loss

The financial implications of accidents or lawsuits can be overwhelming without insurance. General contractor insurance covers legal fees, medical expenses, and damage repairs, shielding your business from potentially devastating financial setbacks.

Imagine a scenario where a minor oversight leads to a substantial accident on a project site. Without the safety net of insurance, a contractor could face debilitating financial strain due to costly legal battles or hefty compensations. This protection extends beyond just immediate physical damage or injuries. By safeguarding against financial liabilities, contractors ensure their business foundations remain intact even amidst challenges. Insurance mitigates these risks, ensuring that businesses don’t crumble under pressure from unexpected circumstances.

Furthermore, some insurance policies offer customizable options that allow contractors to scale their coverage in alignment with business growth. This adaptability ensures that as they take on larger projects, the security net scales accordingly, maintaining adequate protection. Contractors can thus channel their energy towards growing their business, knowing that any potential financial pitfalls are managed effectively.

Enhancing Professional Reputation

Having insurance demonstrates professionalism and reliability to clients and partners. It reassures them that you are prepared for any unforeseen circumstances, thus enhancing trust and encouraging long-term business relationships.

In the competitive NYC construction environment, every edge counts, and having comprehensive insurance signals a contractor’s dedication to thoroughness and quality assurance. This assurance attracts a discerning clientele who value security and professionalism. It also fosters a sense of reliability that can differentiate one contractor from another, helping to forge strong, lasting partnerships built on mutual trust and confidence.

Taking a step further, insurance is also a reflection of a contractor’s commitment to ethical practices and sustainability. A well-insured contractor is viewed not just as a business transaction but as a valued ally in a project’s lifecycle. Clients are more inclined to trust contractors who demonstrate an awareness of their responsibilities and have the foresight to safeguard against potential pitfalls. This allows both parties to focus on innovation and excellence in project delivery.

Finally, by maintaining comprehensive insurance coverage, contractors can also qualify for exclusive work opportunities that require stringent compliance with safety and liability standards. This positions them favorably in NYC’s dynamic market, providing access to premium projects and collaborations that bolster their professional standing and business growth.

The Necessity of Insurance for NYC Contractors

In the dynamic construction industry of New York City, having the right insurance is not a luxury—it’s a necessity. General contractor insurance affords the peace of mind needed to operate confidently, protecting not just your projects but also your livelihood. By investing in comprehensive insurance coverage, contractors can mitigate risks, enhance their reputation, and ultimately, ensure the long-term success of their business.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com


Does General Liability Insurance Provide Coverage for New York Labor Laws?

Navigating the complexities of New York labor laws can be challenging for businesses. Understanding what coverages are necessary is vital to ensure full compliance and protection. One question that frequently arises is whether general liability insurance provides adequate coverage for these state-specific labor laws.

What is General Liability Insurance?

General liability insurance is a foundational policy for many businesses, offering protection against claims of bodily injury, property damage, and personal or advertising injury. It is essential for risk management and provides financial peace of mind in the event of unexpected incidents.

This type of insurance is designed to cover a variety of potential risks that businesses face daily. For instance, if a customer slips and falls on a wet floor in your store and decides to sue, general liability insurance can cover medical expenses and legal fees. The coverage extends to most accidents that occur on business premises, ensuring that companies don’t suffer financially while dealing with such incidents.

Additionally, general liability insurance is often a prerequisite for leasing commercial spaces and acquiring certain licenses. By having this insurance, businesses demonstrate a commitment to maintaining a safe environment for employees and customers alike. However, despite its extensive reach, it’s crucial to remember that this type of insurance has its limitations when it comes to certain areas, especially those concerning labor laws.

Understanding New York Labor Laws

New York labor laws are designed to protect the rights of workers and cover a range of issues including minimum wage, overtime pay, and unfair labor practices. Employers must adhere to these regulations to avoid potential legal actions.

These laws are enforced stringently in New York, making it important for business owners to stay informed and compliant. A particularly notable aspect is the New York Labor Law Section 240, often referred to as the ‘Scaffold Law’, which holds employers and property owners fully accountable for accidents occurring from height-related tasks unless proper safety measures are enacted.

Understanding the details of these laws is not just beneficial but necessary for business owners, as non-compliance can result in hefty fines and potential lawsuits. Keeping up-to-date with the changing landscape of these laws can be daunting, but it’s essential for protecting both the rights of employees and the integrity of the business.

General Liability Insurance and Labor Laws: The Connection

While general liability insurance covers many areas, it typically does not extend to violations of labor laws. This is an important consideration for New York businesses, as fines and legal actions related to labor law non-compliance can be substantial.

General liability insurance is excellent for unforeseen events like a customer injury or damage to someone’s property during the course of business operations. However, when it comes to labor laws, general liability does not cover claims associated with employment-related issues like harassment, discrimination, or wrongful termination. Businesses need to be acutely aware of these exclusions to avoid nasty surprises when settling claims.

Additional Coverage Options for Labor Law Compliance

For comprehensive protection, businesses should look into employment practices liability insurance (EPLI), which specifically addresses issues such as wrongful termination and discrimination, offering peace of mind against labor law claims.

EPLI is a valuable resource for businesses aiming to protect themselves from lawsuits that arise from alleged violations of employees’ rights. It is crucial for businesses not only to have such insurance but also to regularly review and update policies in alignment with current labor laws to ensure full compliance.

Summing Up: Navigating Insurance and Labor Laws in New York

In conclusion, while general liability insurance provides a broad spectrum of protection, it is crucial for businesses operating in New York to understand its limitations regarding labor law coverage. Employers may need to consider additional policies that are specifically designed for employment practices to ensure comprehensive protection. Being well-informed and consulting with insurance professionals can help businesses navigate their insurance needs more effectively.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com


Can Contractor Liability Insurance Protect Against All Risks?

Navigating the intricacies of contractor liability insurance can be daunting. Many contractors wonder if this type of insurance can protect them against all possible risks they face in their line of work. In this FAQ, we aim to address this question by exploring the scope and limitations of contractor liability insurance.

What is Contractor Liability Insurance?

Contractor liability insurance is a policy designed to cover professionals in the construction industry. Its primary function is to protect against claims of damage or injury caused to third parties during business operations. Such insurance is crucial for safeguarding against unforeseen circumstances that may arise due to accidents on job sites. This insurance not only provides peace of mind but also secures the financial stability of a contractor’s business.

Contractors face numerous risks daily, and having this insurance helps mitigate unexpected expenses arising from legal claims. Whether it be an injured visitor or damage to a client’s property, contractor liability insurance offers a shield against potential lawsuits. Moreover, it can enhance a contractor’s professional credibility, signaling reliability and responsibility to potential clients.

Common Risks Covered by Contractor Liability Insurance

The typical risks covered by contractor liability insurance include property damage, bodily injury, and personal injury claims. For instance, if a contractor accidentally damages a client’s home or a visitor slips and falls on a construction site, this insurance would typically cover the ensuing costs. Such coverage helps avoid financial strain and allows contractors to continue their operations smoothly.

Additionally, contractor liability insurance covers advertising injury claims, which might arise from unintentional slander or copyright infringement related to promotional activities. Understanding these common risks and how they are addressed by the insurance allows contractors to better appreciate the value of their investment in such policies.

What Risks Are Not Covered?

Despite its comprehensive nature, contractor liability insurance has its limitations. It does not cover professional mistakes, which means errors in design or judgment that lead to financial loss require separate professional liability insurance. Similarly, employee injuries are not covered under this policy; such incidents necessitate a workers’ compensation policy.

Damage to ongoing work is another risk not typically covered. Contractors must consider additional policies, such as construction all-risk insurance, to address this gap. Understanding what is excluded from contractor liability insurance is crucial for contractors to fully protect their businesses and avoid unexpected financial burdens.

How to Determine Your Coverage Needs

Determining the right amount of coverage begins with a thorough assessment of your business’s unique risks. Analyzing your contract requirements, types of projects, and locations will guide you in understanding the scope of coverage you need. Consulting with insurance experts can provide personalized insights that help tailor a policy to match those needs effectively.

It’s also beneficial to review client requirements, as some may require specific coverage minimums. Additionally, staying informed about industry standards and regulatory changes can impact your insurance needs and ensure continued compliance.

Should You Consider Additional Insurance?

Contractors should consider additional coverage types to fill in gaps left by contractor liability insurance. One such type is professional liability insurance, which covers errors and omissions claims related to professional services. Additionally, workers’ compensation insurance is vital to cover employee injuries on the job.

Other considerations may include commercial auto insurance if vehicles are used for business purposes and equipment insurance to protect tools and machinery from loss or damage. Evaluating these complementary insurance policies ensures that your business has a robust protection strategy in place.

Wrapping Up the Essentials of Contractor Liability Insurance

While contractor liability insurance provides essential protection, it’s crucial to understand its limitations and augment it with other types of coverage for comprehensive risk management. By staying informed and consulting with insurance professionals, contractors can ensure they have the right coverage to protect their business.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com
What Risks Do Scaffolding Projects Face Without Proper Labor Law Coverage?

Scaffolding is a critical component in construction projects, providing workers with the means to reach high places safely. However, failure to secure proper labor law coverage can lead to significant risks and challenges. In this FAQ, we will explore the potential dangers that scaffolding projects may face without this essential coverage and how to mitigate these risks effectively.

Two construction workers on bamboo scaffolding, wearing safety gear under a clear blue sky.

Understanding Scaffolding Risks

Scaffolding involves working at heights, which inherently carries a range of risks such as falls, equipment failure, and structural instability. Identifying these risks is the first step towards ensuring safety on your construction site.

Working at such altitudes means that small mistakes can lead to serious injuries. For example, even a minor miscalculation in the setup of scaffolding can cause significant accidents. Safety nets, guardrails, and proper personal protective equipment (PPE) are simple yet effective measures to reduce these risks. Ensuring all workers are trained in safety procedures can dramatically diminish the chances of mishaps.

Weather conditions also play a crucial role in scaffolding safety. High winds, rain, and ice can increase the likelihood of accidents. Monitoring weather forecasts closely and adjusting the work schedule accordingly can help mitigate these risks. Furthermore, regularly inspecting scaffolding structures for stability and any wear-and-tear can prevent accidents before they occur.

The Importance of Labor Law Coverage

Labor law coverage provides vital protection for workers, covering injuries and accidents. Without it, scaffolding projects may face severe penalties and financial liabilities in the event of an incident.

In New York, specific regulations, such as the Scaffold Law, impose strict liability on employers for elevation-related injuries. This means that if a worker is injured due to falls or scaffolding failures, the employer could face substantial financial penalties. Thus, having appropriate labor law coverage is not just about fulfilling a legal obligation but also about protecting the financial integrity of your business.

Benefit from reduced insurance premiums by maintaining a record of safety and comprehensive coverage. Insurance companies factor in these elements when determining premiums. As such, a proactive approach to labor law compliance can lead to significant cost savings and fewer disputes with insurers.

Consequences of Inadequate Coverage

Without proper coverage, projects run the risk of halted progress due to legal disputes, increased insurance premiums, and potential lawsuits from injured workers.

Beyond immediate financial strains, inadequate coverage can severely harm a company’s reputation. Prospective clients often scrutinize a company’s safety record and compliance history before awarding contracts. A track record marred by legal issues and worker injuries due to insufficient coverage can deter clients, thus affecting business prospects substantially.

Ultimately, failing to secure proper labor law coverage can escalate accidents into complex legal entanglements. Navigating these legal challenges not only diverts attention from core business functions but also drains resources that could otherwise be invested in more productive avenues of the project.

How to Secure Proper Labor Law Coverage

To mitigate risks, understand the specific labor laws applicable in New York for scaffolding and falls. Consult with insurance professionals to find comprehensive coverage that meets legal requirements and protects your workforce.

Begin by assessing your current coverage and identifying any gaps that leave your projects exposed to legal and financial penalties. An assessment should involve a thorough examination of both general liability insurance and workers’ compensation packages to ensure they align with the New York State regulations

Engage with trusted insurance brokers who specialize in construction and scaffolding projects. Their expertise can provide tailored coverage options, assisting you in navigating the nuances of New York labor law.

Finally, continuously educating your workforce on safety protocols and labor laws keeps them informed and compliant. Scheduling regular workshops and training sessions helps in creating a culture of safety and accountability, further reinforcing your commitment to a secure work environment.

Safeguard Your Scaffolding Projects with Proper Coverage

Ensuring proper labor law coverage for scaffolding projects in New York is crucial for protecting both workers and project success. By understanding the potential risks and taking proactive measures, you can create a safer and more efficient construction environment. Don’t overlook the importance of comprehensive coverage—it’s a vital step in safeguarding your projects from unnecessary liabilities. For more detailed information and assistance on labor law coverage, visit our homepage for expert guidance.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com


Understanding Scaffolding Insurance: A Contractor’s Guide

Navigating the world of insurance can be daunting, especially for contractors who are dealing with unique risks every day. One important aspect of coverage often overlooked is scaffolding insurance. In this guide, we’ll break down what scaffolding insurance is, why it’s vital for your business, and how to choose the right policy to keep your projects protected.

Detailed view of a construction site scaffolding structure and ladder against a bright blue sky.

What is Scaffolding Insurance?

Scaffolding insurance is specialized coverage tailored for businesses involved in scaffolding work. It encompasses various risks associated with erecting and dismantling scaffolding, ensuring that contractors are protected against potential accidents or damages.

Scaffolding is a fundamental component of many construction projects, providing the necessary height and support for workers. However, with its advantages come certain risks. As scaffolding structures can vary in complexity and size, they present specific challenges. Scaffolding insurance is designed to mitigate these risks by offering comprehensive coverage that protects against potential legal liabilities and losses. It’s essential for contractors to understand how scaffolding safety standards evolve and how policies can adapt to these changes, ensuring ongoing compliance and protection.

Beyond the general understanding of scaffolding insurance, it’s crucial to delve into what it truly means for contractors. This coverage isn’t just about ticking a box; it’s about safeguarding the future of your business. From unexpected structural failures to accidental damage caused near or on scaffolding, having a well-rounded insurance policy ensures peace of mind. It’s this kind of specialized insurance that allows you to focus on your primary business operations, knowing you’re protected against the nuances of scaffolding liabilities.

The Importance of Scaffolding Insurance for Contractors

In the construction industry, scaffolding plays a critical role, but it also introduces unique hazards. Scaffolding insurance provides essential protection for your business, mitigating the risks of liability from accidents, property damage, or even worker injuries.

Scaffolding is more than just a temporary structure; it is a lifeline for many construction projects, providing access and safety for workers performing tasks at various heights. However, the inherent risks that come with scaffolding cannot be overlooked. Accidents can lead to severe injuries, resulting in costly medical bills and legal fees. By investing in scaffolding insurance, contractors not only protect their financial interests but also demonstrate a commitment to the safety and well-being of their employees. It’s a strategic move that underscores the importance of risk management across the project lifespan.

Moreover, scaffolding insurance is an essential aspect of comprehensive construction risk management. It creates a safety net that allows contractors to navigate unforeseen challenges without the fear of detrimental financial impacts. In essence, this insurance is an investment in the reliability and credibility of your construction firm, offering clients added reassurance which can distinguish your business in a competitive market.

Key Coverage Areas of Scaffolding Insurance

A typical scaffolding insurance policy covers several areas including public liability, employer’s liability, and coverage for equipment damage. Understanding these coverage areas helps in selecting a policy that best meets the needs of your business.

Public liability coverage is essential for protecting against claims of injury or damage caused by your scaffolding operations to third parties. This aspect of the insurance ensures you can address any legal claims without the fear of jeopardizing your business finances. On the other hand, employer’s liability coverage is compulsory, protecting you against claims from employees who might suffer injury or illness as a result of their work. It’s vital to clearly understand how each of these areas impacts your overall business risk profile and operations.

Additionally, equipment damage coverage protects against the costs associated with repairing or replacing damaged scaffolding. Issues such as adverse weather conditions or accidental damage during handling are unpredictable, but if covered by insurance, they don’t have to be financially debilitating. To build a comprehensive safety net, consider these coverage areas in piecing together a robust business protection strategy that aligns perfectly with your operational needs.

How to Choose the Right Scaffolding Insurance Policy

Choosing the right scaffolding insurance involves evaluating your business needs, assessing the risks specific to your operations, and comparing different insurers. Consider factors such as coverage limits, exclusions, and the insurer’s reputation.

Start by identifying the unique risks associated with your scaffolding projects. Every construction site is different, and understanding these specific risks can help tailor your insurance policy to offer maximum coverage. Next, compare the offerings of various insurers. Look into their reputations, customer service quality, and reviews from other contractors. It’s about finding more than just a policy; it’s about forming a partnership with a provider that understands the intricacies of your industry and can respond adeptly to claims when needed.

Additionally, don’t overlook the importance of reviewing policy exclusions and endorsements. These can significantly affect your coverage. Customization is key—while some standardized policies may seem easier to manage, adjusting them to better reflect your business’s operations and risks often results in better security and potentially lower costs over time.

Tips for Lowering Your Scaffolding Insurance Premiums

Reducing insurance costs without sacrificing coverage can significantly benefit your bottom line. Implementing safety measures, maintaining rigorous safety training, and having a good claims history are effective ways to lower your premiums.

One practical approach to reducing premiums is to enhance the safety protocols on your site. Regular safety audits and compliance checks can significantly minimize risk and, in turn, premiums. Investing in quality materials for scaffolding and ensuring all equipment undergoes regular inspections not only offers peace of mind but also demonstrates a commitment to high safety standards, often rewarded by insurers.

Another strategy is bundling your insurance policies. Many insurers offer discounts for businesses that purchase multiple types of coverage. By consolidating your insurance needs with one provider, you may benefit from lower premiums and have a single point of contact for all your insurance needs. Also, consider raising deductibles carefully; while this reduces the premium, make sure it’s within a manageable range so as not to strain your resources in case of a claim.

Securing Your Construction Future with Scaffolding Insurance

Scaffolding insurance is not just an optional extra; it’s a crucial component of risk management for contractors. By understanding the essentials and selecting the right coverage, you can safeguard your business, protect your team, and ensure a smoother operation on-site. Don’t leave your business vulnerable—invest in the right scaffolding insurance today to build a more secure future. For more information on how we can assist you in securing your business’s future, visit our homepage.

About BGES Group

Running a business is challenging enough without having to spend valuable time dealing with insurance issues. At BGES Group, we make insurance simple by providing responsive, personalized service and helping you secure the right coverage at competitive rates. With more than 45 years of industry experience and access to over 25 top-rated insurance carriers, we take the time to understand your business and design insurance solutions that protect your company, employees, assets, and future—without paying for coverage you don’t need.

Our clients appreciate having one dedicated insurance professional, fast certificate processing, prompt answers, and direct access to a real person when they call. We proactively solve problems before they become costly, help control insurance expenses, and provide expert guidance on Workers’ Compensation, General Liability, Commercial Auto, Umbrella Liability, and other business insurance needs. Our goal is simple: make insurance one less thing for you to worry about while providing the peace of mind that comes from knowing an experienced professional is looking out for your business.

Contact BGES Group Insurance Services

Gary Wallach, President
Licensed in New York, New Jersey & Connecticut

📞 (914) 806-5853
✉️ bgesgroup@gmail.com
🌐 www.bgesgroup.com


When a Jobsite Injury Becomes a Lawsuit: New York Labor Law and Contractor Liability Insurance

New York contractors face more than the ordinary risks of construction. If a worker is injured, state Labor Law may allow claims against property owners, general contractors and other parties involved in a project—even when they did not directly supervise the work. The resulting lawsuit can raise questions about who is legally responsible and whether each party’s insurance policy will respond.

Understanding the connection between New York Labor Law and contractor liability insurance can help contractors ask better questions before a project starts and at renewal. The details depend on the facts of an accident, the contract and the policy wording, so contractors should review their situation with qualified legal and insurance professionals.

What Labor Law Sections 240 and 241 cover

New York Labor Law § 240(1) is commonly called the “Scaffold Law.” It addresses certain elevation-related hazards in activities such as construction, demolition, repair, alteration, painting, cleaning and pointing. The law requires covered owners, contractors and their agents to provide or arrange for specified safety devices—such as scaffolds, ladders, hoists and braces—to protect workers. It includes an exception for certain owners of one- and two-family homes who do not direct or control the work. New York Labor Law § 240

New York Labor Law § 241(6) concerns reasonable and adequate protection for workers in construction, demolition and excavation. A claim under this section generally relies on an applicable provision of the New York Industrial Code. Courts have explained that the cited rule must provide a sufficiently specific standard and apply to the circumstances of the accident. New York Court of Claims discussion of § 241(6)

These laws can create significant liability exposure for parties named in a lawsuit. New York courts have described duties under these sections as nondelegable in relevant circumstances: a contractor or owner may face a claim even if it did not directly supervise the specific work involved. The legal outcome depends on the facts and applicable law. New York Court of Appeals discussion

That is why the insurance question deserves careful attention. A contractor may have a general liability policy, but the policy’s name or headline limit alone does not tell you whether a particular lawsuit is covered.

Why the policy wording matters

Commercial general liability insurance can provide defense and indemnity for covered claims, subject to the policy’s terms, limits, exclusions and conditions. A Labor Law claim does not automatically mean a policy will pay—or that it will not. Contractors need to review the actual policy and endorsements.

Pay particular attention to exclusions and limitations that may affect construction work or injury claims. Depending on the policy, these might include construction-operation restrictions, employee injury or “action-over” exclusions, or other wording that limits coverage. “Action-over” commonly refers to a situation in which an injured worker sues a party other than their direct employer, and that party seeks coverage or indemnity from another contractor or subcontractor. The phrase alone does not determine coverage; the specific facts and policy language matter.

Contractors should also check how their umbrella or excess policy interacts with the primary general liability policy. Do not assume that an umbrella automatically fills a gap in the underlying coverage. Ask the broker to explain whether the umbrella follows the relevant terms and exclusions, and what limits may be available for the risks involved.

Five Google searches contractors may use

Contractors researching this topic often search phrases such as:

  • “New York Labor Law 240 insurance coverage for contractors”
  • “New York Labor Law 241 contractor liability insurance”
  • “New York action over exclusion general liability policy”
  • “Does general liability insurance cover Scaffold Law claims in NY?”
  • “NY contractor insurance Labor Law 240 241 exclusions”

These searches are a useful starting point, but no search result can confirm how a specific claim or policy will be treated. The answer requires examining the policy forms, endorsements, project contract and circumstances.

What contractors should ask their broker

At renewal—and before beginning a project—contractors can ask their broker to review:

  1. Whether the policy’s description of operations matches the work performed. New trades, project types, payroll or subcontracting arrangements may affect underwriting and coverage.
  2. Which exclusions may apply to the contractor’s operations. Ask for the relevant endorsement and a plain-language explanation, especially where employee injuries, subcontractors, construction activities or action-over claims may be involved.
  3. How the policy responds to contractual requirements. Owners and general contractors may request additional insured status, primary and noncontributory wording, waivers of subrogation or specific limits. The broker should compare the request with the actual policy and endorsements.
  4. How the umbrella or excess policy interacts with the primary policy. Review its limits and terms rather than assuming it provides identical or broader protection.
  5. What documentation and risk controls should be maintained. Keep contracts, certificates, payroll records, subcontractor insurance documentation and jobsite safety records organized. These records do not guarantee coverage or determine legal responsibility, but they can be important when questions arise.

A good broker should help the contractor understand the policy, identify issues to discuss with the insurer, and coordinate documentation. The broker does not replace legal counsel or guarantee a particular outcome, but informed review can help contractors make decisions with a clearer understanding of the coverage they are buying.

How BGES Group can help contractors review coverage

BGES Group specializes in construction insurance and serves contractors in New York and the surrounding region. The agency describes its approach as personalized and hands-on, with Gary Wallach as a direct point of contact. Its website says BGES Group reviews contractors’ operations, discusses tailored coverage options, shops accounts with insurance providers and helps clients understand policy terms, conditions and exclusions. BGES Group About BGES Group

For contractors concerned about Labor Law exposure, a focused review can help identify questions about exclusions, limits, project requirements and how primary and umbrella policies fit together. BGES Group’s stated service model emphasizes direct communication and continuity with a professional familiar with the account—an alternative for contractors who prefer a personal relationship over a high-volume, factory-like service experience.

No broker can promise that every claim will be covered or that every requested term will be available. Contractors should ask for clear explanations, review policy documents carefully and consult legal counsel about their specific obligations and exposure.

Contact BGES Group

Gary Wallach
Phone: 914-806-5853
Email: bgesgroup@gmail.com
Website: www.bgesgroup.com

This article provides general information, not legal or insurance advice. Coverage depends on policy wording, endorsements, facts and applicable law.

The Renewal Test: 5 Things Every New York Contractor Should Expect From an Insurance Broker

When your contractor insurance renewal arrives, it’s tempting to focus on one question: How much will it cost? Price matters, but it’s only one part of a good insurance decision.

Contractors also need coverage that fits the work they do, clear answers about exclusions, help with certificates and contracts, and an agency that responds when a job is waiting. A renewal is a good time to ask whether your broker is providing the service and guidance your business needs.

Here are five things New York contractors should look for when renewing their business insurance—and how BGES Group says it works to deliver them.

1. A broker who understands your kind of work

Construction insurance is not one-size-fits-all. The needs of an electrician may differ from those of a roofer, demolition contractor, remodeler or general contractor. A broker who understands construction should ask about the work you perform, the projects you take on, your employees and subcontractors, your equipment, and any changes to the business since the last renewal.

That conversation helps the broker assess whether the policy information still reflects your operations. If your work has changed, your insurance may need a closer review. If a project contract has specific requirements, those should be part of the discussion too.

New York contractors may also need to maintain workers’ compensation and disability benefits coverage, depending on their circumstances. Some permits, licenses and contracts require proof of coverage. For example, New York City lists general liability, workers’ compensation and disability benefits requirements for certain contractor permits. Contractors should confirm the requirements that apply to their specific work and location. NYC Department of Buildings contractor insurance requirements

BGES Group describes itself as a construction insurance specialist serving contractors in New York, New Jersey and Connecticut. Its website says it reviews a contractor’s work, company size and potential liabilities when considering coverage. That kind of industry focus can make renewal discussions more relevant to the actual business behind the policy. About BGES Group

2. A broker you can trust to put your interests first

Contractors want an insurance broker who takes their questions seriously and gives them a fair picture of their options. That means explaining the renewal, being open about what is known and what needs to be checked, and following up when an answer isn’t immediately available.

Trust also means having a broker who is willing to talk through difficult situations: a steep premium increase, a confusing audit, a claim question, a non-renewal notice or a concern about whether a contract requirement is met. Contractors should not feel they have to accept a recommendation without understanding the reasoning behind it.

The broker’s role is to help the contractor understand available insurance choices and communicate with insurers. The policy itself is issued by an insurer, and coverage depends on its actual terms and conditions. A good broker helps the contractor ask informed questions and understand the choices before deciding.

BGES Group presents its service as hands-on, with Gary Wallach as a direct contact for clients. The agency’s website highlights personalized attention and continuity with the same professional over time. For a contractor, that can mean building a working relationship with someone who becomes familiar with the company’s history and priorities, rather than starting from scratch at each renewal. About BGES Group

3. The right coverage, a competitive price and a careful look at exclusions

A low premium is not enough if the policy does not fit the work or leaves important questions unanswered. Contractors should review the coverage being offered, compare it with the expiring policy and ask what has changed.

That review may include general liability, workers’ compensation, disability benefits, commercial auto, umbrella coverage, tools and equipment, builders risk or other policies relevant to the business. The right combination depends on the contractor’s operations, contracts and risk profile.

Exclusions deserve particular attention. Ask your broker which exclusions or restrictions might matter for your work. Depending on the policy, it may be useful to discuss limitations related to specific trades, subcontractors, heights, roofing, completed operations or other activities. Policy wording varies, so contractors should review their own documents rather than assume a particular exposure is covered.

Price should be part of the conversation, too. Ask what factors affected the renewal premium and whether the broker can explore other suitable markets. If alternatives are available, compare more than the price: check limits, deductibles, exclusions, endorsements and other conditions. BGES Group says it works with multiple insurance providers and compares quotes to help contractors pursue competitive pricing while considering their coverage needs. About BGES Group

The goal is to understand what you are buying, what it costs and where the policy may have limitations. A broker should help make those details easier to evaluate.

4. An agency that gets certificates and time-sensitive work done

A certificate of insurance request can be urgent when a contractor needs to meet a client’s requirement or get onto a job. Contractors want an agency that responds promptly, understands what is being requested and helps coordinate the appropriate documentation.

The same applies to questions about additional insured status, policy limits or contract wording. A certificate provides evidence of insurance, but it does not change the policy. If a contract calls for a specific endorsement, ask the broker to review the request against the policy and explain what documentation may be needed.

Responsiveness is about more than certificates. Contractors also need timely help with quote follow-ups, audit questions, claims communications and changes to their policies. They want a person to answer the phone, give a clear response and take ownership of what needs to happen next.

BGES Group emphasizes direct access and ongoing guidance as part of its service approach. The agency says it assists clients with policy terms, conditions and exclusions, and with navigating the claims process. For contractors, those services matter most when a deadline is near or an issue is disrupting the workday. About BGES Group

5. A consistent person who knows your account

Contractors often prefer to work with someone who already knows their business. A familiar contact can understand why a certificate is urgent, remember what was discussed at renewal and recognize when a change in operations needs attention.

Some contractors say that after an agency is acquired, service can feel more standardized: more handoffs, less continuity and fewer chances to speak directly with someone familiar with the account. Experiences differ across agencies, but contractors who value personal service may prefer a broker with a more direct, consistent approach.

BGES Group positions itself as the alternative to a factory-like service experience. Its website says clients work directly with Gary Wallach and highlights his construction insurance experience, personalized service and attention to detail. It also describes a risk review tailored to each contractor’s operations, coverage options arranged through its insurance-provider relationships, and ongoing guidance. Those are concrete qualities contractors can ask about when deciding whether an agency is right for them.

No agency can promise that every request will be resolved instantly or that every coverage option will be available. But contractors can reasonably expect communication, informed guidance and follow-through. In BGES Group’s case, its stated focus is to combine construction insurance knowledge with a direct relationship—so clients have a person to call who can learn their account and help move the work forward.

Make your renewal a conversation

Before renewing, gather information about your current work, payroll, vehicles, equipment, subcontractors and upcoming contracts. Ask what changed in the renewal, which exclusions to review, whether alternative quotes are available and who you can contact when you need help. The answers can tell you whether your broker is offering the service your business needs.

BGES Group says it aims to provide New York contractors with the combination many are looking for: construction insurance experience, tailored coverage discussions, competitive options, personal attention and a consistent point of contact.

Contact BGES Group

Gary Wallach
Phone: 914-806-5853
Email: bgesgroup@gmail.com
Website: www.bgesgroup.com

Insurance availability, policy terms and legal requirements vary. Review your policy and contract requirements with your broker, and confirm applicable rules with the relevant government agency.