10 Reasons NY, NJ & CT Contractors Should Call BGES Group When Workers Comp Becomes a Headache

When you run a contracting business in New York, New Jersey, or Connecticut, there’s one insurance policy that can make or break your operation — workers’ compensation. It’s mandatory, expensive, and often misunderstood. Many contractors find themselves dealing with constant premium hikes, audits that never seem to end, and brokers who vanish once the policy is bound.

If this sounds familiar, you’re not alone — and you don’t have to settle for it. For over 44 years, BGES Group, led by Gary Wallach, has been the go-to insurance resource for contractors facing tough workers compensation challenges. Whether you’ve been canceled, your experience modification (mod) has skyrocketed, or you’re just tired of being treated like a number, BGES Group specializes in fixing tough situations quickly, personally, and professionally.

Here are 10 reasons why contractors across NY, NJ, and CT should turn to BGES Group when they’re having problems with their workers comp coverage.


1. Fast Turnaround When You’re in a Bind

Many contractors call BGES Group when they’re in panic mode — maybe their policy was non-renewed, their coverage lapsed, or a general contractor is withholding payment until they show proof of insurance. BGES Group has access to multiple markets and can often get new workers comp coverage issued in 24–48 hours. They act fast, communicate clearly, and get you back to work without missing a beat.


2. Expertise in High-Risk Contractor Classes

Not every insurance broker understands the complexities of construction. Roofing, masonry, flooring, concrete, demolition, or carpentry — these trades are often seen as “high-risk” by most carriers. BGES Group specializes in these classes and knows exactly which companies are open to them, what paperwork is needed, and how to structure your policy so you’re properly covered and compliant.


3. Help for Companies with Claims or Cancellations

If your policy was canceled or your claims history is hurting your renewal options, most brokers will tell you “there’s nothing we can do.” BGES Group says otherwise. Gary and his team regularly help contractors with prior claims, large losses, or even open claims find coverage again. They don’t judge — they find solutions.


4. Fair Premiums and No Hidden Surprises

One of the biggest complaints contractors have is overpaying for workers comp. BGES Group reviews your class codes, payroll estimates, and subcontractor costs to make sure everything is accurate. Many contractors discover they were being overcharged thousands of dollars simply because their prior broker didn’t review details or file corrections.

With BGES Group, you get honest, transparent pricing — and an agent who explains where every dollar goes.


5. Personalized Service — You Deal Directly with the Owner

When you work with BGES Group, you’re not bounced around a call center. You deal directly with Gary Wallach, a broker with over four decades of experience in contractor insurance. Gary is hands-on, responsive, and reachable — even after hours. Contractors often say he’s the most attentive, reliable, and knowledgeable broker they’ve ever worked with.


6. Help Managing Subcontractor Insurance Compliance

One of the biggest workers comp headaches comes from subcontractors. If their insurance isn’t correct, your audit can blow up and cost you thousands. BGES Group provides custom subcontractor insurance checklists, cover letters, and review services to help make sure your subs’ coverage meets your requirements. Gary personally reviews their certificates and endorsements so you’re not left holding the bag at audit time.


7. Audit Assistance That Saves You Money

Workers comp audits can be confusing — and they often result in surprise bills. BGES Group doesn’t just sell you a policy and disappear. They’ll help you prepare for and review your audit, making sure payroll classifications, subcontractor documentation, and other details are accurate. Many clients save significant amounts because BGES Group catches errors the auditor missed.


8. Exclusive Access to Top Workers Comp Programs

BGES Group works with specialized insurance carriers that most local agencies can’t access. These programs are designed specifically for contractors and often include more flexible underwriting, better payment plans, and fewer restrictions. Whether you’re a small start-up or a large established contractor, BGES Group can match you with the right fit.


9. Additional Coverage Expertise — Beyond Workers Comp

While workers compensation may be your immediate concern, BGES Group can also review and improve your entire insurance program — general liability, umbrella, commercial auto, and bonds. They’ll make sure all your coverages work together, no exclusions overlap, and your certificates meet your GC or building owner’s requirements. That means fewer delays, fewer rejections, and fewer compliance headaches.


10. Proven Track Record and Long-Term Relationships

BGES Group has been helping contractors in the tri-state area for decades. Many clients have stayed with them for 10, 20, even 30 years — not because they’re the cheapest every single year, but because they deliver real value, personal service, and unmatched expertise.

Gary and his team believe insurance is a partnership, not a transaction. They take the time to understand your business, find solutions that make sense, and are always available when problems come up.


Bonus: They Actually Care

It’s rare today to find a broker who treats you like family, but that’s exactly how BGES Group operates. Whether you need a certificate on a Saturday, advice about hiring, or help handling a claim, you’ll get real human support — not a 1-800 number or chatbot.


Final Thoughts: Stop Struggling — Get the Help You Deserve

If your workers comp situation has become a constant source of stress, don’t wait until your policy is canceled or your GC refuses to pay. A five-minute call with BGES Group could save your business time, money, and frustration.

They’ll help you:
✅ Get insured quickly, even if you’ve been canceled or declined.
✅ Pay fair premiums that match your true risk.
✅ Avoid costly audit surprises.
✅ Stay compliant with your GCs and clients.
✅ Gain a partner who truly has your back.


Contact BGES Group Today

BGES Group
Contractor Insurance Specialists – Serving NY, NJ & CT
📞 Call/Text: (914) 806-5853
📧 Email: bgesgroup@gmail.com
🌐 Website: www.bgesgroup.com

When workers comp becomes a problem, BGES Group is the solution.
Personal service. Expert advice. Real results. Every time.
What is Residential Contractor Insurance and Why Do You Need It?

If you’re navigating the world of construction, you may have heard about residential contractor insurance. But what exactly is it, and why is it crucial for your business? This blog will unpack the essentials of residential contractor insurance and explain why it’s a must-have for contractors.

A room prepared for renovation with a ladder, paint supplies, and drop cloth.

Understanding Residential Contractor Insurance

Residential contractor insurance is a type of coverage specifically designed for professionals in the construction of residential buildings. This insurance typically includes several types of coverage to protect against potential risks encountered on the job.

Understanding the requirements and benefits of residential contractor insurance can seem daunting, but it is essentially a lifeline for contractors. Acting as a safety net, it shields business owners from a plethora of unforeseen liabilities. This means that whether a simple mishap occurs or a considerable disaster strikes, you’re covered. The peace of mind that comes with knowing your business and assets have robust protection is invaluable.

For contractors, understanding the specifics of their insurance policy is paramount. Knowing what coverage applies in specific scenarios prevents unexpected out-of-pocket expenses. For example, general liability contributes significantly to safeguarding a contractor’s operations by covering third-party claims, whether of injuries or property damage. It ensures that you focus more on the construction and less on financial anxieties.

Types of Coverage Included

Generally, residential contractor insurance policies cover general liability, workers’ compensation, commercial auto insurance, and more. Each type serves a specific purpose to address various incidents that may arise during construction projects.

While general liability and workers’ compensation are frequently discussed, understanding the nuances of additional coverage options could be worthwhile. Commercial auto insurance is pivotal for businesses employing vehicles for work purposes. Additionally, other forms such as tools and equipment insurance can protect an often overlooked category—contractors’ valuable instruments and machinery that are crucial for day-to-day functions.

An important yet lesser-known part of the insurance is known as ‘errors and omissions’ coverage, which provides protection against claims related to negligence, misrepresentation, or violation of good faith. Contractors should harbor a keen understanding of E&O coverage nuances. This facet can be indispensable in safeguarding the small details that might be overlooked during projects but hold significant value.

Why You Need Residential Contractor Insurance

Having this insurance is crucial as it protects your business from financial losses due to accidents, damages, or legal claims. Moreover, it’s often a requirement for legal compliance and project contracts.

Imagine you’re midway through a construction project and an unforeseen accident results in significant damage or injury. Without insurance, the financial repercussions could be crippling. Contractor insurance ensures these liabilities do not fall directly upon your business, allowing you to navigate through such challenges much more gracefully.

Notably, this insurance not only accommodates legal compliance but enhances your reliability as a contractor. The assurance provided can be quite persuasive to prospective clients, as it demonstrates due diligence and preparedness. It echoes the contractor’s commitment to safety and professionalism, which are key attributes clients look for when hiring services for their homes.

Choosing the Right Insurance for Your Business

Selecting the right insurance policy involves assessing your business’s unique needs, comparing coverage options, and often consulting with an insurance broker. This ensures you have adequate protection tailored to your specific operational risks.

An effective strategy is to partner with experienced brokers who understand the intricacies of the contractor industry. This relationship helps in navigating complex policies and negotiating terms that best suit your business. Consider seeking guidance for identifying the most pertinent coverage that aligns with your risk profile.

Remember, the cheapest policy isn’t always the best choice. You should evaluate the extent of coverage and the reputation of the insurer. A smart choice will balance cost-effectiveness with comprehensive protection, ensuring you and your team can operate confidently with minimal exposure to costly pitfalls.

Why Residential Contractor Insurance is Essential

In summary, residential contractor insurance is not just a legal necessity, but a critical safeguard for your business. It provides financial protection, ensures compliance with laws, and builds trust with clients. Investing in the right coverage can save you from costly mishaps and provide peace of mind as you focus on crafting beautiful, safe homes. Check out more about our services at BGES Group.

BGES Group is one of New York, New Jersey, and Connecticut’s Construction Insurance Specialists representing 50+ companies, including all the BEST general & umbrella liability programs. We offer all the coverage needed, including property, builders’ risk, inland marine, general liability, umbrella liability, auto, bid & performance bonds, workers’ compensation, N.Y.S. disability, and group health.  Our commitment to you goes beyond the policies we provide. We are always just a call, text, or email away, ready to assist you, even on weekends. We understand the importance of your business and are here to help you navigate any insurance challenges. 
 
BGES Group are Workers’ Compensation Insurance Specialists for Tri-State Business Owners: Unhappy with your rates, company, being canceled, losses causing difficulty getting coverage, in the middle of an audit dispute, misclassified payrolls, or whatever your issue. We can help!  We have special programs for Auto Services, Contractors (especially in New York), Limousine Services, Logistics Companies, Manufacturers, Recyclers, and Truckers; we can help ANY tri-state business owner. We are considered “Preferred Agents” for this one program that, if we can get you into, their pricing is excellent, offers long-term coverage stability, and can cover multi-state operations. The program takes the hassle out of doing annual audits, too. 
 
If you want to speak with us, call Gary Wallach at 914-806-5853, click here to email, or visit our website.
 
Company: BGES Group, 216A Larchmont Acres West, Larchmont, NY 10538

email: bgesgroup@gmail.com

website: http://www.bgesgroup.com


Who Covers the Building While It’s Being Built? What Every New York Contractor Must Know

If you’re a New York general contractor, chances are you’ve faced this question more than once: Who insures the building while it’s under construction? It may sound simple, but it’s one of the most misunderstood areas of construction risk management. Whether you’re building a new home, remodeling an existing structure, or adding an addition, the answer depends on who owns the project at each stage and what agreements are in place.

Let’s break it down—step by step.

⸻

Scenario 1: You’re a General Contractor Building a New Home You Own

In this scenario, you’re not just the builder—you’re also the owner. You purchased the land, you’re financing the construction, and you plan to sell or occupy the finished property. That means you are responsible for insuring the building while it’s being built.

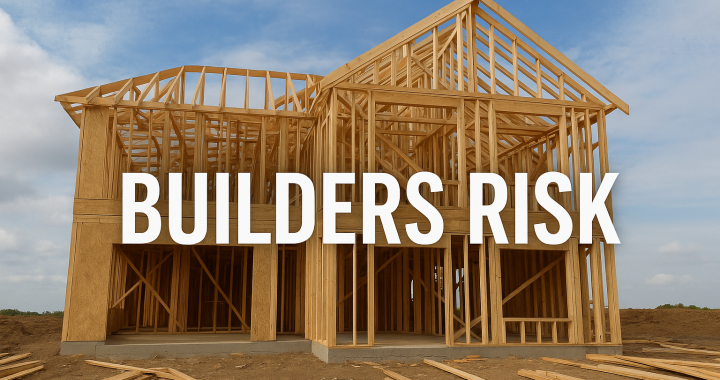
The correct policy for this is a Builders Risk Policy, sometimes called a “Course of Construction” policy. It’s designed to protect your investment from losses during construction.

A Builders Risk Policy covers:

• Fire, theft, vandalism, or wind damage to the structure while under construction

• Building materials on-site, in transit, or temporarily stored off-site

• Temporary structures (fencing, scaffolding, etc.)

• Sometimes, soft costs like permits, architectural fees, or lost interest due to delays from covered losses

What it doesn’t cover:

• Liability for injuries to others (that’s under your General Liability policy)

• Workers injuries (that’s covered by Workers’ Compensation)

• Faulty workmanship (that’s your responsibility, not an insurable event)

So if you’re both the owner and builder, you buy the Builders Risk policy in your own name. The moment the structure is complete and you obtain a Certificate of Occupancy, you can switch to a permanent property policy—homeowners insurance, landlord insurance, or commercial property insurance, depending on the project’s intent.

⸻

Scenario 2: You’re a General Contractor Hired by a Homeowner

Now let’s flip it. You’re hired by a homeowner to build their new house. You’re not the owner—your client is. So who covers the building while it’s being built?

In almost all cases, the owner should purchase the Builders Risk Policy. Why? Because the owner has the insurable interest in the property. If the home burns down halfway through construction, the owner loses the value of what’s been built so far—not the general contractor.

However, this is where things can get messy if it’s not spelled out clearly in the contract. If there’s no mention of builders risk insurance, and the owner doesn’t buy it, you could be facing disputes and delays in the event of damage or loss.

To protect yourself as a general contractor:

1. Address builders risk insurance in your contract. State who is responsible for providing it—typically the owner.

2. Request to be named as an additional insured and loss payee. That way, if a covered loss occurs, your interests are protected as well.

3. Verify coverage before work begins. Don’t rely on verbal assurances. Ask for a copy of the policy or a certificate of insurance.

If the homeowner refuses to carry builders risk, some contractors will choose to buy it themselves to protect their work and materials. In that case, you’d list yourself as the insured party and the homeowner as an additional insured.

Bottom line: someone must carry builders risk—either the owner or the GC. Don’t start work without confirming who it is.

Article content

Scenario 3: You’re Building an Addition to an Existing Structure

Now imagine you’re hired to add a new section onto an existing home or commercial building. A kitchen extension, a second story, or a new office wing—whatever the project, you’re working on property that already exists and is likely insured.

In this case, the owner should contact their property insurance company before construction begins. They’ll need to ask whether their existing policy will extend to cover the new addition while it’s being built.

Often, standard homeowners or commercial property policies do not automatically cover structures under renovation or expansion. That’s why most insurance agents will recommend either:

• Adding a Builders Risk Endorsement to the existing policy, or

• Purchasing a separate Builders Risk Policy just for the addition

In some situations, the general contractor might again step in and buy the builders risk policy, especially if the owner is inexperienced or doesn’t have proper insurance guidance.

A good rule of thumb:

• If you’re working on someone else’s building, the owner should carry builders risk.

• If you’re building on your own land, you carry builders risk.

As a contractor, you should always confirm these details in writing before breaking ground.

⸻

Why Builders Risk Coverage Matters

Builders risk coverage can mean the difference between a minor setback and financial disaster. Imagine this: you’re halfway through framing a new home when a windstorm rips through and destroys $100,000 worth of materials. Without builders risk coverage, someone—either you or the owner—will be paying that out of pocket.

Even worse, it could lead to lawsuits, delays, and ruined relationships. Proper builders risk insurance ensures that the project continues smoothly after a covered loss.

It’s also worth noting that lenders usually require it if there’s a construction loan. The bank wants to protect its financial interest just as much as you do.

⸻

What About Renovations and Remodeling?

For remodeling jobs that don’t involve major structural work, the owner’s existing homeowner or commercial policy may offer limited coverage. However, policies vary widely. For example, if walls are opened up, roofs removed, or structural changes made, many insurers will refuse to cover the work in progress unless a builders risk endorsement is added.

So again, communication is key. Both the owner and contractor should consult with their insurance professionals before starting the job.

⸻

BGES Group: Protecting New York Contractors

At BGES Group, we specialize in insuring New York contractors. Whether you’re a general contractor, subcontractor, or construction manager, we help you identify coverage gaps before they become costly mistakes.

We work with all major insurance carriers that understand the complexities of New York’s construction laws and insurance requirements—including labor law exposures, action-over claims, and contractual risk transfer.

Our team can help you secure:

• General Liability and Workers’ Compensation

• Builders Risk and Installation Floater policies

• Umbrella and Excess Liability coverage

• Certificates of Insurance and contract compliance reviews

We don’t just sell policies—we help contractors protect their businesses and win more jobs by making sure their insurance meets project and lender requirements.

⸻

Final Thoughts

Builders risk insurance isn’t a luxury—it’s a necessity. Whether you’re the owner, the general contractor, or both, understanding who is responsible for covering the building during construction can save you thousands of dollars and countless headaches.

Before the first shovel hits the ground, make sure one question is answered: Who’s insuring the project?

If you’re not sure, BGES Group can help. We’ll review your project details, determine what coverage you need, and make sure you’re fully protected from start to finish.

⸻

Contact BGES Group

Specialists in Insuring New York Contractors

📞 Gary Wallach: 914-806-5853

📧 bgesgroup@gmail.com

🌐 http://www.bgesgroup.com

Protect your projects, your profits, and your peace of mind—with BGES Group by your side.

Navigating Scaffolding Insurance Options for Contractors in the Northeast

Scaffolding projects come with their unique set of challenges and risks, especially for contractors in the busy Northeast. Navigating insurance options can feel overwhelming, but it’s crucial for protecting yourself and your business. In this guide, we’ll break down the essential aspects of scaffolding insurance to help contractors make informed decisions.

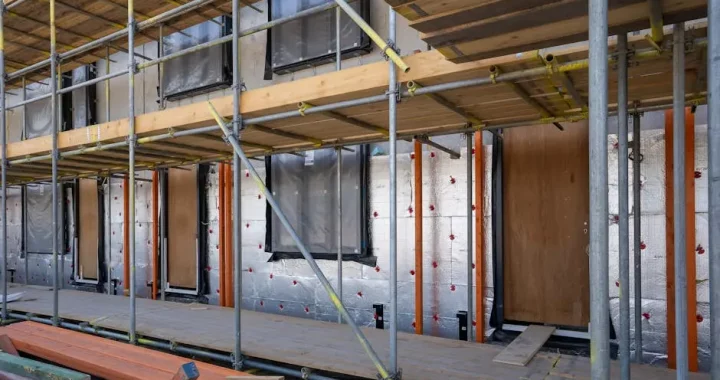
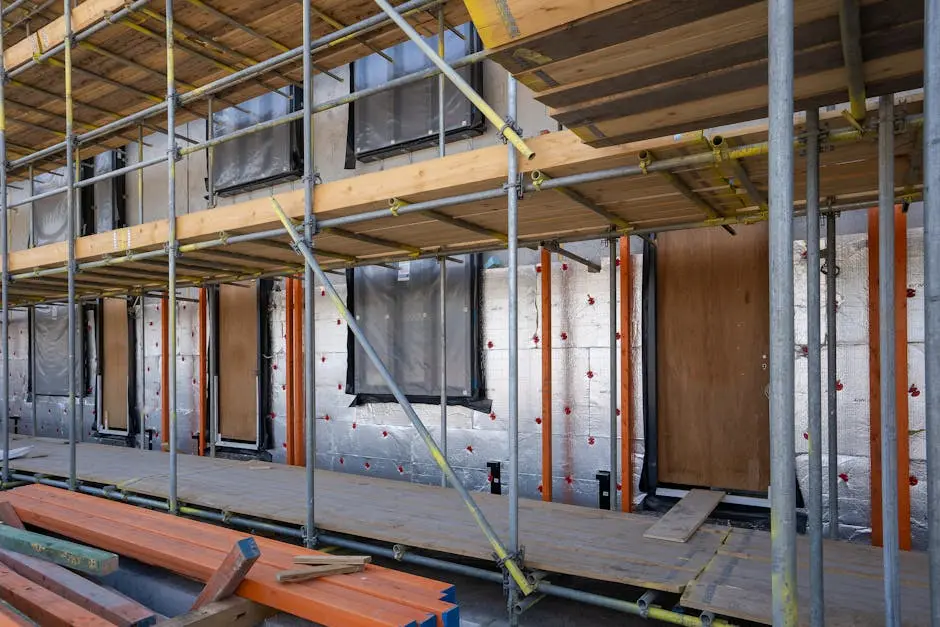
Scaffolding at a residential building under construction with windows and insulation sheets visible.

Understanding the Basics of Scaffolding Insurance

To effectively navigate scaffolding insurance, contractors first need to understand what it covers. Primarily, this type of insurance protects against damages, accidents, and liabilities specifically associated with scaffolding work. It includes coverage for both property damage and bodily injury, which are common risks in this line of work.

Scaffolding insurance is not just a one-size-fits-all policy. Different projects may require various types of coverage depending on specific needs. For example, if you’re working on a large-scale commercial building, you might need a policy that includes higher coverage limits compared to a smaller residential project. This insurance usually covers accidents like unforeseen structural failures or falling objects that may lead to severe injuries and property damage.

Moreover, scaffolding insurance often includes protection against legal fees if a lawsuit arises from an accident on-site. Legal battles can be incredibly expensive, and having an insurance policy that defends your business in such situations offers peace of mind. It’s essential that contractors understand these basics to ensure they have the correct level of coverage.

Assessing Your Business Risks

Every scaffolding project carries unique risks that can vary based on the scope, location, and duration of the job. Contractors should perform a thorough risk assessment to identify potential hazards and determine the necessary coverage limits. This process helps in selecting a policy that sufficiently protects against the most significant risks your projects may encounter.

For instance, projects situated in densely populated urban areas may increase the risk of third-party injuries, highlighting the need for public liability insurance. Conducting a detailed risk assessment involves examining the project environment, identifying potential hazards such as unstable ground or weather conditions, and determining the potential impact of such risks.

It’s also crucial to take into account the qualifications and experience of your workforce. Less experienced workers may pose higher risks of accidents, necessitating more comprehensive coverage. By thoroughly assessing all these factors, contractors can tailor their insurance plans to effectively manage potential risks.

Choosing the Right Insurance Coverage

Once the risks have been assessed, contractors can explore different types of insurance coverage such as general liability, workers’ compensation, and equipment insurance. Each type serves a different purpose, and understanding their benefits is key to ensuring comprehensive protection. Consulting with an experienced insurance agent can provide tailored advice for your specific needs.

General liability insurance is essential as it covers third-party bodily injury and property damage claims. This is particularly crucial when dealing with scaffolding, given the increased odds of accidents. Meanwhile, workers’ compensation covers medical expenses and lost wages if an employee is injured on the job—a vital coverage that helps preserve your workforce while protecting your business from financial ruin.

In addition to these primary insurance types, contractors might also consider inland marine insurance for equipment protection. This is particularly useful for safeguarding valuable tools and scaffolding materials during transport or while on-site. By mixing and matching these insurance types based on assessed risks, contractors can craft a comprehensive and customized policy.

Considering Regional Regulations and Requirements

The Northeast has specific regulatory requirements that scaffolding contractors must adhere to. Understanding local laws concerning scaffolding operations and insurance is crucial for compliance and avoiding penalties. Keeping abreast with these regulations ensures that your projects run smoothly and legally.

For instance, some states may require contractors to have certain certifications or permits before undertaking scaffolding work. These regulations vary widely, making it essential for contractors to stay informed about the guidelines relevant to each project location. State-specific health and safety standards can affect insurance requirements, so compliance not only helps maintain legal operations but can also influence insurance rates.

Moreover, some regions may mandate minimum insurance coverage levels, particularly in public works or highly regulated industries. As regulations often update, having a point of contact in regional regulatory bodies or industry groups can be beneficial for receiving timely updates. Staying informed and compliant is the best way to avoid costly interruptions or legal issues.

Evaluating Insurance Providers

Not all insurance providers are the same. When comparing providers, consider their experience with scaffolding projects, their claims process, and customer service reputation. Reviews and recommendations from fellow contractors can also be invaluable in making an informed choice that offers the best coverage and support.

A provider with a specific focus on construction insurance often understands the unique needs and challenges of scaffolding work. Their experience can translate into more accurate risk assessments and potentially lower premiums. It’s also worthwhile to compare turnaround times for claims processing and any additional services like risk management consulting.

Capturing the testimonials and case studies of other contractors who have successfully navigated claims with particular providers can offer insight into what you might expect. A good insurance partner is not just a policy provider but a supporter through the myriad challenges of scaffolding work.

Securing the Right Protection for Your Business

Understanding the nuances of scaffolding insurance is essential for contractors in the Northeast to safeguard their business operations. By assessing your risks, selecting the right coverage, and staying compliant with regional regulations, you can ensure a solid safety net for your company. Remember, the right insurance is more than just a policy—it’s a vital component of your business strategy. To learn more about how BGES Group can assist you with your insurance needs, visit our homepage today.

BGES Group is one of New York, New Jersey, and Connecticut’s Construction Insurance Specialists representing 50+ companies, including all the BEST general & umbrella liability programs. We offer all the coverage needed, including property, builders’ risk, inland marine, general liability, umbrella liability, auto, bid & performance bonds, workers’ compensation, N.Y.S. disability, and group health.  Our commitment to you goes beyond the policies we provide. We are always just a call, text, or email away, ready to assist you, even on weekends. We understand the importance of your business and are here to help you navigate any insurance challenges. 
 
BGES Group are Workers’ Compensation Insurance Specialists for Tri-State Business Owners: Unhappy with your rates, company, being canceled, losses causing difficulty getting coverage, in the middle of an audit dispute, misclassified payrolls, or whatever your issue. We can help!  We have special programs for Auto Services, Contractors (especially in New York), Limousine Services, Logistics Companies, Manufacturers, Recyclers, and Truckers; we can help ANY tri-state business owner. We are considered “Preferred Agents” for this one program that, if we can get you into, their pricing is excellent, offers long-term coverage stability, and can cover multi-state operations. The program takes the hassle out of doing annual audits, too. 
 
If you want to speak with us, call Gary Wallach at 914-806-5853, click here to email, or visit our website.
 
Company: BGES Group, 216A Larchmont Acres West, Larchmont, NY 10538

email: bgesgroup@gmail.com

website: http://www.bgesgroup.com


Understanding the Importance of Electrician Insurance in New York

Navigating the electrical industry in New York can be a complex yet rewarding endeavor. However, it’s crucial to ensure that you’re protected against potential risks. This is where electrician insurance comes into play. In this blog, we’ll explore why electrician insurance is vital for professionals in this field and how it can safeguard both your business and your clients.

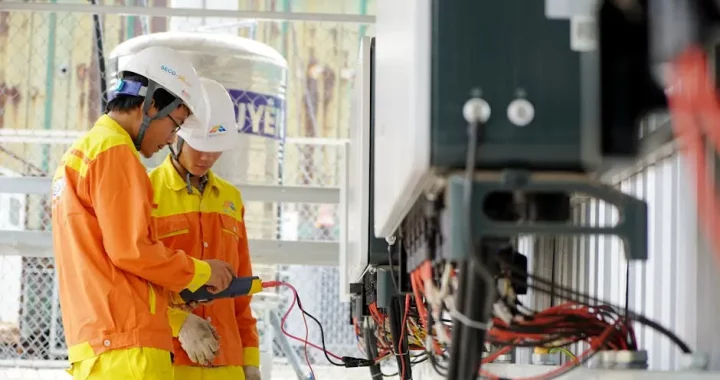
Two technicians with helmets working on electrical equipment outdoors, ensuring safety.

What Is Electrician Insurance?

Electrician insurance is a tailored policy designed to protect electricians from the specific risks associated with their trade. This can include general liability, professional liability, and workers’ compensation, among others. For instance, general liability insurance covers claims related to third-party injuries or damages that could occur during your work, while professional liability is crucial in the event of errors or negligence in your services.

One might wonder why electricians in New York require such comprehensive insurance. The reality of working in this trade involves dealing with a variety of hazards, from electrical failures to accidents involving clients or employees. Thus, having a robust insurance plan can be the lynchpin in managing unforeseen events effectively, allowing electricians to work with peace of mind, knowing they are adequately protected.

In New York, electricians must adhere to strict licensing and insurance requirements. Understanding these mandates not only keeps you compliant but also ensures you’re covered for potential mishaps or liabilities. New York State requires electricians to carry both a valid license and adequate insurance, including workers’ compensation and disability benefits if they employ others.

Being informed about local regulations is crucial. The city’s licensing protocols are designed to ensure that electrical work adheres to safety standards, minimizing risks for both workers and consumers. Failing to comply can not only lead to hefty fines but also potentially damage the electrician’s reputation and business.

Types of Coverage Electricians Need

From property damage to injury claims, having the right insurance coverage is essential. Explore the various types of coverage available, including general liability and equipment coverage, to find what suits your business best. General liability insurance, for instance, covers third-party injuries, while equipment coverage helps in cases of tool and machinery loss or theft.

Beyond just basic liabilities, additional coverage like inland marine insurance might be essential for electricians who frequently transport tools and equipment. This type of insurance ensures that your assets are protected on the go, offering peace of mind.

Benefits of Having Electrician Insurance

Insurance provides more than just security; it offers peace of mind to you and your clients. Explore the myriad benefits, such as financial protection and enhanced credibility, that electrician insurance can bring to your business. Clients often prefer insured electricians, viewing them as more reliable and professional.

Moreover, having insurance can set you apart from competitors. It’s an investment in your company’s reputation, demonstrating a commitment to safety and reliability that can lead to more job opportunities and client trust in the long run.

Choosing the Right Insurance Provider

Selecting the right insurance provider can impact the effectiveness of your coverage. We’ll discuss tips on evaluating potential insurers and choosing a provider that meets your specific needs. It’s essential to assess providers’ reputations, review policy options, and compare rates to ensure that the insurer can cover the unique risks associated with electrical work efficiently.

A good starting point is to seek recommendations from industry peers or browse through third-party reviews. Trust and reliability should be a priority when deciding who will provide you with this crucial support for your business.

Safeguarding Your Electrical Business in New York

In a city as dynamic as New York, having the right insurance is not just a good idea—it’s a necessity. Electrician insurance acts as a safety net, providing peace of mind so you can focus on growing your business. By understanding and securing the appropriate coverage, you’re taking a vital step towards protecting your livelihood and ensuring long-term success. For more information on safeguarding your business, visit the BGES Group homepage.

BGES Group is one of New York, New Jersey, and Connecticut’s Construction Insurance Specialists representing 50+ companies, including all the BEST general & umbrella liability programs. We offer all the coverage needed, including property, builders’ risk, inland marine, general liability, umbrella liability, auto, bid & performance bonds, workers’ compensation, N.Y.S. disability, and group health.  Our commitment to you goes beyond the policies we provide. We are always just a call, text, or email away, ready to assist you, even on weekends. We understand the importance of your business and are here to help you navigate any insurance challenges. 
 
BGES Group are Workers’ Compensation Insurance Specialists for Tri-State Business Owners: Unhappy with your rates, company, being canceled, losses causing difficulty getting coverage, in the middle of an audit dispute, misclassified payrolls, or whatever your issue. We can help!  We have special programs for Auto Services, Contractors (especially in New York), Limousine Services, Logistics Companies, Manufacturers, Recyclers, and Truckers; we can help ANY tri-state business owner. We are considered “Preferred Agents” for this one program that, if we can get you into, their pricing is excellent, offers long-term coverage stability, and can cover multi-state operations. The program takes the hassle out of doing annual audits, too. 
 
If you want to speak with us, call Gary Wallach at 914-806-5853, click here to email, or visit our website.
 
Company: BGES Group, 216A Larchmont Acres West, Larchmont, NY 10538

email: bgesgroup@gmail.com

website: http://www.bgesgroup.com


Why New York Contractors Are Ditching Traditional Workers’ Comp Policies for PEOs — And Saving Big

If you’re a New York contractor who does most of your work under wrap-up projects (OCIPs or CCIPs), you already know the nightmare that comes with your workers’ compensation insurance audit. You spend months sending proof after proof to show that your payroll should be excluded because the general contractor’s policy covers your workers’ comp. Yet somehow, the audit always drags on — or ends with you overpaying.

There’s a smarter, simpler way: move your workers’ compensation and payroll to a Professional Employer Organization (PEO). Below are ten major ways doing this can benefit your business — financially, operationally, and mentally.

⸻

1. End the Audit Headache

PEOs manage workers’ compensation audits for you. Because they handle payroll and workers’ comp under their own federal employer identification number (FEIN), you’re no longer the one being audited. That means no more gathering payroll reports, job lists, certificates of insurance, and OCIP documentation every year. The PEO takes care of it all.

⸻

2. No More Double Charging for Wrap-Up Work

One of the biggest problems with traditional insurance audits is that they often don’t properly exclude wrap-up (OCIP/CCIP) payrolls. Even when you prove that your employees were covered by the GC’s policy, those payrolls can still show up in your premium calculation until you fight it out.

With a PEO, your payroll is managed in real time, and wrap-up exclusions are applied automatically — ensuring accurate, fair billing from the start.

⸻

3. Stable, Predictable Premiums

Traditional workers’ comp policies fluctuate based on estimates, classifications, and claims. PEOs offer flat, predictable pricing based on your actual payroll each pay period. You’ll know exactly what you’re paying — no surprise bills at year-end.

⸻

4. Lower Workers’ Comp Costs

Most PEOs have master workers’ comp policies with top-rated carriers. Because they pool many employers under one large policy, they negotiate lower rates than a single contractor could get alone. The savings can be substantial — especially if your payroll varies throughout the year.

⸻

5. Compliance Made Easy

PEOs stay on top of New York’s complex labor and workers’ compensation regulations. They make sure your business complies with all wage, reporting, and coverage requirements — reducing your risk of penalties or cancellations.

Article content

6. Pay-As-You-Go Premiums

Instead of paying large upfront deposits or estimated premiums, PEOs use pay-as-you-go billing. Premiums are calculated on actual payroll every pay period, which improves cash flow and eliminates big audit adjustments.

⸻

7. Professional Payroll & HR Support

When you join a PEO, you’re not just getting insurance — you’re getting an entire support team. PEOs handle payroll processing, tax filing, new-hire reporting, and even HR compliance. That means you can focus on managing jobs instead of chasing paperwork.

⸻

8. Better Coverage Options

Many PEOs offer access to large-group employee benefits — including health, dental, vision, and 401(k) plans. Small and mid-sized contractors often can’t get these benefits on their own, but through a PEO, you can attract and retain skilled labor more easily.

⸻

9. Improved Safety and Risk Management

PEOs employ safety experts who can help you develop safety manuals, training programs, and jobsite inspections. This proactive approach lowers claim frequency, improves your safety record, and helps reduce long-term costs.

⸻

10. Peace of Mind and Time Savings

Imagine not having to deal with audit disputes or endless proof-of-coverage requests every year. With a PEO, everything is streamlined — one invoice, accurate payrolls, and professionals managing compliance behind the scenes. That peace of mind is worth its weight in gold.

⸻

Why More New York Contractors Are Making the Switch

For contractors who do mostly wrap-up work, the PEO model is a no-brainer. You avoid being double-charged for payroll already covered under OCIP/CCIP, eliminate audit battles, and gain expert HR and payroll support.

You’ll have more time to focus on growing your business instead of managing your insurance company.

⸻

How BGES Group Can Help

At BGES Group, we specialize in helping New York contractors find smarter, more efficient workers’ compensation solutions — including the right PEOs for construction. We’ll review your policy, wrap-up exposure, and payroll structure to determine how much you can save and simplify your operations.

Our team has over 44 years of experience helping contractors throughout New York, New Jersey, and Connecticut lower costs and eliminate audit headaches.

Contact BGES Group today:

📞 Gary Wallach – 914-806-5853

📧 bgesgroup@gmail.com

🌐 http://www.bgesgroup.com

Stop overpaying and overworking for your insurance company. Let BGES Group show you how the right PEO can make your workers’ comp simple, affordable, and stress-free.

15 Common Misconceptions About Workers’ Compensation Insurance NJ

Navigating the world of workers’ compensation insurance can be daunting, especially with so many misconceptions floating around. Whether you’re an employer or an employee in New Jersey, understanding the real facts can help you make informed decisions. Let’s clear up some of the most common myths associated with workers’ compensation insurance in NJ.1. Coverage Is Optional for Small Businesses

Many believe that only large businesses are required to have workers’ compensation insurance. In reality, most businesses in NJ, regardless of size, must carry insurance to protect their employees. New Jersey law requires that all employers, even those with just one employee, obtain workers’ compensation coverage. This requirement underscores the importance of this protection in maintaining workplace safety and supporting injured workers during recovery.

Small business owners might overlook the nuances of coverage due to misinterpretation. It’s essential for smaller establishments to comprehend that exemptions are rare and specific. While sole proprietors without employees might not need to purchase a policy, hiring just one person changes everything. Getting informed not only safeguards employees but also shields business owners from potential legal repercussions that can arise from non-compliance.

2. Insurance Only Covers Serious Injuries

Contrary to popular belief, workers’ compensation covers a range of injuries, from minor sprains to more severe conditions. It’s important to report and file a claim for any workplace injury. Whether an injury happens gradually over time, such as carpal tunnel syndrome, or is an acute incident, like a fall, reporting it promptly can be crucial in determining the validity of a claim.

The misconception might stem from the dramatic portrayal of workplace accidents in media. In truth, everyday incidents like slipping on a wet floor or straining a muscle while lifting can all be legitimate claims. The breadth of coverage ensures that workers can focus on recovery rather than worrying about hefty medical bills. Awareness and education about the kinds of injuries covered can promote a more supportive work environment.

3. Workers’ Compensation Claims Are Always Approved

There is a misconception that filing a claim guarantees approval. However, claims can be denied if they don’t meet certain criteria, underscoring the importance of accurate and detailed reporting. Factors such as timely submission, proof of work-related causation, and documented medical evaluations play a critical role in the approval process.

This myth can discourage employees from understanding the rigorous processes involved in claims evaluation. Awareness of potential denial reasons, such as incomplete information or lack of evidence, can empower them to compile a more robust case. To navigate this system more effectively, workers are encouraged to maintain comprehensive records and consult with professionals if needed.

4. Employees Don’t Need to Inform Employers About Injuries

In reality, timely reporting is crucial. Employees should inform their employers as soon as an injury occurs to ensure proper processing of their claim. Delaying this notification might hinder the employer’s ability to conduct necessary investigations and corroborate facts, potentially complicating the claims process.

Clear communication channels within organizations can facilitate smoother claim submissions. Employees may worry about repercussions, but legal provisions shield them against any prejudicial treatment following an injury report. Therefore, prioritizing transparency and prompt action benefits both the injured worker and the business’s operational continuity.

5. Employers Can Discriminate Against Injured Employees

Some believe that employers can retaliate against employees who file claims. However, this is illegal and employees are protected under state and federal laws. The New Jersey Workers’ Compensation Law expressly forbids any discriminatory actions against workers exercising their rights.

The fear of unfair treatment often prevents employees from pursuing rightful benefits. It’s important for employers to cultivate a culture of trust where employees feel safe to report incidents without fear. Employers should also stay informed about legal obligations, ensuring policies are in place to prevent even unintentional discrimination.

BGES Group is one of New York, New Jersey, and Connecticut’s Construction Insurance Specialists representing 50+ companies, including all the BEST general & umbrella liability programs. We offer all the coverage needed, including property, builders’ risk, inland marine, general liability, umbrella liability, auto, bid & performance bonds, workers’ compensation, N.Y.S. disability, and group health.  Our commitment to you goes beyond the policies we provide. We are always just a call, text, or email away, ready to assist you, even on weekends. We understand the importance of your business and are here to help you navigate any insurance challenges. 
 
BGES Group are Workers’ Compensation Insurance Specialists for Tri-State Business Owners: Unhappy with your rates, company, being canceled, losses causing difficulty getting coverage, in the middle of an audit dispute, misclassified payrolls, or whatever your issue. We can help!  We have special programs for Auto Services, Contractors (especially in New York), Limousine Services, Logistics Companies, Manufacturers, Recyclers, and Truckers; we can help ANY tri-state business owner. We are considered “Preferred Agents” for this one program that, if we can get you into, their pricing is excellent, offers long-term coverage stability, and can cover multi-state operations. The program takes the hassle out of doing annual audits, too. 
 
If you want to speak with us, call Gary Wallach at 914-806-5853, click here to email, or visit our website.
 
Company: BGES Group, 216A Larchmont Acres West, Larchmont, NY 10538

email: bgesgroup@gmail.com

website: http://www.bgesgroup.com


Navigating General Contractor Insurance NY: Tips and Tricks

Navigating the world of insurance as a general contractor in New York can be daunting. With so many options and requirements, it can be hard to know where to start. This guide aims to break down the essentials of general contractor insurance in NY, making it easier for you to make informed decisions that protect your business and give you peace of mind.Understanding the Basics of General Contractor Insurance

General contractor insurance is like a safety net for your business. The right coverage can protect you from a range of unforeseen events, from property damage and injuries at the job site to lawsuits and other liabilities. But what does this insurance typically include? It encompasses several key areas: liability insurance, which covers damages that your work might cause to third parties; property insurance, safeguarding your tools and workspace; and workers’ compensation, which is crucial in protecting your employees.

In addition to the typical components, some policies might offer more specialized options. Equipment insurance can protect your machinery and tools against specific risks, while builder’s risk insurance covers buildings under construction in case of eventualities like fire or theft. Understanding these elements can help you tailor coverage to your specific needs. Therefore, it’s essential to review your policy thoroughly and consult with a knowledgeable insurance agent to ensure you’re fully protected in all areas pertinent to your business operations.

The Importance of Compliance: NY State Requirements

New York State has stringent regulations when it comes to contractor insurance. One of the first things you’ll need to consider is workers’ compensation, which is mandatory for all employees. Without it, you could face hefty fines and legal issues. Additionally, general liability insurance is typically required as a part of contractor licensing. This protects your business from claims arising from bodily injury or property damage resulting from your work.

To comply with New York’s specific requirements, stay updated on changes in legislation and industry standards. For example, certificates of insurance may need to be presented to clients or regulatory bodies to verify that your business is compliant. It’s also wise to build relationships with local insurance agents who are familiar with state laws and can provide insights tailored to the NY market.

Choosing the Right Insurance Provider

When selecting an insurance provider, it’s important to look beyond the price tag. A good provider should have a solid reputation and be financially stable, so check their ratings and reviews from other contractors in your industry. Customer service is another crucial factor – you need to be sure that they will respond quickly and efficiently when you file a claim. Consider meeting with several providers to compare their policy offerings and find one that meets your specific needs.

Don’t forget to inquire about add-ons and extra features that could benefit your business. Some insurers offer risk management advice and tailored insurance plans that might suit your work specifics better. Additionally, verify if they provide online platforms or tools for easier policy management, which can be highly beneficial for monitoring your coverage and claims.

Tips for Managing Your Insurance Effectively

Effective management of your insurance policies is key to maximizing their benefits. Start by scheduling regular policy reviews, especially after your business grows or changes its operations, to ensure your coverage evolves with your needs. You should also regularly update your assets list and notify your insurer about any changes. This guarantees that all your tools and vehicles are covered and can help prevent gaps in protection.

Furthermore, bundling different types of insurance with one provider might result in cost savings due to discounts. Engaging with forums or networking within the industry can provide insights into the best practices for insurance management. Keeping open communication lines with your provider can also facilitate smoother claims processes when unexpected situations arise.

Securing Your Business: The Final Word

Understanding general contractor insurance is essential for protecting your business and ensuring compliance with New York regulations. By familiarizing yourself with the types of insurance, knowing your state’s specific requirements, and choosing a plan that suits your business, you can operate with confidence and focus on the work you love.

BGES Group is one of New York, New Jersey, and Connecticut’s Construction Insurance Specialists representing 50+ companies, including all the BEST general & umbrella liability programs. We offer all the coverage needed, including property, builders’ risk, inland marine, general liability, umbrella liability, auto, bid & performance bonds, workers’ compensation, N.Y.S. disability, and group health.  Our commitment to you goes beyond the policies we provide. We are always just a call, text, or email away, ready to assist you, even on weekends. We understand the importance of your business and are here to help you navigate any insurance challenges. 
 
BGES Group are Workers’ Compensation Insurance Specialists for Tri-State Business Owners: Unhappy with your rates, company, being canceled, losses causing difficulty getting coverage, in the middle of an audit dispute, misclassified payrolls, or whatever your issue. We can help!  We have special programs for Auto Services, Contractors (especially in New York), Limousine Services, Logistics Companies, Manufacturers, Recyclers, and Truckers; we can help ANY tri-state business owner. We are considered “Preferred Agents” for this one program that, if we can get you into, their pricing is excellent, offers long-term coverage stability, and can cover multi-state operations. The program takes the hassle out of doing annual audits, too. 
 
If you want to speak with us, call Gary Wallach at 914-806-5853, click here to email, or visit our website.
 
Company: BGES Group, 216A Larchmont Acres West, Larchmont, NY 10538

email: bgesgroup@gmail.com

website: http://www.bgesgroup.com

7 Key Factors to Consider When Choosing Builders Risk Insurance

Choosing the right builders risk insurance is crucial for protecting your construction project. It ensures that you’re covered against a variety of risks while building or renovating. Whether you’re a seasoned contractor or a first-time builder, understanding what to look for in a policy can save you time and money. Here, we’ll explore the key factors you should consider when selecting builders risk insurance.

Smiling female engineer in protective gear at an outdoor construction site.

1. Understanding Coverage Options

The first step in choosing builders risk insurance is to understand what the policy covers. Typically, it should protect materials, fixtures, and equipment on-site against damage or theft. Knowing these details helps you ensure that your policy is comprehensive and fits your project needs.

Builders risk insurance can also extend to cover temporary structures and scaffolding, which are key components of many construction projects. Depending on your specific needs, additional coverage can be included to handle unique aspects, such as transportation and storage of materials offsite. It’s crucial to carefully consider which coverage options are most beneficial for your project to avoid potential gaps.

2. Evaluating Policy Limits

Policy limits define the maximum amount your insurer will pay in the event of a claim. Assess both the value of your project and the policy limits offered to ensure there is adequate coverage. This consideration is crucial for avoiding unexpected financial burdens during construction.

Beyond the basic limits, consider whether your policy includes extensions for cost escalations and delays, which can be crucial in safeguarding against inflation or unforeseen price hikes in materials. Such extensions could increase your total coverage without a proportionate increase in your premium, offering strategic protection against unforeseen costs.

3. Considering Exclusions and Restrictions

Every builders risk insurance policy comes with specific exclusions. These exclusions can significantly impact your coverage. Review policy documents carefully to understand situations or items that may not be covered, such as certain natural disasters or faulty workmanship.

Moreover, policy exclusions can often involve subcontractors and their errors, which are frequent in construction projects. Knowing how exclusions apply to third-party work is vital, as these areas might leave substantial portions of your project vulnerable. Always explore options for additional insurance to cover gaps where the primary policy might not offer protection.

4. Assessing the Duration of Coverage

The duration of coverage is another critical factor. Builders risk insurance typically lasts until the project is completed or occupied. Ensure your policy timeline aligns with the expected completion date to avoid any gaps in coverage.

Should your project face unexpected delays, extended coverage can be crucial, allowing you to focus on completion without the stress of unprotected periods. Consider scenarios like material shortages or labor disputes, which might necessitate extended coverage options to protect your financial interests throughout the construction.

5. Considering the Insurer’s Reputation

Selecting a reputable insurance provider is as important as the policy itself. Research potential insurers’ histories, financial stability, and customer reviews to ensure they can deliver on claims efficiently and effectively.

Reputation matters, particularly in the building industry, where swift service can make or break project timelines. Look into how insurers handle claim settlements and what their past clients have to say about responsiveness, ensuring you partner with a provider who backs their promises.

6. Understanding the Claims Process

A clear understanding of the claims process can save you time and stress should a claim need to be made. Look for insurers with straightforward claim procedures and responsive customer service to facilitate swift resolution.

Insurers that offer digital tools for claims processing can greatly enhance your experience, allowing for more agility and transparency during a potentially stressful time. Therefore, it’s advantageous to choose an insurer that offers seamless digital claims processes, minimizing paperwork and expediting the overall procedure.

7. Comparing Costs and Premiums

While cost shouldn’t be the sole deciding factor, it’s crucial to compare premiums across providers. Weigh the costs against the coverage offered to ensure you’re receiving the best value without compromising on essential protections.

Different projects may qualify for varying premium rates based on risk assessment, project scope, location, and other factors. Consulting expert advice can help you determine which plans offer the best pricing structures for your specific requirements, ensuring cost-efficiency alongside robust risk management.

BGES Group is one of New York, New Jersey, and Connecticut’s Construction Insurance Specialists representing 50+ companies, including all the BEST general & umbrella liability programs. We offer all the coverage needed, including property, builders’ risk, inland marine, general liability, umbrella liability, auto, bid & performance bonds, workers’ compensation, N.Y.S. disability, and group health.  Our commitment to you goes beyond the policies we provide. We are always just a call, text, or email away, ready to assist you, even on weekends. We understand the importance of your business and are here to help you navigate any insurance challenges. 
 
BGES Group are Workers’ Compensation Insurance Specialists for Tri-State Business Owners: Unhappy with your rates, company, being canceled, losses causing difficulty getting coverage, in the middle of an audit dispute, misclassified payrolls, or whatever your issue. We can help!  We have special programs for Auto Services, Contractors (especially in New York), Limousine Services, Logistics Companies, Manufacturers, Recyclers, and Truckers; we can help ANY tri-state business owner. We are considered “Preferred Agents” for this one program that, if we can get you into, their pricing is excellent, offers long-term coverage stability, and can cover multi-state operations. The program takes the hassle out of doing annual audits, too. 
 
If you want to speak with us, call Gary Wallach at 914-806-5853, click here to email, or visit our website.
 
Company: BGES Group, 216A Larchmont Acres West, Larchmont, NY 10538

email: bgesgroup@gmail.com

website: http://www.bgesgroup.com


Need Help Getting New Workers’ Compensation Insurance? Here Are 15 Reasons Why BGES Group Is Your Best Choice

Finding affordable, reliable workers’ compensation insurance can feel like navigating a maze. Between state requirements, confusing forms, audit risks, and constant insurer changes, many business owners end up frustrated and paying more than they should. Whether your current policy has been canceled, your premiums have skyrocketed, or your broker stopped returning calls, you’re not alone.

At BGES Group, we specialize in helping small and mid-sized businesses — especially New York contractors — get back on track fast with the right coverage, the right insurer, and the right support. Below are 15 reasons why you should make BGES Group your first call when you need help getting new workers’ compensation insurance.


1. We Help You Get Reinstated Quickly After a Lapse

If your policy has been canceled for nonpayment or audit issues, time is critical. BGES Group understands the reinstatement process inside and out. We guide you step-by-step so you can get your policy back in force — or, if reinstatement isn’t possible, we’ll find a new carrier fast to avoid uncovered exposure or penalties.

2. We Work Directly with NYSIF and Private Carriers

Navigating the New York State Insurance Fund (NYSIF) can be a challenge, but we know how to make the system work for you. Whether you need to get unblocked from online payments, reapply after a lapse, or move to a private carrier for better rates, BGES Group has you covered.

3. We Specialize in Construction Accounts

No one knows construction insurance like BGES Group. From general contractors and framers to painters, electricians, and small renovation firms, we understand your trade, your contracts, and your compliance requirements. You’ll get coverage that meets what general contractors, property owners, and municipalities require — without overpaying.

4. We Handle Tough-to-Place Risks

Has another broker told you your business is “too risky”? BGES Group thrives on challenges. We work with specialized markets that insure businesses others turn away. Whether you’ve had claims, lapses, or high experience mods, we’ll find a carrier willing to work with you.

5. We Can Save You Thousands

Our clients routinely save 20–40% compared to what they were paying before. We don’t just quote one company — we compare multiple insurers and help you choose the best combination of coverage and price.

6. We Simplify the Process

No endless paperwork. No confusing emails. BGES Group makes applying for coverage simple and fast. You’ll know exactly what’s needed, and we’ll help you complete it quickly so there’s no delay in getting coverage bound.

7. We Make Sure You Stay Compliant

Workers’ compensation is not just about protection — it’s a legal requirement. We make sure you meet all state and contract compliance rules so you can avoid costly fines or stop-work orders. Need a Certificate of Insurance same-day? We can deliver it fast.

8. Personalized Service – You’re Never Just a Number

At BGES Group, you work directly with an experienced insurance professional who knows your business — not a call center. We believe in old-fashioned service: quick responses, clear answers, and real people who care.

9. Fast Certificates and Endorsements

When you need a certificate of insurance, additional insured wording, or a waiver of subrogation for a project, speed matters. We pride ourselves on turning requests around quickly so your work isn’t held up waiting for paperwork.

10. We Help You Avoid Audit Headaches

Workers’ comp audits can be stressful — but not when you have BGES Group in your corner. We help you prepare, organize your records, and avoid unnecessary charges. We’ll even review your audit results and dispute errors when necessary.

11. We Understand Experience Mods and How to Lower Them

Your experience modification factor (mod) can make or break your premiums. We’ll explain how it works, how claims impact your rating, and what steps you can take to lower it over time. Our goal is not just to get you insured, but to help you pay less every year.

12. We Can Bundle General Liability and Workers’ Comp

Many clients save more by combining their workers’ compensation and general liability policies. We’ll find packages that make sense for your business and can often secure multi-policy discounts.

13. We Work with Startups and New Ventures

Starting a new business and need workers’ compensation for the first time? BGES Group makes it easy. We’ll help you register, file the necessary applications, and secure coverage even if you don’t have payroll yet.

14. We Protect You from Policy Gaps

A gap in coverage can lead to major problems — from stop-work orders to uncovered employee injuries. We make sure your coverage is continuous, properly classified, and structured so you’re never exposed.

15. We’re Trusted by Hundreds of New York Businesses

BGES Group has been serving New York businesses for over 44 years. Our clients stay with us because we deliver what we promise — responsiveness, professionalism, and real results. Many clients have been with us for over a decade because they know we always have their back.


Why Working with BGES Group Makes the Difference

Many insurance brokers today operate like online sales machines. They quote quickly but don’t stick around when problems arise. BGES Group is different — we’re advocates for our clients.

We step in when the carrier makes a mistake, when your audit seems unfair, or when you’re struggling with state paperwork. We talk directly to underwriters, claims adjusters, and compliance officers on your behalf. You’ll never have to handle those frustrations alone again.

When you work with BGES Group, you’re getting more than an insurance policy — you’re getting a partner who’s genuinely invested in your success.

We don’t just sell coverage; we solve problems.


Who We Help

  • Construction contractors (general, roofing, electrical, painting, masonry, HVAC, and more)
  • Small businesses with payroll challenges or coverage lapses
  • Companies transitioning from the assigned risk or NYSIF to private carriers
  • New ventures looking to get workers’ comp for the first time

Whether you’re a one-person operation or a business with dozens of employees, we can tailor a plan that fits your needs — and your budget.


Our Process

  1. Consultation: We review your current policy, payroll, and claims.
  2. Strategy: We identify the best carriers for your situation.
  3. Quote: You receive clear, competitive quotes with transparent explanations.
  4. Placement: We bind coverage and issue certificates fast.
  5. Support: We help you through audits, renewals, and compliance.

Every step is handled with personal care and urgency — because we know your business depends on it.


Contact BGES Group Today

If you’re struggling to get new workers’ compensation insurance, or your old broker can’t deliver the help you need, reach out today. Let us do the heavy lifting so you can focus on running your business.

📞 Call: (914) 806-5853
📧 Email: bgesgroup@gmail.com
🌐 Website: www.bgesgroup.com

BGES Group — Helping New York Businesses Stay Protected, Compliant, and Confident for Over 44 Years.